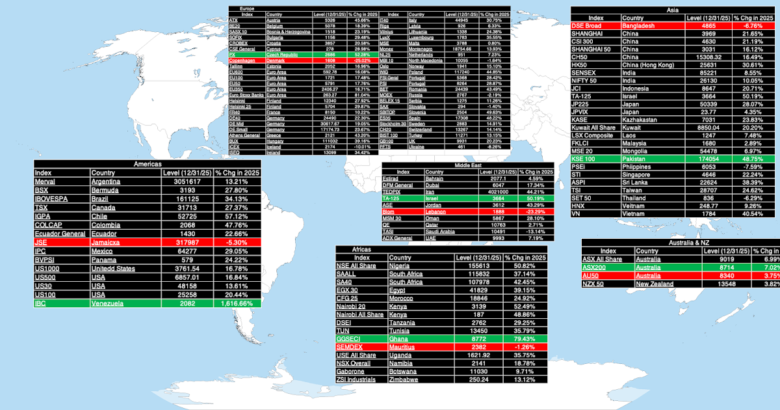
In every area, I’ve highlighted the very best performing index (in inexperienced) and worst performing one (in pink), and you’ll see the disparities in market efficiency, even inside areas. One of many issues with evaluating returns throughout currencies is that they’re distorted by the consequences of inflation that additionally fluctuate broadly throughout currencies. Whereas I’ll take a look at inflation variations in additional element later on this put up, one strategy to make the returns comparable is to recompute them in a typical forex. To this finish, I compute the greenback returns, in combination greenback market capitalization phrases, in 2025:
As I discussed in my second information replace, India was the worst performing sub-region of the world, up solely 3.31% in 2025, and people returns replicate not only a comparatively below-average yr in native forex phrases, with the Sensex up 8.55% for the yr, however a weaker forex, with the rupee depreciating towards the greenback. It’s only one yr and whereas I’ll want learn an excessive amount of into it, my argument earlier final yr that the India story has legs, however that the trail to delivering will probably be rockier than lots of its advocates appear to factor. For a lot of the remainder of the world, the greenback returns are larger than native forex returns, due to forex appreciation towards the greenback.
Zeroing in on the mixture market capitalization the world over in the beginning of 2026, I first created a pie chart (on the left) breaking market capitalization by area, and as you’ll be able to see, US equities, despite a weaker greenback, accounted for 47% of world market capitalization.
Evaluating simply the change in market capitalization throughout 2025, within the second pie (not he proper), you’ll be able to see the rationale for the slippage within the US hare, with the US punching in beneath its weight (38% of the change) and Europe and China weighing in, with bigger shares.
To shut this part, I’ll unwrite an epitaph for worldwide diversification that many US buyers, wealth advisors and market consultants have been beginning to etch in stone even a yr in the past. For a lot of the twenty first century, an investor invested totally in US shares would have outperformed one who adopted the textbook recommendation to diversify globally. Whereas that will look sound conclusive, the reality is that 20 years isn’t a very long time interval in inventory market historical past and you can have prolonged market runs that look everlasting, even when they don’t seem to be. It’s true that as multinationals displace home corporations, the payoff to worldwide diversification has turn out to be smaller over time; shopping for the S&P 500 would have purchased your publicity to the worldwide economic system, because the corporations within the index, whereas integrated within the US, get virtually 60% of their revenues in the remainder of the world. Nonetheless, the underperformance of the US, relative to the remainder of the world, in 2025 must be a reminder that worldwide diversification nonetheless belongs within the toolkit for a prudent investor. That lesson cuts throughout the globe, and means that a lot as politicians and nations could need to delink from every others, buyers haven’t got that selection.
In case you have been a reader of my posts, I do have a little bit of an obsession with nation danger,, i.e., why the danger of investing and doing enterprise varies throughout nations, and what causes that danger to vary. My protection for that’s that I educate company finance and valuation, and to do both, I want solutions to those nation danger questions, and whilst you could not just like the quick cuts and approximations I exploit alongside the best way, I’ll take you alongside on my January 2026 journey:
The place to begin any dialogue of nation danger is with an examination of the elements that feed into that danger, and I’ll use a matrix that you’ll have seen in my prior posts on nation danger:
Whereas I do take a deeper and extra detailed take a look at these elements in a mid-year replace that I do yearly (hyperlinks to paper and my July 2025 weblog put up), the forces that trigger variations in nation danger span politics and economics, and embrace:Political Construction: From an investing and enterprise standpoint, the selection between democracy and autocracy is nuanced, with the previous creating extra steady uncertainty, as adjustments in authorities carry extra coverage change , and the latter creating extra coverage stability within the close to time period, albeit with a better chance for wrenching and doubtlessly catastrophic uncertainties over time.Battle and Violence: Investing and enterprise turn out to be extra hazardous, each bodily and economically, in the event you spend money on a extra violent setting, and battle, terrorism and entry to weapons can create variations throughout nations.Corruption: Corruption impacts companies instantly, working as implicit taxes on companies which can be uncovered to it, and not directly, by undercutting belief and the willingness to observe guidelines. Whereas variations in corruption throughout nations are sometimes attributed to cultural elements, a significant factor of corruption comes from buildings which can be designed to encourage and reward it.Authorized and Property rights: Traders and companies are depending on contracts and authorized agreements to function, however safety for property rights. Authorized programs which can be capricious in how they implement contractual and possession rights, or delay judgments to make them successfully ineffective, create dangers for companies and buyers.
There are various causes to anticipate variations throughout nations, on these dimensions, there’s a completely different perspective that may additionally assist. As a few of chances are you’ll know, I take a look at companies by the lens of a company life cycle, the place as companies age, their traits and challenges change as properly. That life cycle construction can be utilized to clarify variations throughout nations, the place the age is much less tied to how lengthy a rustic has been in being and extra to do with its economic system.
Younger economies have larger development potential, however that larger financial development comes with extra danger (extra risky economies) and require extra sturdy governance to ship on their promise. As economies age, they face a interval of decrease development, albeit with extra financial stability, and governance issues much less, successfully turn out to be mature (center aged) economies. There’s a ultimate part, the place a rustic’s economic system hits partitions, and development can stagnate and even turn out to be unfavorable, pushed partly by a lack of aggressive edge and partly by growing older populations. In every of those phases, nations typically overreach, with younger nations aspiring for the steadiness of center age, whereas attempting to develop at double-digit charges, and mature corporations, searching for to rediscover excessive development. With out treading an excessive amount of on political terrain, it might be value interested by the Trump actions in 2025 as pushed, not less than partially, by nostalgia for a unique time, when america was the dominant financial energy, with a mixture of stable financial development and stability that few economies, virtually unmatched in historical past.
With that philosophical discourse in nation danger out of the best way, let’s flip to the brass tacks of measuring nation danger, beginning with one of the crucial accessible and broadly obtainable one, that are rankings that businesses comparable to S&P, Moody’s and Fitch (amongst others) connect to sovereigns. The next is the heatmap of sovereign rankings (from Moody’s) in the beginning of 2026:
Whereas Moody’s charges greater than 140 nations, there stay just a few (referred to as frontier markets) that haven’t any rankings, however by way of the colour map, I’ve included these nations with the bottom rated, as a result of they share lots of the similar danger traits. There are three key options of those rankings which can be value emphasizing:
The sovereign rankings are centered virtually totally on default danger, and whereas the prospect {that a} nation will default is correlated with the core dangers (violence, political construction, authorized system and corruption) that I discussed up entrance, there are nations on this record the place they diverge. I consider that that is particularly the case within the Center East, the place there are nations, like Saudi Arabia, which have low or no default danger, however stay uncovered to massive political dangers.The sovereign rankings have their share of biases, for or towards areas, however their greater sin is that they’re sluggish to react. If you happen to take a look at the record, you will note nations like Argentina and Venezuela which have seen important adjustments in governance and politics within the final yr, however the place the rankings haven’t modified or barely modified. That may in all probability change in 2026, however this delayed response will imply that the sovereign rankings for some nations, not less than, is not going to be good reflections of nation danger, in the intervening time.There have been just a few rankings adjustments in 2025, largely on the margin, however the one which obtained essentially the most consideration was the rankings downgrade for the US that I highlighted on the time it occurred. Whereas markets, for essentially the most half, took that rankings downgrade in stride, it did create waves within the course of that I exploit to estimate riskfree charges and fairness danger premiums, by nation, as you will note later on this put up.
The rationale that a lot of how we cope with nation danger rests on sovereign rankings isn’t as a result of rankings businesses have particular insights, however as a result of sovereign rankings, in contrast to different (typically extra complete) measures of nation danger, like nation danger scores (from PRS or the Economist, to call two), could be transformed into default spreads that conveniently feed into monetary evaluation. In the beginning of 2026, listed below are my estimates of default spreads for every sovereign ranking:
As I famous earlier although, utilizing sovereign rankings to get default spreads comes with the restrictions that these rankings could not replicate present situations, when change is fast, and that’s the place the sovereign CDS market has created an alternate. For the 80 nations the place sovereign CDS exist, you may get a market-determined quantity for the default unfold, and listed below are the numbers in the beginning of 2026:
Notice that these spreads, whereas noisy and reflective of market temper, replicate the world we dwell in, and each Argentina and Venezuela, which was once uninsurable, have each seen enchancment on these market-driven numbers, albeit from unattainable to insure to actually pricey to insure.
As a ultimate step in my nation danger exploration, I repeat a course of that I’ve used to estimate fairness danger premiums, by nation, each six months for shut to 3 many years. That course of begins with estimating an fairness danger premium for the S&P 500, after which makes use of the nation default spreads (based mostly upon the rankings) to estimate fairness danger premiums for nations:
It’s simple that the rankings downgrade for the US has created some change on this course of. As an alternative of utilizing the S&P 500’s implied fairness danger premium as my estimate of the mature market premium, which was my pathway till Could 2025, I now take away the default unfold (0.23%) for the US from that premium to get to a mature market fairness danger premium (4.23%). To get to nation danger premiums for particular person nations, I scale up the ratings-based default spreads for the relative riskiness of equities, and add these nation danger premiums to the mature market premium:
Notice that I carry the frontier nations into the combo, through the use of nation danger scores for these nations to estimate nation and fairness danger premiums.
The Foreign money Impact
Whereas it stays true that nation danger and forex volatility/devaluation typically go collectively, considered one of my issues with mixing up the 2 up is that you find yourself double counting or miscounting danger. To grasp the divide between nation and forex danger, I begin with a take a look at authorities bond charges in numerous currencies, with the caveat that there solely about forty governments that concern bonds of their native currencies and that some or many of those authorities bonds are evenly traded, making their charges unreliable.
In lots of finance courses and textbooks, you might be typically taught (as I used to be) to make use of the federal government bond charge because the riskfree charge, on the facile assumption that governments shouldn’t default on these bonds, since they’ll print extra forex and canopy their debt obligations. The issue with that logic is that it’s at odds with the truth that governments can, and sometimes do, default on native forex bonds, selecting that possibility over devaluation. That additionally implies that the federal government bond charges can embrace a default danger element, and to get to a riskfree charge, that default danger must be faraway from the federal government bond charge. Within the image above, that’s what I do, utilizing the ratings-based default unfold). After this clean-up, you’ll be able to see that riskfree charges fluctuate broadly throughout currencies, from very low in some currencies (Swiss Franc, Japanese yen and the Thai Baht), barely larger for others (US greenback, Euros) and really excessive on just a few (Turkish Lira, Zambian kwacha).
In my third information replace, I estimated an intrinsic riskfree charge for the US greenback, by including inflation and actual GDP development. Extending that lesson to different currencies, the first motive for variations in these riskfree charges, throughout currencies, is anticipated inflation, with larger(decrease) rates of interest in larger (decrease) inflation currencies. Whereas inflation measures are imperfect and anticipated inflation estimates are sometimes flawed, I exploit the IMF’s estimates of inflation to construct a worldwide inflation warmth map:
The logic that I used to argue that it’s unlikely that you will note US treasury bond charges drop a lot beneath 4%, not less than so long as inflation runs sizzling (2.5-3%), not solely applies for different currencies, however yields a roadmap for estimating riskfree charges in these currencies (together with these with out a authorities bond within the native forex). As an instance, I’ll attempt to estimate an Egyptian pound riskfree charge in the beginning of 2026: