Tihana Škrinjarić
In my current paper, I current a brand new mannequin that helps assess dangers within the UK housing market. Not like conventional approaches that concentrate on common home value progress, the mannequin estimates a full vary of potential outcomes, permitting policymakers to establish potential threat of massive home value drops. The evaluation additionally highlights vital regional variations: areas with extra constrained housing provide are usually extra delicate to adjustments in rates of interest. Increasing provide may also help ease value pressures. These insights may also help enhance the monitoring of housing market vulnerabilities and assist monetary stability coverage.
What I do
Analysing vulnerabilities within the housing market is essential to trace monetary stability dangers stemming from this a part of the financial system. These developments are important for banks, households, and companies, as housing represents a long-term funding. Moreover, mortgages are one of many largest parts of the stability sheets and money flows of each UK lenders and households. Nonetheless, forecasting dynamics within the housing market is difficult attributable to uncertainty round future outcomes. To take action, I gather many potential variables and indicators that would assist me to foretell home value progress from the views of provide, demand, monetary, and non-fundamental elements. I look at round 50 totally different indicators, which makes it probably the most complete checklist in the home value modelling literature.
To gauge dangers of massive future home value drops, I apply a quantile regression strategy (Koenker (2005)), and derive a measure of house-price-at-risk (HPaR) each on the nationwide UK degree and regional degree. HPaR is a low percentile (I deal with the fifth) of the conditional distribution of future home value progress and subsequently captures the severity of potential home value declines beneath hostile situations. This strategy permits me to look at how totally different components of the distribution of home value progress – significantly the decrease tail versus the median – are related to adjustments in key variables, together with:
rates of interest;
earnings;
debt burden dynamics;
home value overvaluation, outlined as important improve in actual property costs past their intrinsic worth, usually pushed by investor expectations that costs will proceed to rise, even when elementary elements can not justify such valuations (Stiglitz (1990)). This overvaluation refers to accommodate costs rising above ranges that may be defined by financial fundamentals reminiscent of earnings, rates of interest, credit score situations and housing provide. It subsequently captures the a part of home value progress that seems disconnected from these elements and is commonly related to speculative expectations;
provide constraints; and
broader monetary situations.
On this method, the framework highlights that the connection between these elements and home value progress can differ throughout regular and hostile states, with out imposing a uniform impact throughout the distribution. The benefit of utilizing quantile regression is that it extra clearly captures durations of booms and busts in comparison with a normal linear regression mannequin.
Home value progress decomposition
Chart 1 presents the decomposition of the fifth percentile (I name it tail threat) nominal HPaR progress. The tail threat element successfully identifies downturns of early Eighties, Nineteen Nineties, and dynamics of world monetary disaster (GFC).
I observe that these declines have been defined by various factors. Within the early Eighties, the preliminary drop in nominal home costs was primarily linked to the oil value shock and a concurrent financial recession, adopted by sharp will increase in mortgage rates of interest. The downturn within the early Nineteen Nineties coincided with each a weakening financial system and a subsequent correction within the housing market. Whereas financial exercise had already begun to sluggish earlier than the housing bubble absolutely unwound, the decline in home costs possible amplified the recession by its results on family stability sheets, consumption and credit score situations.
That is mirrored by a pointy decline in home value overvaluation and compounded by a major drop in credit score exercise and transactions in previous quarters. In the course of the GFC, transaction volumes clarify a lot of the decline, adopted by heightened monetary stress and a contraction in credit score provide. In the newest downturn, the decline started with a slowdown in transactions, rising mortgage rates of interest, and a drop in home value overvaluation. Each the expected tail and median nominal home value progress have been trending downward since 2016.
Chart 1: Decomposition of nominal year-on-year (YoY) UK home value progress on the fifth percentile exhibits totally different contributions of house-price predictors throughout time
Observe: Const – fixed, Demand – contains YoY actual GDP progress, Monetary – contains YoY mortgage charge change, YoY change of value to earnings ratio, credit-to-GDP hole, CISS – composite indicator of systemic stress, YoY inventory market progress, and YoY inflation; Non fund – home value overvaluation, Different – contains YoY home market transaction progress, CCI – client confidence index, and EPU – financial coverage uncertainty; Provide – contains YoY housing funding progress, and YoY oil value progress.
Chart 1 additionally highlights a recurring sample during which durations of elevated home value overvaluation are adopted by subsequent corrections in tail house-price progress. That is in keeping with the broader literature on asset-price cycles, which finds that extended durations of speedy value appreciation and overvaluation are sometimes adopted by market corrections as expectations modify and costs converge again in the direction of ranges justified by fundamentals. Within the decomposition, this mechanism is mirrored within the non-fundamental element making a optimistic contribution throughout growth durations and a damaging contribution throughout subsequent downturns. Whereas home value overvaluation is just not the only driver of housing downturns, the outcomes recommend that the unwinding of earlier overvaluation amplified a number of of the noticed declines in UK home costs.
Ahead-looking measures of home value vulnerability
I calculate a number of forward-looking threat measures primarily based on the estimated distributions for the one-year forward mannequin: distance to tail (measured because the distinction between the median and tail threat forecasts), and the likelihood of damaging progress – introduced in Chart 2.
Distance to tail (left panel) measures the hole between the median and lower-tail forecasts. Bigger values point out a wider dispersion between central and hostile home value outcomes and are subsequently usually interpreted as an indication of elevated vulnerability.
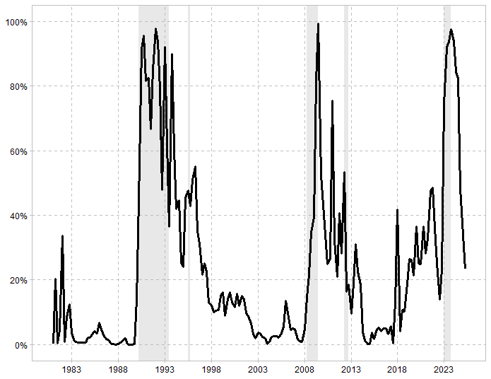
A notable spike in uncertainty is noticed through the Covid-19 shock, although it dissipates shortly, as anticipated. The mannequin can be profitable in predicting such durations when home costs would drop considerably (proper panel), as indicated by spikes of the forecasted likelihood sequence that preceded precise home value drops (gray shaded space).
Chart 2: Distance to tail and its decomposition (left), and likelihood of damaging home value progress (proper), one-year forward
Notes: Left panel exhibits the distinction between the median and tail progress (DTT = distance to tail). Proper panel exhibits estimated likelihood of home value progress dropping beneath 0%. Gray shaded space denote durations when noticed home value progress dropped beneath 0%. Estimates at a sure quarter of a 12 months are primarily based on data from the identical quarter within the earlier 12 months.
What does regional evaluation uncover?
Regional housing market vulnerabilities matter for monetary stability as a result of dangers can construct inconsistently throughout the nation and might not be absolutely captured by nationwide indicators. The regional evaluation exhibits that UK housing market vulnerabilities differ considerably throughout areas, highlighting the worth of estimating separate HPaR fashions reasonably than relying solely on nationwide outcomes.
A key discovering is that demand-related variables exhibit markedly totally different associations throughout areas. Revenue progress is most strongly related to future home value progress in London, the South East, South West and East Anglia, suggesting that these areas are extra delicate to demand situations than different components of the UK (Chart 3, blue bars).
Chart 3: Variations between estimation outcomes between areas
Notes: Bars denote the values of estimated parameters for chosen variables, and calmly shaded blue, inexperienced, and orange bars denote statistically insignificant values.
Estimates of the connection between mortgage charge adjustments and future home value progress range significantly throughout the nation. Provide-constrained areas, significantly southern and midland areas of the UK, show bigger and quicker coefficient of mortgage charge adjustments within the HPaR specification (Chart 3, orange bars). Because of this, larger mortgage charges are related to extra pronounced threat of massive home value drops in these areas.
On the provision facet, higher housing provide is usually related to decrease future home value pressures in most areas (Chart 3, inexperienced bars). Nonetheless, London, the South East and Scotland are exceptions. For the primary two, the outcomes align with the findings of Zahirovic-Herbert and Gibler (2014), who argue that in massive, built-up metropolitan areas, new provide can result in larger home costs. This is because of elevated land prices, stringent improvement constraints, and the potential want for brownfield remediation. Scotland has its personal housing rules and broader housing coverage framework, which differ from these in England and Wales (Gibb (2019)).
This means that regional monitoring can present priceless data for monetary stability surveillance and coverage evaluation.
Key takeaways
Whereas nationwide estimates present helpful alerts of housing market threat, regional outcomes reveal some heterogeneity throughout areas. The associations between home costs and elements reminiscent of GDP progress, credit score situations and mortgage charges range significantly throughout the UK, suggesting that each nationwide and regional views are helpful for monitoring vulnerabilities. Stronger financial exercise and housing provide are usually related to decrease draw back dangers, whereas larger mortgage charges and stronger credit score progress are related to higher dangers of enormous home value falls.
A number of limitations stay. Regional information availability is restricted, significantly for macrofinancial indicators, and the mannequin is designed to establish predictive relationships reasonably than causal results. Future analysis may incorporate richer regional information units, discover housing market spillovers in higher element, and examine regional convergence golf equipment to higher seize frequent housing market dynamics.
Tihana Škrinjarić works within the Financial institution’s Stress Testing and Resilience Division.
If you wish to get in contact, please e mail us at bankunderground@bankofengland.co.uk or go away a remark beneath.
Feedback will solely seem as soon as authorised by a moderator, and are solely revealed the place a full identify is equipped. Financial institution Underground is a weblog for Financial institution of England workers to share views that problem – or assist – prevailing coverage orthodoxies. The views expressed listed below are these of the authors, and usually are not essentially these of the Financial institution of England, or its coverage committees.
Share the publish “A brand new framework for monitoring dangers within the UK housing market”