With President Milei’s election in Argentina, dollarization is immediately on the desk. I am for it. Here is why.
Why not? A regular of worth
Begin with “why not?” Dollarization, not a nationwide forex, is definitely a wise default. The greenback is the US customary of worth. We measure size in ft, weight in kilos, and the worth of products in {dollars}. Why ought to completely different nations use completely different measures of worth? Would not it make sense to make use of a standard customary of worth? As soon as upon a time each nation, and infrequently each metropolis, had its personal weights and measures. That made commerce troublesome, so we finally converged on worldwide weights and measures. (Ft and kilos are literally a US anachronism since everybody else makes use of meters and kilograms. Clearly if we needed to begin over we would use SI items, as science and engineering already do.)
Furthermore, no one thinks it is a good suggestion to periodically shorten the meter in an effort to stimulate the economic system, say by making the sale of material extra worthwhile. As quickly as individuals determine they should purchase extra fabric to make the identical denims, the revenue goes away.
Precommitment
Precommitment is, I believe, probably the most highly effective argument for dollarization (as for euorization of, say, Greece): A rustic that dollarizes can not print cash to spend greater than it receives in taxes. A rustic that dollarizes should additionally borrow solely in {dollars}, and should endure pricey default somewhat than comparatively more cost effective inflation if it would not need to repay money owed.
Ex publish inflation and devaluation is all the time tempting, to pay deficits, to keep away from paying debt, to switch cash from savers to debtors, to benefit exporters, or to goose the economic system forward of elections. If a authorities can precommit itself to eschew inflation and devaluation, then it may possibly borrow much more cash on higher phrases, and its economic system will probably be much better off in the long term.
An unbiased central financial institution is usually advocated for precommitment worth. Properly, finding the central financial institution 5,000 miles away in a rustic that does not care about your economic system is as unbiased as you may get!
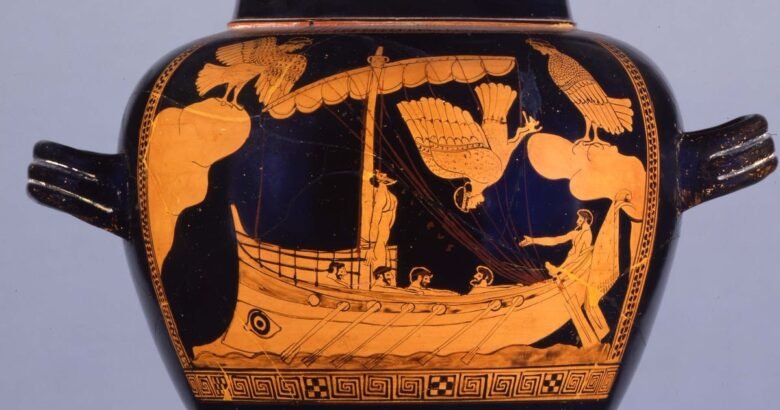
Precommitment is an previous concept. See image. It is onerous. A rustic should set issues up in order that it can not give in to temptation ex publish, and it’ll remorse and attempt to wriggle out of that dedication when the time comes. Quite a lot of the construction of our legal guidelines and authorities quantity to a set of precommitments. An unbiased central financial institution with a price-level mandate is a precommitment to not inflate. A structure and property rights are precommitments to not expropriate electoral minorities.
Particularly in Argentina’s case, precommitment is why full dollarization is healthier than an change charge peg or a forex board. A real change charge peg — one greenback for one peso, as a lot as you want — would appear to unravel the temptation-to-inflate downside. However the nation can all the time abrogate the peg, reinstitute forex controls, and inflate. An change charge peg is finally a fiscal promise; the nation will elevate sufficient taxes in order that it may possibly get the {dollars} essential to again its forex. When that appears too onerous, nations devalue the peg or abandon it altogether.
A forex board is harder. Underneath a forex board, each peso issued by the federal government is backed by a greenback. That appears to make sure enough reserves to deal with any conceivable run. However a strapped authorities eyes the nice Uncle-Scrooge swimming pool stuffed with {dollars} on the forex board, and is tempted to abrogate the board, seize the property and spend them. That is precisely how Argentina’s forex board ended. Dollarization is a burn the ships technique. There isn’t any return. Reserves are neither essential nor ample for an change charge peg. The peg is a fiscal promise and stands and falls with fiscal coverage.
A forex board, to the federal government
Full dollarization — the nation makes use of precise {dollars}, and abandons its forex — can’t be so swiftly undone. The nation must move legal guidelines to reinstitute the peso, declare all greenback contracts to be Peso contracts, ban using {dollars} and attempt to confiscate them. {Dollars} pervading the nation would make that onerous. Individuals who perceive their wealth is being confiscated and changed by monopoly cash would make it tougher — tougher than some technical change within the quantity of backing on the central financial institution for a similar peso notes and financial institution accounts underlying a devalued peg and even an abrogated forex board.
The design of dollarization ought to make it tougher to undo. The purpose is precommitment, to make it as pricey as potential for a following authorities to de-dollarize, in any case. It is onerous to confiscate bodily money, but when home Argentine banks have greenback accounts and greenback property, it’s comparatively straightforward to pronounce the accounts in pesos and seize the property. It will be higher if dollarization had been accompanied by full monetary, capital, and commerce liberalization, together with permitting international banks to function freely and Argentinian banks to develop into subsidiaries of international banks. Absence of a central financial institution and home deposit insurance coverage will make that much more fascinating. Then Argentinian financial institution “accounts” could possibly be claims to greenback property held offshore, that stay intact it doesn’t matter what a future Peronist authorities does.
Governments in fiscal stress that print up cash, like Argentina, additionally impose an array of economy-killing insurance policies to attempt to prop up the worth of their forex, so the cash printing generates extra income. They prohibit imports with tariffs, quotas, and crimson tape; they’ll prohibit exports to attempt to steer provide to residence markets at decrease costs; they prohibit forex conversion and accomplish that at manipulated charges; they prohibit capital markets, stopping individuals from investing overseas or borrowing overseas; they drive individuals to carry cash in oligopolized financial institution accounts at artificially low rates of interest. Dollarization can be a precommitment to keep away from or at the very least cut back all these dangerous insurance policies, as producing a requirement for a rustic’s forex would not do any good to the federal government finances when there is not a forex.
Zimbabwe dollarized in 2009, giving up on its forex after the best hyperinflation ever seen. The argument for Argentina is analogous. Ecuador dollarized efficiently in a lot much less attempting circumstances. It is not a brand new concept, and unilateral dollarization is feasible. In each circumstances there was a interval through which each currencies circulated. (Sadly, Zimbabwe ended dollarization in 2019, with a re-introduction of the home forex and redenomination of greenback deposits at a really unfavorable change charge. It’s potential to undo, and the safety of greenback financial institution accounts in face of such appropriation is a vital a part of the dollarization precommitment.)
The boundaries of precommitment
Dollarization isn’t any panacea. It would work whether it is accompanied by fiscal and microeconomic reform. Will probably be of restricted worth in any other case. I am going to declare a motto: All profitable inflation stabilizations have come from a mix of fiscal, financial and microeconomic reform.
Dollarization doesn’t magically clear up intractable finances deficits. Underneath dollarization, if the federal government can not repay debt or borrow, it should default. And Argentina has loads of expertise with sovereign default. Argentina already borrows overseas in {dollars}, as a result of no one overseas desires peso debt, and has repeatedly defaulted on greenback debt.
The thought of greenback debt is that express default is extra pricey than inflation, so the nation will work tougher to repay debt. Bond purchasers, conscious of the temptation to default, will put clauses in debt contracts that make default extra pricey nonetheless. So that you can borrow, it’s important to give the financial institution the title to the home. Sovereign debt issued underneath international legislation, with rights to seize property overseas works equally.
However sovereign default shouldn’t be infinitely pricey and nations like Argentina generally select default anyway. The place inflation might characterize merely hugging the mast and promising to not let go, default is a set of free handcuffs that you could wriggle out of painfully.
International locations are like firms. Debt denominated within the nation’s personal forex is like company fairness (inventory): If the federal government cannot or will not pay it again the value can fall, by way of inflation and forex devaluation. Debt denominated in international forex is like debt: If the federal government cannot or will not pay it again, it should default. (Most frequently, default is partial. You get again some of what’s promised, or you’re compelled to transform maturing debt into new debt at a decrease rate of interest.)
The usual concepts of company finance inform us who points debt and who points fairness. Small companies, new companies, companies that do not have simply beneficial property, companies the place it’s too straightforward for the managers to cover money, are compelled to borrow, to subject debt. You need to borrow to start out a restaurant. Companies subject fairness once they have good company governance, good accounting, and stockholders could be positive they’re getting their share.
These concepts apply to nations, and the selection between borrowing in their very own forex and borrowing in international forex. International locations with poor governance, poor accounting, uncontrolled fiscal insurance policies, poor establishments for compensation, must borrow in international forex if they will borrow in any respect, with intrusive circumstances making default much more costly. Issuing and borrowing in your personal forex, with the choice to inflate, is the privilege of nations with good establishments, and democracies the place voters get actually mad about inflation specifically.
After all, when issues get actually unhealthy, the nation cannot borrow in both home or international forex. Then it prints cash, forcing its residents to take it. That is the place Argentina is. In private finance, you begin with no credit score in any respect; then you may borrow; lastly you may subject fairness. On the size of more healthy economies, dollarizing is the subsequent step up for Argentina.
Dollarization and international forex debt have one other benefit. If a rustic inflates its means out of a fiscal mess, that advantages the federal government but in addition advantages all personal debtors on the expense of personal savers. Personal borrowing inherits the inflation premium of presidency borrowing, because the efficient authorities default induces a widespread personal default. Dollarization and sovereign default can permit the sovereign to default with out messing up personal contracts, and all costs and wages within the economic system. It’s potential for sovereigns to pay greater rates of interest than good firms, and the sovereign to be extra more likely to default than these firms. It would not all the time occur, as a result of sovereigns about to default normally seize all of the wealth they’ll discover on the way in which down, however the separation of sovereign default from inflationary chaos can be a bonus.
Greece is an efficient instance, and a bit Italy as nicely, each within the benefits and the cautionary story concerning the limitations of dollarization. Greece and Italy used to have their very own currencies. In addition they had borders, commerce controls, and capital controls. That they had common inflation and devaluation. Each day gave the impression to be one other “disaster” demanding one other “simply this as soon as” splurge. Because of this, they paid fairly excessive rates of interest to borrow, since savvy bondholders wished insurance coverage towards one other “simply this as soon as.”
They joined the EU and the eurozone. This step precommitted them to free commerce, comparatively free capital markets, and no nationwide forex. Sovereign default was potential, however considered very pricey. Having banks filled with sovereign debt made it extra pricey. Leaving the euro was potential, however much more pricey. Intentionally having no plan to take action made it extra pricey nonetheless. The ropes tying arms to the mast had been fairly robust.
The end result: borrowing prices plummeted. Governments, individuals and companies had been capable of borrow at unprecedented low charges. They usually did so, with aplomb. The borrowing might have financed private and non-private funding to benefit from the brand new enterprise alternatives the EU allowed. Sadly it didn’t. Greece quickly skilled the upper ex-post prices of default that the precommitment imposed. Dollarizaton — euroization — is a precommitment, not a panacea. Recommitments impose prices on your self ex publish. These prices are actual.
A profitable dollarization for Argentina needs to be a part of a joint financial, fiscal, and microeconomic reform. (Did I say that already? 🙂 ) If public funds aren’t sorted out, a default will come finally. And public funds do not want a pointy bout of “austerity” to please the IMF. They want a long time of small main surpluses, tax revenues barely greater than spending, to credibly pay down any debt. To get a long time of income, one of the best reply is development. Tax income equals tax charge instances earnings. Extra earnings is loads simpler than greater tax charge, which at the very least partially lowers earnings. Greece and Italy didn’t accomplish the microeconomic reform half.
Thankfully, for Argentina, microeconomic reform is low-hanging fruit, particularly for a Libertarian president.
Transition
Properly, a lot for the Promised Land, they could have requested of Moses, how will we get there? And let’s not spend 40 years wandering the Sinai on the way in which.
Transition is not essentially onerous. On 1 January 1999, Italy switched from Lira to Euro. Each value modified in a single day, each checking account redenominated, each contract reinterpreted, all immediately and seamlessly. Individuals turned in Lira banknotes for Euro banknotes. The most important grievance is that shops might need rounded up transformed costs. If solely Argentina might have such issues.
Why is Argentina not the identical?
Properly, for lots of causes. Earlier than attending to the euro, Italy had adopted the EU open market. Trade charges had been efficiently pegged on the conversion charge, and no humorous enterprise about a number of charges. The ECB (actually the Italian central financial institution) might merely print up euros handy out in change for lira. The property of the Italian central financial institution and different nationwide central banks had been additionally redenominated in euro, so printing up euros to take in nationwide currencies was not inflationary — property nonetheless equal liabilities. Banks with lira deposits that convert to Euro even have lira property that convert to euro. And there was no sovereign debt disaster, financial institution disaster, or huge inflation occurring. Italian authorities debt was buying and selling freely on an open market. Italy would spend and obtain taxes in euros, so if the debt was value its present value in lira as the current worth of surpluses, it was value precisely the identical value, on the conversion charge, in euro.
None of that is true in Argentina. The central downside, after all, is that the federal government is broke. The federal government doesn’t have {dollars} to change for Pesos. Usually, this might not be an issue. Reserves do not matter, the fiscal capability to get reserves issues. The federal government might merely borrow {dollars} internationally, give the {dollars} out in change for pesos, and slowly repay the ensuing debt. If Argentina redenominated interest-bearing peso debt to {dollars} at a market change charge, that will haven’t any impact on the worth of the debt.
Clearly, borrowing further {dollars} would doubtless be troublesome for Argentina proper now. To the extent that its remaining debt is a declare to future inflationary seigniorage revenues, its debt can be value much less as soon as transformed to {dollars}, even at a free market charge, as a result of with out seigniorage or fiscal reforms, finances deficits will enhance.
And that results in the first argument towards dollarization I hear nowadays. Sure it may be the promised land, but it surely’s too onerous to get there.
I do not hear loudly sufficient, although, what’s the various? Another muddle of forex boards, central financial institution guidelines, guarantees to the IMF and so forth? How do you immediately create the type of steady establishments that Argentina has lacked for a century to justify a good forex?
One would possibly say it is a downside of value, not of amount. Choose the suitable change charge, and conversion is feasible. However that isn’t even clearly true. If the state is really broke, if pesos are solely value something due to the authorized restrictions forcing individuals to carry them, then pesos and peso debt are genuinely nugatory. The one path to dollarization can be basically a whole collapse of the forex and debt. They’re value nothing. We begin over. You should use {dollars}, however you will must export one thing to the US — both items or capital, i.e. inventory and bonds in personal firms — to get them. (Properly, to get any extra of them. Plenty of {dollars} line Argentine mattresses already.) That’s sufficient financial chaos to essentially put individuals off.
In actuality, I believe the worry shouldn’t be a very nugatory forex, however {that a} transfer to fast dollarization would make peso and peso claims value little or no, and other people would insurgent towards seeing their cash holdings and financial institution accounts much more immediately nugatory than they’re now. Perhaps, perhaps not. Simply who’s left in Argentina relying on a strong worth of pesos?
However the state shouldn’t be value nothing. It could be value little in mark to market, or present greenback borrowing capability. However a reformed, rising Argentina, with tax, spending, and microeconomic reform, could possibly be an important place for funding, and for tax income above prices. As soon as worldwide lenders are satisfied these reform efforts are locked in, and Argentina will develop to something like its superb potential, they’re going to be stumbling over themselves to lend.
So a greater dollarization plan redeems pesos on the new better worth of the post-reform Argentine state. The query is a little bit of rooster and egg: Dollarization needs to be a part of the reform, however solely reform permits dollarization with an honest worth of peso change. So there’s a real query of sequencing of reforms.
This query jogs my memory of the completely fruitless dialogue when the Soviet Union broke up. American economists amused themselves with intelligent optimum sequencing of liberalization schemes. But when competent benevolent dictators (sorry, “policy-makers”) had been working the present, the Soviet Union would not have failed within the first place.
The tip of hyperinflation in Germany. Worth degree 1919-1924. Word left-axis scale. Supply: Sargent (1982) “The ends of 4 huge inflations.”
A greater historic analogy is, I believe, the ends of hyperinflation after WWI, so superbly described by Tom Sargent in 1982. The inflations had been stopped by a sudden, simultaneous, fiscal, financial, and (to some extent) microeconomic reform. The fiscal downside was solved by renegotiating reparations underneath the Versailles treaty, together with extreme cuts in home spending, for instance firing a number of authorities and (nationalized) railroad employees. There have been financial reforms, together with an unbiased central financial institution forbidden to purchase authorities debt. There have been some microeconomic reforms as nicely. Stopping inflation took no financial stringency or excessive rates of interest: Rates of interest fell, and the governments printed extra money, as actual cash demand elevated. There was no Phillips curve of excessive unemployment. Employment and the economies boomed.
So I am for almost-simultaneous and quick reforms.
1) Enable using {dollars} in every single place. {Dollars} and pesos can coexist. Sure, it will put downward strain on the worth of the peso, however that may be essential to take care of curiosity within the different reforms, which is able to elevate the worth of the peso.
2) On the spot unilateral free commerce and capital opening. Argentina should export items and capital to get {dollars}. Get out of the way in which. Liberating imports will decrease their costs and make the economic system extra environment friendly. Capital will solely are available, which it ought to do shortly, if it is aware of it may possibly get out once more. Float the peso.
3) Lengthy listing of development – oriented microeconomic reforms. That is why you elected a Libertarian president.
4) Slash spending. Reform taxes. Low marginal charges, broad base. Subsidies specifically distort costs to switch earnings. Get rid of.
5) As soon as reforms are in place, and Argentina has some borrowing capability, redenominate debt to {dollars}, and borrow further {dollars} to change pesos for {dollars}. All present peso contracts together with financial institution accounts change on the date.
Principally, you need individuals to carry peso payments and peso debt within the interim as claims on the post-reform authorities. Peso holders have an incentive to push for reforms that may elevate the eventual change worth of the peso.
6) Discover an interim lender. The central downside is who will lend to Argentina in mid stream in an effort to retire pesos. That is like debtor in possession financing however for a bankrupt nation.
This could possibly be a job for the IMF. The IMF might lend Argentina {dollars} for the aim of retiring pesos. One could not ask for significantly better “conditionality” than a strong Libertarian pro-growth program. Having the IMF alongside for the trip may also assist to commit Argentina to this system. (The IMF can drive conditionality higher than personal lenders.) When issues have settled down, Argentina ought to be capable of borrow {dollars} privately to pay again the IMF. The IMF would possibly cost an honest rate of interest to encourage that.
How a lot borrowing is required? Lower than you assume. Curiosity-paying debt can merely be redenominated in {dollars} when you choose a charge. That may be onerous to repay, however that is an issue for later. So Argentina actually solely must borrow sufficient {dollars} to retire money pesos. I am unable to discover numbers, however hyper inflationary nations sometimes haven’t got a lot actual worth of money excellent. The US has 8% of GDP in forex excellent. If Argentina has half that, then it must borrow solely 4% of GDP in {dollars} to purchase again all its forex. That is not loads. If the peso actually collapses, borrowing a little bit bit extra (towards nice future development of the reform program) to present everybody $100, the type of contemporary begin that Germany did after WWII and after unification, is value contemplating.
Many of the fear about Argentina’s borrowing potential envisions continued main deficits with gradual fiscal adjustment. Make the fiscal adjustment tomorrow.
“You by no means desire a severe disaster to go to waste,” mentioned Rahm Emanuel correctly. “Sequencing” reforms signifies that the whole lot promised tomorrow is up for fixed renegotiation. Particularly when elements of the reform rely on different elements, I am for doing all of it as quick as potential, after which including refinements later if want be. Roosevelt had his well-known 100 days, not a 8 12 months sequenced program.
The Argentine reform program goes to harm lots of people, or at the very least acknowledge losses that had lengthy been papered over within the hope they might go away. Politically, one desires to make the case “We’re all on this, we’re all hurting. You surrender your particular deal, preferential change charge, particular subsidy or no matter, however so will everybody else. Grasp with me to ensure they do not get theirs, and in a 12 months we’ll all be higher off.” If reforms are in an extended sequence, which suggests lengthy renegotiation, it is a lot tougher to get purchase in from people who find themselves harm earlier on that those who come later can even do their half.
The usual solutions
One customary critique of dollarization is financial coverage and “optimum forex areas.” By having a nationwide forex, the nation’s sensible central bankers can artfully inflate and devalue the forex now and again to adapt to unfavorable shocks, with out the inconvenience and potential dislocation of everybody within the nation decreasing costs and wages.
Suppose, say, the nation produces beef, and exports it in an effort to import automobiles. If world demand for beef declines, the greenback value of beef declines. The nation goes to must import fewer automobiles. In a dollarized nation, or with a pegged change charge, the interior value of beef and wages go down. With its personal nation and a floating charge, the worth of the forex might go down, leaving beef and wages the identical contained in the nation, however the value of imported automobiles goes up. If decreasing costs and wages causes extra recession and dislocation than elevating import costs, then the suave devaluation is the higher concept. (To consider this query extra fastidiously you want traded and non-traded items; beef, automobiles, and haircuts. The relative value of beef, automobiles, and haircuts together with demand for haircuts can be completely different underneath the 2 regimes).
Equally, suppose there’s a “lack of demand” recession and deflation. (90 years later, economists are nonetheless struggling to say precisely the place that comes from.) With its personal central financial institution and forex, the nation can artfully inflate simply sufficient to offset the recession. A rustic that dollarizes additionally has to import not-always-optimal US inflation. Switzerland did loads higher than the US and EU as soon as once more within the covid period.
This line of considering solutions the query, “OK, if Argentina ($847 bn GDP, beef exports) ought to have its personal forex in an effort to artfully offset shocks, why should not Colorado ($484 bn GDP, beef exports)?” Colorado is extra depending on commerce with the remainder of the US than is Argentina. However, the story goes, individuals can extra simply transfer throughout states. A standard federal authorities shoves “fiscal stimulus” to states in hassle. Most of all, “lack of demand” recessions appear to be nationwide, partly due to the excessive integration of states, so recessions are fought by nationwide coverage and do not want state-specific financial stimulus.
That is the usual “optimum forex space” line of considering, which recommends a standard forex in an built-in free commerce zone similar to US, small Latin American nations that commerce loads with the US, and Europe. Normal considering particularly likes a standard forex in a fiscal union. Some commenters felt Greece ought to hold or revert to the Drachma as a result of the EU did not have sufficient widespread countercyclical fiscal coverage. It likes unbiased currencies elsewhere.
I hope you are laughing out loud by now. A sensible central financial institution, coupled with a thrifty nationwide authorities, that artfully inflates and devalues simply sufficient to technocratically exploit value stickiness and monetary frictions, offsetting nationwide “shocks” with minimal disruption, is a laughable description of Argentina’s fiscal and financial insurance policies. Periodic inflation, hyperinflation and default, along with a wildly overregulated economic system with far an excessive amount of capital and commerce controls is extra prefer it.
The lure of technocratic stabilization coverage within the face of Argentina’s fiscal and financial chaos is like fantasizing whether or not you need the tan or black leather-based in your new Porsche whilst you’re on the bus to Carmax to see in case you can afford a 10-year previous Toyota.
One more reason individuals argue that even small nations ought to have their very own currencies is to maintain the seigniorage. Precise money pays no curiosity. Thus, a authorities that points money earns the curiosity unfold between authorities bonds and curiosity. Equivalently, if demand for money is proportional to GDP, then as GDP grows, say 2% per 12 months, then the federal government can let money develop 2% per 12 months as nicely, i.e. it may possibly print up that a lot money and spend it.
However this type of seigniorage is small for contemporary economies that do not have inflation. With out inflation, a nicely run economic system would possibly pay 2% for its debt, so save 2% by issuing forex. 2% curiosity instances money which is 10% of GDP is 0.2% of GDP. On the size of Argentinian (or US) debt and deficits, that is sofa change.
When inflation is greater, rates of interest are greater, and seigniorage or the “inflation tax” is greater. Argentina resides off that now. However the level is to not inflate eternally and to forswear greater inflation taxes.
Conserving this small seigniorage is one cause for nations to maintain their forex and peg to the greenback or run a forex board. The forex board holds interest-bearing greenback property, and the federal government will get the curiosity. Good. However as I decide above, the additional precommitment worth of complete dollarization is well worth the small misplaced seigniorage. Going through Argentina’s disaster, plus its catastrophic century of misplaced development, misplaced seigniorage is a value that I decide far under the profit.
Different nations dollarize, however agree with the US Fed to rebate them some cash for the seigniorage. Certainly, if Argentina dollarizes and holds 10% of its GDP in non-interest-bearing US {dollars}, that is a pleasant little current to the US. A dollarization settlement with Argentina to present them again the seignorage can be the least we are able to do. However I do not assume Argentina ought to maintain off ready for Jay Powell to reply the telephone. The Fed has different fires to place out. If Argentina unilaterally dollarizes, they’ll work this type of factor out later.
Dollarization would clearly be loads simpler whether it is labored out along with the US authorities and US banks. Getting money despatched to Argentina, getting banks to have straightforward fee programs in {dollars} and hyperlinks to US banks would make all of it simpler. If Argentina eliminates its central financial institution it nonetheless wants a fee system to settle claims in {dollars}. Accounts at, say, Chase might operate as a central financial institution. However it might all be simpler if the US cooperates.
Updates:
Some commenters level out that Argentina could also be importing US financial coverage simply because the US imports Argentine fiscal coverage. That will result in importing a giant inflation. They counsel a Latin American Financial Union, just like the euro, or utilizing a 3rd nation’s forex. The Swiss franc is fairly good. Perhaps the Swiss can set the world customary of worth.
Each are good theoretical concepts however loads tougher to attain within the quick run. Dollarization will probably be onerous sufficient. Argentines have a number of {dollars} already, most commerce is invoiced in {dollars} so getting {dollars} by way of commerce is comparatively straightforward, the Swiss haven’t constructed out a banking infrastructure able to being a worldwide forex. The EMU lives on high of the EU, and has its personal fiscal/financial issues. Constructing a brand new forex earlier than fixing Argentina’s issues appears like an extended street. The query requested was dollarization, so I caught to that for now.
I imagined right here unilateral dollarization. However I did not emphasize sufficient: The US ought to encourage dollarization! China has figured this out and desperately desires anybody to make use of its forex. Why ought to we not need extra individuals to make use of our forex? Not only for the seigniorage income, however for the benefit of commerce and worldwide linkages it promotes. The Treasury and Fed ought to have a “how one can dollarize your economic system” bundle able to go for anybody who desires it. Full integration shouldn’t be trivial, together with entry to forex, getting financial institution entry to the Fed’s clearing programs, instituting cyber and cash laundering protocols, and so forth.
Necessary replace:
Daniel Raisbeck and Gabriela Calderon de Burgos at CATO have a beautiful essay on Argentinian dollarization, additionally debunking an earlier Economist article that proclaimed it unattainable. They embody details and comparability with different dollarization experiences, not simply concept as I did. (Because of the correspondent who pointed me to the essay.)
Some quotes:
On the finish of 2022, Argentines held over $246 billion in international financial institution accounts, secure deposit containers, and principally undeclared money, in keeping with Argentina’s Nationwide Institute of Statistics and Census. This quantities to over 50 p.c of Argentina’s GDP in present {dollars} for 2021 ($487 billion). Therefore, the greenback shortage pertains solely to the Argentine state….
The final two dollarization processes in Latin American nations show that “buying” your entire financial base with U.S. {dollars} from one second to the subsequent shouldn’t be solely impractical, however it is usually pointless.
In each Ecuador and El Salvador, which dollarized in 2000 and 2001 respectively, dollarization concerned parallel processes. In each nations, probably the most simple course of was the dollarization of all present deposits, which could be transformed into {dollars} on the decided change charge immediately.
in each Ecuador and El Salvador, dollarization not solely didn’t result in financial institution runs; it led to a speedy and sharp enhance in deposits, even amid financial and political turmoil in Ecuador’s case….
There’s a normal characteristic of ending hyperinflation: Individuals maintain extra money. On this case, individuals maintain extra financial institution accounts as soon as they know these accounts are secure.
Quick abstract of the remaining, all these greenback deposits (out of mattresses into the banking system) allowed the central financial institution to retire its native forex liabilities.
Emilio Ocampo, the Argentine economist whom Milei has put accountable for plans for Argentina’s dollarization ought to he win the presidency, summarizes Ecuador’s expertise thus:
Individuals exchanged their {dollars} via the banks and a big a part of these {dollars} had been deposited in the identical banks. The central financial institution had nearly no must disburse reserves. This was not by design however was a spontaneous end result.
In El Salvador additionally,
Greenback deposits additionally elevated spontaneously in El Salvador, a rustic that dollarized in 2001. By the top of 2022, the nation’s deposits amounted to 49.6 p.c of GDP—in Panama, one other dollarized peer, deposits stood at 117 p.c of GDP.
El Salvador’s banking system was dollarized instantly, however the conversion of the circulating forex was voluntary, with residents allowed to determine if and when to change their colones for {dollars}. Ocampo notes that, in each Ecuador and El Salvador, solely 30 p.c of the circulating forex had been exchanged for {dollars} 4 months after dollarization was introduced in order that each currencies circulated concurrently. Within the latter nation, it took over two years for 90 p.c of the financial base to be greenback‐based mostly.
Cachanosky explains that, in an El Salvador‐kind, voluntary dollarization situation, the circulating nationwide forex could be dollarized as it’s deposited or used to pay taxes, through which case the sums are transformed to {dollars} as soon as they enter a state‐owned checking account. Therefore, “there isn’t any want for the central financial institution to purchase the circulating forex” at a second’s discover.
Dollarization begins with each currencies and a peg. So long as individuals belief that dollarization will occur on the peg, the conversion can take some time. You don’t want {dollars} to take in each peso on day 1. Dollarization is, above, a dedication that the peg will final for years, not a essential dedication that the peg will final a day.
I speculated about personal borrowing at decrease charges than the sovereign, as soon as default somewhat than inflation is the one means out for the sovereign. This occurred:
… as Manuel Hinds, a former finance minister in El Salvador, has defined, solvent Salvadorans within the personal sector can borrow at charges of round 7 p.c on their mortgages whereas worldwide sovereign bond markets will solely lend to the Salvadoran authorities at far greater charges. As Hinds writes, underneath dollarization, “the federal government can not switch its monetary prices to the personal sector by printing home cash and devaluing it.”
A pleasant backside line: Ask individuals in Ecuador, El Salvador, and Panama what they assume:
That is one more lesson of dollarization’s precise expertise in Latin American nations. It is usually a cause why the overwhelming majority of the inhabitants within the dollarized nations has no want for a return to a nationwide forex. The financial experiences of day by day life have taught them that dollarization’s palpable advantages far outweigh its theoretical drawbacks.
Much more necessary replace:
From Nicolás Cachonosky Learn how to Dollarize Argentina The central downside is non-money liabilities of the central financial institution. An in depth plan. Many different weblog posts on the hyperlink. See his remark under.
Tyler Cowen on dollarization in Bloomberg. Nice quote:
The query shouldn’t be how one can undertake a brand new forex, it’s how one can undertake a brand new forex and retain an inexpensive worth for the previous one.
Dollarization is straightforward. Hyperinflate the Peso to zero a la Zimbabwe. Repeat quote.
Emilio Ocampo on dollarization as a dedication gadget.
One of many foremost causes to dollarize is to get rid of excessive, persistent, and unstable inflation. Nevertheless, to be efficient, dollarization should generate ample credibility, which in flip relies upon critically on whether or not its anticipated likelihood of reversal is low….
The proof means that, within the long-run, the strongest insurance coverage towards reversal is the assist of the citizens, however within the short-run, institutional design [dollarization] can play a vital position.
Fifty years in the past, in testimony to U.S. Congress, Milton Friedman argued that “the entire cause why it is a bonus for a growing nation to tie to a serious nation is that, traditionally talking, the interior insurance policies of growing nations have been very unhealthy. U.S. coverage has been unhealthy, however their insurance policies have been far worse. … (1973, p.127).”
On this respect, not a lot has modified in Argentina since.
Craig Richardson explains how dollarization failed in Zimbabwe, a beautiful cautionary story. Deficits didn’t cease, the federal government issued “bonds” and compelled banks to purchase them, financial institution accounts turned de linked from forex. Gresham’s legislation prevailed, the federal government “bonds” circulating at half face worth drove out money {dollars}. With persistent authorities and commerce deficits there was a “greenback scarcity.”