Inventory markets have at all times rewarded winners with giant capitalizations, and with every new threshold, the questions start anew of whether or not animal spirits or fundamentals are driving the numbers. A number of weeks in the past, Nvidia appeared unstoppable as its market capitalization crested $5 trillion, and whereas markets have turned skeptical since, the core questions haven’t gone away, and the solutions come from two extremes. At one finish are the “realists”, who view themselves as rational, above the fray and completely data-driven, who argue that there isn’t any enterprise mannequin that may assist a worth this excessive, and that Nvidia is overvalued. On the different finish are the “AI true believers”, who consider that if the market the corporate goes after is sufficiently big, they usually see AI as such a market, the higher bounds on worth are launched, the sky is the restrict. As somebody who entered the Nvidia sweepstakes early (in 2018) and has held it via a lot of its magical run, whereas expressing reservations about its pricing working forward of its worth, particularly within the final three years, I’ll attempt to thread the needle (unsuccessfully, I’m certain) on this publish. Actually, somewhat than attempt to persuade you that the corporate is beneath or overvalued, which is absolutely your judgment to make, I’ll provide a easy mannequin to reverse engineer from any given market capitalization, the revenues and profitability thresholds it’s important to meet, and help you come to your personal conclusions.
A Historical past of Market Cap Thresholds
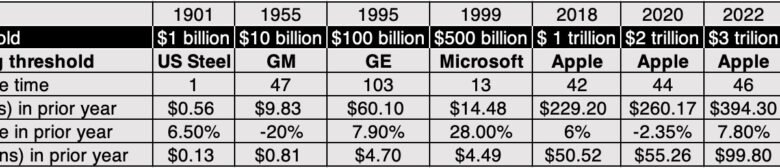
In 1901, US Metal was created when Andrew Carnegie and J.P. Morgan consolidated a lot of the US metal enterprise, with an eye fixed to monopolizing the metal enterprise, and the corporate turned the primary world agency with a market capitalization of a billion {dollars}, a small quantity in at present’s phrases, however a quantity that was 3 times bigger than the Federal funds in that yr. The 20 th century was a very good one for the US economic system and US shares, and the thresholds for highest market cap rose alongside the way in which:
Word the lengthy stretch between Microsoft hitting the half-a-trillion greenback market cap in 1999, because the dot com increase peaked, and Apple doubling that threshold in 2018. Word additionally the quickening of the tempo, as Apple hit the $2 trillion and $3 trillion market capitalization thresholds within the subsequent 4 years, and Nvidia continued the streak hitting $4 trillion in 2024 and $5 trillion in 2025. The desk does present a place to begin to discussing a number of themes about how the US economic system and US equities have developed during the last century. You’ll be able to see the shift away from the smokestack economic system to expertise , within the corporations hitting the thresholds, with US Metal and GM firmly within the outdated economic system mode, Microsoft, Apple, and Nvidia representing the brand new economic system, and GE, with its giant monetary service arm, working as a bridge. Having been in markets for all the thresholds breached since 1981, the talk about whether or not the corporate breaking via has risen an excessive amount of in too quick a time interval has been a recurring one. Substance: To get a measure of working substance, I appeared on the revenues and internet earnings within the yr main into the yr during which every firm broke via the edge. As you possibly can see, US Metal had revenues of $0.56 billion and internet earnings of $0.13 billion in 1901, the yr during which its market cap exceeded $1 billion. GM, on the time its market cap breached $10 billion, had revenues of $9.83 billion, on which it generated internet earnings of $0.81 billion; if PE ratios are your pricing metric of selection, that will have translated right into a PE ratio of 12.35. Between 2018 and 2022, as Apple’s market cap tripled from $1 trillion to $3 trillion, its annual revenues elevated by 72%, and its internet income virtually doubled. Lastly, coming to Nvidia, the surge in market cap to $4 trillion in 2024 and $5 trillion in 2025 has come on revenues and internet earnings which can be a couple of quarter of the dimensions of Apple’s revenues and internet earnings.Life cycle: Each firm that climbed to the highest of the market cap tables and hit a market cap threshold traditionally has had single-digit income development within the yr main up, with two exceptions: Microsoft in 1999, which was coming off a 28% income development charge in 1998, and Nvidia in each 2024 and 2025 coming off even greater development charges. Utilizing this income development charge along with the ages of the businesses concerned, I feel it’s honest to conclude that there was a shift throughout time, with the mature corporations (older, decrease development) that have been on the high of the listing for a lot of the 20th century to a lot youthful corporations with development potential rising to the highest on this one.Funding returns: Wanting on the returns within the years after these corporations hit their market cap thresholds, the outcomes are blended. Whereas shopping for Apple in 2018, 2020, or 2022 would have yielded profitable returns, no less than over the following yr or two, shopping for Microsoft in 1999 wouldn’t. In a few of these circumstances, extending the time horizon would have made a distinction, for the optimistic with Microsoft and for the detrimental with GE.From a rational perspective, you could possibly argue that these thresholds (billion, half a billion, trillion, and many others.) are arbitrary and that there’s nothing gained by specializing in them, however in a publish that I wrote in September 2018 on Apple and Microsoft changing into trillion-dollar corporations, I argued that crossing these arbitrary thresholds can draw consideration to the numbers, with the consequences slicing each methods, drawing in traders who remorse lacking out on the rising market cap within the intervals earlier than (a optimistic) and inflicting present traders to take a more in-depth have a look at what they’re getting in return (maybe a detrimental).
Market Caps: Pathways to Intrinsic Worth Break Even
Debates about whether or not an organization is price what it’s buying and selling for, whether or not it’s a billion, ten billion, 100 billion, or a trillion, devolve into shouting matches of “he mentioned, she mentioned”, with either side staking out divergent views on worth and name-calling the opposite. Having been on the receiving finish of a few of that abuse, I made a decision to take a distinct pathway to inspecting this query. Fairly than ponder whether Nvidia is price 5 trillion or Eli Lilly is price a trillion, I framed the query when it comes to how a lot Nvidia or Eli Lilly must generate in revenues to justify their market capitalizations. The explanation for my concentrate on revenues is easy since it’s comparatively unaffected by accounting video games and will be in comparison with the overall market measurement to realize perspective.
The device that I plan to make use of to reach at this breakeven income is intrinsic valuation, and I selected to not use the acronym “DCF” intentionally. A reduced money stream valuation (DCF) appears like an abstraction, with fashions driving low cost charges and monetary modeling driving money flows. To me, a DCF is only a device that lets you assess how a lot you’d pay for a enterprise or the fairness within the enterprise, given its capability to generate money flows for its house owners. Since it’s simple to get misplaced within the labyrinth of estimates over time, I’ll simplify my DCF by doing two issues. First, since our dialogue is about market capitalization, i.e., the market’s estimate of the worth of fairness, I’ll stick with an fairness model of the mannequin, the place I concentrate on the money flows that fairness traders can get from the enterprise and low cost these money flows again at a charge of return that they might demand for investing in that fairness. In its most normal kind, that is what an fairness valuation yields:
To simplify the evaluation additional, I structured this mannequin to worth fairness in a mature firm, i.e., one rising at or beneath the nominal development charge of the economic system within the very long run and once more for simplicity, assumed that it may do that perpetually. The worth of fairness on this mature, long-lasting agency will be written as follows:
To place this mannequin into use, let’s take the $5 trillion greenback market capitalization that Nvidia commanded just a few weeks in the past and assign the next normal inputs:
Value of fairness: Each month, I estimate the implied price of fairness for the S&P 500, and that quantity is model-agnostic and pushed by what traders are keen to pay for shares, given their fears and hopes. Firstly of November 2025, that quantity was about 8%, with greater required returns (9-12%) for riskier shares and decrease anticipated returns (6-7%) for safer shares.Inflation charge: Whereas inflation has come down from its 2022 highs, it has stayed stubbornly above 2%, which the Fed claims as its goal, and it appears extra reasonable to imagine that it’ll keep at 2.5%, which is according to the riskfree charge being about 4%.Steady development charge (nominal development charge within the economic system): This can be a quantity that’s in flux, as economists fear about recessions and financial development, however since this can be a long-term quantity that comes with anticipated inflation, it appears affordable to imagine an anticipated nominal development of 4% for the economic system (about 1.5% actual development). The online revenue margin for Nvidia in the newest twelve months has been 53.01%, an exceptionally excessive quantity, and the return on fairness it has earned, on common during the last 5 years, is about 64.44%. I do know that these numbers will come beneath stress over time, as competitors for AI chips picks up, and Nvidia’s largest prospects (and chip maker) push for his or her share of the spoils, however even in the event you assume that Nvidia can preserve these margins, the income that Nvidia must ship to justify its worth is $483.38 billion.
Since Nvidia remains to be rising and you might want to attend, as fairness traders, to get your money flows, this breakeven quantity will get bigger, the longer it’s important to wait and the decrease the money yield that fairness traders obtain in the course of the development interval. Actually, with Nvidia, in the event you assume that it’ll take 5 years for them to develop to regular state, and that fairness traders will obtain a money yield (money stream as a % of market cap) of two% a yr, the estimated breakeven income will increase to $677.97 billion. The desk beneath maps out the consequences of ready on breakeven revenues for a spread of money yield:
If, as appears affordable, you assume that internet margins and return on fairness will lower over time, the revenues you would want to interrupt even will increase:
Actually, in case you are a low-margin firm, with internet margins of 5% (as is the case with even the very best-run low cost retailers) and a extra modest return on fairness of 10%, you will want revenues of $8 trillion or extra to have the ability to get to a market capitalization of $5 trillion.
This framework can be utilized to compute breakeven revenues at different corporations, and within the desk beneath, we accomplish that for the twelve largest market cap corporations on the earth, at their market capitalizations on November 20, 2025:
Word that, for simplicity, I’ve used a 2% money yield and 4% development charge in perpetuity for all of those corporations, and that the breakeven revenues replicate present internet margins and returns on fairness at every of those corporations, however with that mentioned, there may be nonetheless worth in variations. To permit for this comparability, I forecast out breakeven revenues 5 years from now, and estimated the expansion that every firm would want over the 5 years to justify its present market cap. Not surprisingly, Aramco can get to its breakeven revenues in yr 5 with virtually no development (0.59% development charge) however Tesla must ship income development of 86.4% to interrupt even. Broadcom, one other firm that has benefited from the market’s zeal for AI, has the following highest cliff to climb when it comes to income development. Actually, for all the Magazine Seven shares, development has to fifteen% or greater to breakeven, a problem given their scale and measurement. In greenback worth phrases, three corporations might want to get to breakeven revenues that exceed one trillion by yr 5 to breakeven, Apple, Amazon and Tesla, however the first two are already greater than a 3rd of the way in which to their breakeven targets, however Tesla has a protracted, lengthy strategy to go.
From Breakeven Revenues to Funding Motion
Whereas some are extra snug changing typical intrinsic valuation, the place you estimate worth and evaluate it to cost, with a breakeven evaluation, the reality is that the 2 approaches are born out of the identical intent.
The Economics of Breakeven Revenues
The mannequin that I used to compute breakeven revenues is a vastly simplified model of a full fairness valuation mannequin, however even in its simplified kind, you possibly can see the drivers of breakeven revenues.
Market Capitalization: Since we work again from market capitalization to estimate breakeven revenues, the bigger the market capitalization, holding all else fixed, the larger the breakeven revenues will likely be. Utilizing simply Nvidia for example, the corporate has seen its market capitalization rise from lower than $400 billion in 2021, to $1 trillion in 2023, $2 trillion and $3 trillion thresholds in 2024 and crossed the $4 trillion and $ 5 trillion market cap ranges in 2025. Because the market cap has risen, the breakeven revenues have elevated from $200 billion on the $1 trillion mark to $600 billion on the present market cap.Working Profitability: There are two profitability metrics within the drivers, with internet margins figuring out how a lot of the revenues an organization can convert to income and the return on fairness driving the reinvestment wanted to maintain development. Larger profitability will enable an organization to ship a better market capitalization, at any given degree of revenues. One cause manufacturing corporations like Tesla will want greater breakeven revenues than software program corporations is that the unit economics will not be as favorable.Rates of interest and fairness danger premiums: The extent of rates of interest and fairness danger premiums decide the price of fairness for all firm, with greater values for the latter pushing up the prices of fairness for riskier corporations greater, relative to safer corporations.Working and leverage danger: The riskiness in a enterprise will push its price of fairness greater, and a better debt load (relative to market cap) can have the identical impact. The next price of fairness will increase the breakeven revenues wanted to ship the identical market capitalization.
In sum, whereas the breakeven income that you’ll want to justify a given market cap at all times will increase because the market cap will increase, its degree and charge of rise will likely be ruled by enterprise economics.
The 3Ps: Attainable, Believable, and Possible
Changing a standard intrinsic valuation with a breakeven income evaluation nonetheless leaves open the ultimate funding query of whether or not that breakeven income is a quantity that you’re snug with, as an investor. To handle this query, I’ll draw on a construction that I exploit for intrinsic valuation, the place I put my evaluation via what I name the 3P check.
It’s potential that when you compute the breakeven revenues for a agency and measure it up in opposition to actuality that it’s inconceivable, i.e., a fairy story. The obvious case is when the breakeven revenues that you simply compute to your agency exceeds the overall marketplace for the services or products that it gives. If there’s a lesson that tech corporations discovered within the final decade, it was in making the overall addressable market (TAM) for his or her market into virtually an artwork kind, including zeros and changing billion greenback markets into trillion greenback TAMs. In the event you go the “it’s potential” check, you enter the plausibility zone, and nuance and enterprise economics enter the image extra absolutely. Thus, assuming {that a} luxurious retailer with sky-high margins and small revenues, by staying with a distinct segment market, can enhance its revenues ten-fold, whereas conserving margins intact, is implausible, as is a internet margin of 40% in steady development for an organization with gross margins which can be barely above that quantity. Lastly, assuming that revenues can multiply over time, with out reinvesting in acquisitions or tasks to ship these revenues are additionally pushing the boundaries of what’s believable. As soon as breakeven revenues go the potential and believable exams, you have to be on extra acquainted floor as you have a look at your complete story line for the corporate, and assess whether or not the mix of development, profitability and reinvestment that you’re assuming along with your story has an affordable likelihood of being delivered.
To use these exams, think about Nvidia and Tesla. Nvidia wants about $590 billion in revenues by 2030 to interrupt even at its present market capitalization of $4.3 trillion, requiring a development charge in revenues of about 26% for the following 5 years. Whereas that may be a attain, it’s each potential and believable, with continued development within the AI chip market and a dominant market share for Nvidia offering the pathway. It’s on the possible check that you simply run into headwinds, since competitors is heating up, and that may put stress on each development and margins. The issue for Tesla is that if the web margin stays low (at 5.31%), the revenues wanted to breakeven exceed $2.2 trillion, and even with robotics and automatic driving thrown into the enterprise combine, you might be pushing the boundaries of chance. A Tesla optimist, although, would argue that these new companies, once they arrive, will convey a lot greater internet margins, which, in flip, will push down breakeven revenues and convey it into believable territory.
The Aggregated 3P Check – Massive Market Delusion
We are likely to ask the 3P query on the firm degree with the businesses that we select to put money into (and like), however as we assemble what appear like believable and possible tales for these corporations, and put money into them accordingly, there are different traders are asking the identical questions concerning the corporations that they put money into, a lot of which compete in the identical enterprise as yours. That will sound unexceptional to you, however when the market that these corporations are competing in could be very giant and nonetheless in formation, you possibly can find yourself with what I described virtually a decade in the past as the massive market delusion. In a paper on the subject, I used the dot.com increase, the hashish inventory surge and internet marketing as case research to elucidate how this conduct is a function of massive markets
The AI storyline clearly suits the massive market delusion. There may be discuss of a “large” marketplace for AI services and products, with little to point out as tangible proof of that market’s existence proper now, and that potential has drawn large investments in AI structure from tech corporations. Alongside the way in which traders have additionally fallen beneath the spell of the massive market, and have pushed up the market capitalizations of just about each firm within the house. Utilizing the language of breakeven revenues, traders in every of those corporations is attributing giant breakeven revenues to their chosen corporations, however the delusion comes from the fact that in the event you aggregated these breakeven revenues throughout corporations, the market shouldn’t be sufficiently big to maintain all of them. In brief, every firm handed the potential and believable check, however within the combination, you might be chasing an inconceivable goal.
Whereas the massive market delusion is at play in each facet of AI, one section the place it’s most seen proper now’s within the Massive Language Fashions (LLM) house, the place excessive profile gamers like ChatGPT, Gemini, Grok and Claude are vying for customers, and their creators are being rewarded with nosebleed pricing. OpenAI, whereas nonetheless unlisted, has used the early lead that ChatGPT gave it within the LLM race to draw investments from a bunch of massive tech corporations (together with Nvidia and Amazon) and enterprise capitalists, with the newest traders pricing it at $500 billion, an astonishing quantity, on condition that the corporate reported revenues of solely $13 billion in the newest twelve months. Anthropic, the creator of Claude, has seen its pricing bounce in the newest funding spherical (from Microsoft and Nvidia in November 2025) to $350 billion, fifty instances its revenues of $7 billion within the final twelve months. Elon Musk’s house owners stake in xAI, Grok’s originator, was estimated to be price $230 billion in November 2025, once more an immense a number of of its revenues of $3.2 billion (in the event you embody mixed revenues with X). Increasing the listing to the massive tech corporations, it’s plain that a few of Alphabet’s large rise in market capitalization in 2025 is due to its possession of Gemini, and that Meta (with Llama) and Amazon (with Nova) have additionally seen bumps in market capitalization. Lastly, whereas Deepseek is now not making headlines, it is usually within the house, competing for enterprise. Within the combination, LLM possession is being priced at $1.5 trillion or extra, and the collective revenues, even generously outlined, are lower than $100 billion. It’s solely believable {that a} huge market exists for LLMs, and that one and even two of the gamers on this house will likely be winners, however within the combination, the market is overreaching.
The Administration Impact
The mechanics of the breakeven income course of might make it appear to be managers are bystanders within the course of and that investing will be on autopilot, however they aren’t. Actually, when market capitalizations rise, and breakeven revenues run effectively forward of present revenues, I might argue that administration issues greater than ever. Going again to the breakeven revenues that we computed for the twelve largest market cap corporations on the earth, I might make the case that administration issues a lot much less (if in any respect) in Aramco and Berkshire Hathway, the place breakeven revenues are near present revenues, and the investments wanted to ship these revenues have already been made, that on the corporations that also have steep climbs forward of them to get to breakeven revenues.
On this context, I’ll reemphasize a priority that I raised on the top of Meta’s metaverse investing fiasco, which is that traders at many tech corporations, together with most on the massive cap listing, have given up their company governance rights, usually voluntarily (via the acceptance of shares with completely different voting rights), to founders and high administration in these corporations. When conventional company governance mechanisms break down, and high managers have unchecked energy, there may be an elevated danger of overreach. That concern is multiplied within the LLM house, the place Sam Altman (at OpenAI) and Elon Musk (at xAI) are extra emperors than CEOs.
The Investing Bottomline
I began this publish with mentions of market cap thresholds being breached, because the market pricing pushes up into the trillions for a number of the largest inventory market winners. However what are the implications for traders?
Extremely priced ≠ Overpriced: If you’re an investor who considers any extremely priced firm to be overvalued, I hope that this publish leads you to rethink. By reframing a pricing when it comes to breakeven revenues, profitability and reinvestment, it lets you think about whether or not a inventory, even when priced at $4 trillion, should be a very good purchase. The 3P check: When you compute the working metrics you’ll want to breakeven on an funding in a extremely priced firm, passing these metrics via the 3P check (Is it potential? Is it believable? Is it possible?) lets you look at every firm on its deserves and potential, somewhat than use a broad brush or a rule of thumb (based mostly on PE ratios or income multiples).Room to disagree: I’ve by no means understood why, even in the event you consider strongly {that a} inventory is over or beneath priced, that you’ll want to evangelize that perception or contest individuals with alternate views. I feel that the pathway that you’d want (when it comes to income development and profitability) to justify Nvidia’s and OpenAI’s present pricing is unbelievable, however that’s simply my view, and it’s solely potential that you’ve an alternate perspective, resulting in the conclusion that they’re undervalued.Actuality checks: It doesn’t matter what your view, optimistic or pessimistic, it’s important to be open to altering your thoughts, as you might be confronted with knowledge. Thus, you probably have priced an organization to ship 20% development in revenues over the following 5 years (to interrupt even) and precise revenues development is available in at 10%, it’s important to be keen to revisit your story, admit that you simply have been fallacious, and adapt.
In the event you got here into this publish, anticipating a definitive reply on whether or not Nvidia is overpriced, you might be in all probability disillusioned, however I hope that you simply use the breakeven spreadsheet to good impact to make up your personal thoughts.
YouTube
Spreadsheets