Repo markets play an important function within the U.S. monetary system. On this three-part collection, we study who participates in these markets, what trade-offs affect how totally different repo segments are structured, and why repos matter for financial coverage. At this time’s submit introduces repo transactions, specializing in the key private-sector members and why they have interaction in these markets.
What’s a Repo?
A repurchase settlement or repo is a monetary transaction during which one occasion sells a safety in alternate for money, with the dedication to repurchase the identical (or a intently associated) safety for a prespecified worth on a future date. (From the angle of the occasion shopping for the safety and later reselling it, this transaction is named a reverse repo.) Repos are an integral part of the U.S. monetary system, performing each as a supply of funding and short-term funding for a lot of monetary establishments, in addition to a market for acquiring particular securities. Latest estimates assess the day by day quantity of excellent agreements within the U.S. at round $13.5 trillion or 40 % of U.S. GDP (see OFR 2026).
The time between the preliminary sale and the repurchase, together with the value distinction, determines the rate of interest, often called the repo charge. Repo charges fluctuate relying on quite a lot of components, most notably the kind of collateral accepted (the securities bought), maturity (the size of time between the preliminary sale and repurchase), counterparty, the scale of the haircut (the distinction between the worth of the securities bought and money delivered), and clearing (the method between the execution and ultimate settlement of a transaction). Round 70 % of repos are collateralized by U.S. Treasury securities and most have an in a single day maturity. When it comes to clearing, round 60 % of repos are cleared by a central counterparty (35 %) or by a 3rd occasion (25 %), whereas 40 % are instantly cleared between the customer and vendor (OFR 2025).
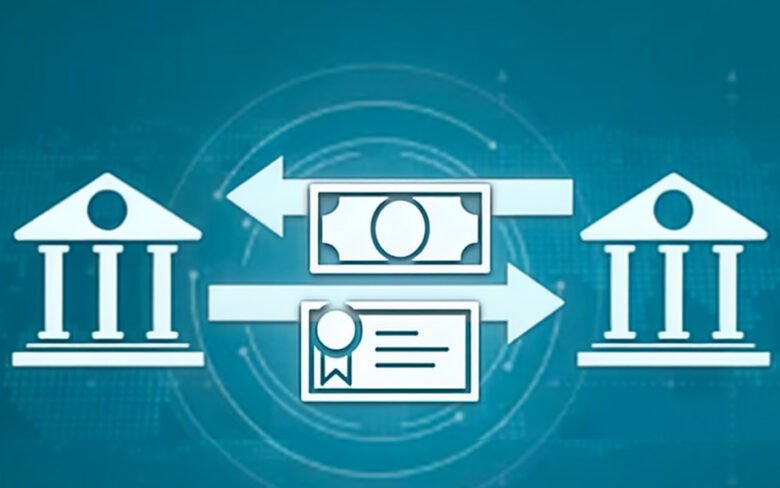
As an illustration, the diagram beneath exhibits a stylized illustration of a repo market. Many several types of transactions happen in repo markets. For instance, a vendor—performing as an middleman—should purchase securities from levered buyers like hedge funds (a reverse repo from the vendor’s perspective), and likewise enter right into a repo with different sellers or with money lenders comparable to cash market funds (MMFs) to promote the securities, thus finally channeling funds from money lenders to money debtors. In tomorrow’s submit, we delve deeper into the microstructure of varied segments of repo markets.
A Stylized Illustration of a Repo Market
Supply: Authors’ illustration.
Repos might be traced again to the early twentieth century. Repo market measurement and contracting conventions modified markedly within the Nineteen Eighties following the failure of a number of sellers, amid a rising degree and volatility of rates of interest and rising provide of Treasury debt (see Garbade 2006). An essential conference that has contributed to the liquidity and progress of repo markets is that repos involving Treasury and federal company securities are exempt from the automated keep underneath the U.S. Chapter Code that, because the title suggests, comes into impact when an organization information for chapter and stays collectors from taking sure actions on account of their claims in opposition to the corporate. Because of this if the money borrower defaults in the course of the lifetime of the repo, the money lender can typically terminate its repo contracts with the defaulting counterparty, promote the securities promptly, and keep away from the delay and uncertainty of the chapter course of.
What Are Repos Used for?
In a repo, the occasion promoting the safety is concerned with borrowing money. The counterparty, nevertheless, might enter the repo transaction for one among two causes: to speculate money and earn a return, or to acquire a selected safety. The primary motive makes a repo economically just like different short-term cash market devices comparable to federal funds, Eurodollars, or industrial paper. Not like in these markets, the transaction is collateralized: from the angle of the money lender, the securities scale back the danger of the commerce.
A “basic collateral repo” (or GC repo) is an efficient instance of a repo transaction during which the money lender is just not within the particular securities it receives. In GC repo, the money lender agrees to obtain any safety that meets a specified standards (for instance, Treasury securities with lower than ten years to maturity) moderately than a selected safety. This makes GC repo a funding market each for money debtors looking for to finance a basket of securities and for money lenders seeking to make investments money at a aggressive charge. The diagram beneath exhibits an illustration of a repo used as a funding instrument. On this instance, a MMF is seeking to make investments $98 million in money in a single day and lends to a repo vendor in opposition to a basket of Treasury securities together with a haircut of two %. The next day, the MMF receives $98,009,800 (at a return of three.6 % in annual phrases) and returns the securities.
An Instance of a Repo Transaction
Supply: Authors’ calculations.
Contributors might also have interaction in repo to amass a selected safety. Within the particular problem market, the securities used to settle the transaction are recognized on the outset of the commerce. When a specific safety is in excessive demand relative to obtainable provide, it has shortage worth and is named a “particular,” and sometimes trades at a decrease charge relative to the prevailing GC charge: the money lender, looking for to acquire a selected, scarce asset is keen to forgo some return (Duffie 1996). From this attitude, repos are like a safety lending transaction in opposition to money collateral moderately than a collateralized mortgage. There are two essential variations: first, repo primarily makes use of fixed-income devices as collateral and, second, repo sometimes doesn’t grant the lender the best of early recall of the securities.
Repos additionally play a key function in financial coverage implementation. In immediately’s submit we give attention to personal repos, returning to their use in central banks’ toolkits within the third submit of this collection.
Who Participates in Repo Markets?
Relative to the federal funds and Eurodollar and chosen deposits markets, the panorama of personal repo members is extra advanced for 2 important causes. First, there’s a broader and extra numerous set of final debtors and lenders. Second, sellers are instrumental intermediaries in repo markets. Within the the rest of this submit, we make clear the primary class, describing the important thing function of sellers in tomorrow’s submit.
The Debtors
The highest money debtors in personal repo markets are hedge funds. Hedge funds depend on repo markets for leverage to spice up their returns. An instance of a hedge fund technique that makes use of repo is the so-called “Treasury cash-futures foundation commerce.” On this technique, a hedge fund purchases a Treasury safety and sells a Treasury futures contract, which permits it to revenue from the value differential. To amplify the return on the idea commerce, hedge funds finance the acquisition of the Treasury securities with money borrowed in a repo that makes use of these securities as collateral. Because the chart beneath exhibits, hedge fund borrowing in repo markets tripled over 2013-23, from $400 billion to $1.5 trillion; after which it doubled once more within the following two years, reaching $3 trillion in late 2025.
Hedge Funds Are the Primary Money Debtors in Personal Repo Markets
Sources: OFR; FFIEC 002; FFIEC 031/041/051; Federal Reserve Financial institution of St. Louis, FRED database.
Notes: The chart exhibits personal repo money borrowing quantity by varied participant sorts. FBOs are U.S. branches and companies of international banks, HFs are hedge funds, USDIs are U.S. depository establishments, and REITs are actual property funding trusts.
The subsequent three largest debtors in repo markets immediately are U.S. branches and companies of international banks (FBOs), U.S. depository establishments (USDIs), and actual property funding trusts (REITs). Collectively, their excellent borrowing in repo has ranged between $800 billion and $1.3 trillion since 2013.
The Lenders
The primary money lenders in repo are MMFs. As the subsequent chart exhibits, between January 2013 and January 2021, MMF lending elevated by 90 %, from underneath $600 billion to $1 trillion. Within the following 5 years, MMF lending virtually tripled, reaching $3 trillion in January 2026. Repo markets supply MMFs a short-term funding that meets their regulatory necessities on maturity and asset composition whereas offering flexibility to assist handle investor redemptions.
The second largest lenders in repo are hedge funds. Though hedge funds are internet money debtors in repo, additionally they lend to handle money and liquidity and for collateral transformation. In late 2025, hedge funds lent round $1.3 trillion, a gradual improve from $350 billion in early 2013. The subsequent three largest lenders—government-sponsored enterprises (GSEs), U.S. branches and companies of international banks, and U.S. depository establishments—are key gamers within the federal funds, Eurodollar, and chosen deposits markets, and collectively lent $0.6-$1.5 trillion in repo over the 2013-25 interval.
MMFs Are the Primary Money Lenders in Repo Markets
Sources: OFR; FFIEC 002; FFIEC 031/041/051; Federal Reserve Financial institution of St. Louis, FRED database.
Notes: The chart exhibits personal repo money lending quantity by varied participant sorts. FBOs are U.S. branches and companies of international banks, HFs are hedge funds, USDIs are U.S. depository establishments, GSEs are government-sponsored enterprises, and MMFs are cash market funds.
In Sum
Repo markets are the venue the place monetary establishments lend and borrow cash in a collateralized method, often quick time period. Whereas debtors on this market receive money, lenders might search short-term investments or a selected safety of curiosity. As a market within the trillions of {dollars}, repo markets host all kinds of members. Within the subsequent posts on this collection, we are going to study the microstructure of varied segments of this market, and the market’s significance for financial coverage implementation.
Gara Afonso is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Jun-Davinci Choi is a analysis analyst within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Gonzalo Cisternas is a monetary analysis advisor within the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
Will Riordan is a capital markets buying and selling advisor within the Federal Reserve Financial institution of New York’s Markets Group.
Learn how to cite this submit:
Gara Afonso, Jun-Davinci Choi, Gonzalo Cisternas, and Will Riordan, “Who’s Borrowing and Lending in Repo Markets?,” Federal Reserve Financial institution of New York Liberty Road Economics, September 28, 2026, https://doi.org/10.59576/lse.20260928
BibTeX: View | Obtain
@article{GaraAfonso,Jun-DavinciChoi,GonzaloCisternas,andWillRiordan2026,
writer={Gara Afonso, Jun-Davinci Choi, Gonzalo Cisternas, and Will Riordan},
title={Who’s Borrowing and Lending in Repo Markets?},
journal={Liberty Road Economics},
observe={Liberty Road Economics Weblog},
quantity={September 28},
12 months={2026},
url={https://doi.org/10.59576/lse.20260928}
}
Disclaimer
The views expressed on this submit are these of the writer(s) and don’t essentially replicate the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the duty of the writer(s).