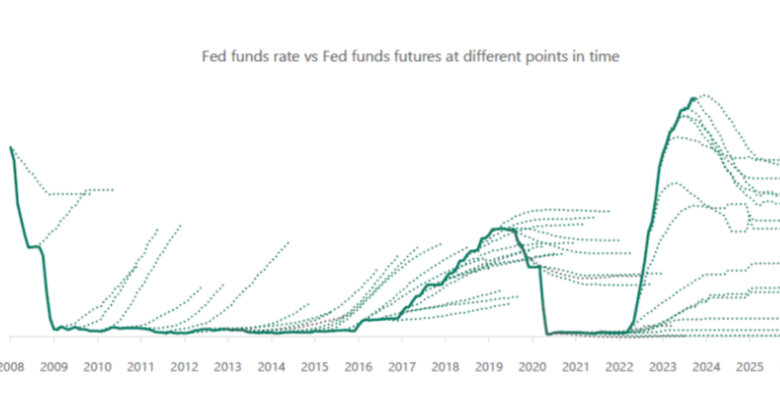
A beautiful plot from the at all times fascinating Torsten Slok. The graph reveals the precise federal funds price, along with the trail of “anticipated” funds price implicit in fed funds futures market costs. (Roughly talking the futures contract is a guess on the place the Fed funds price will likely be at numerous dates sooner or later. If you wish to bloviate about what the Fed will do, it is easy to place your cash the place your mouth is!)
Plenty of graphs appear to be this, together with the Fed’s “dot plot” projections of the place rates of interest will go, inflation forecasts, and long run rate of interest forecasts based mostly on the yield curve (yields on 10 yr bonds suggest a forecast of 1 yr bonds over the ten yr interval.) Simply change the labels.
In phrases, all through the 2010 zero sure period, markets “anticipated” rates of interest to raise off quickly, yr after yr. It was kind of like spring in Chicago — this week, 35 levels and raining. Subsequent week will likely be sunny and 70! Rinse and repeat. As soon as charges began rising in 2016, markets really thought the rise could be slower than it was, however then didn’t see the top of the rise. In fact they didn’t see the sudden drop in 2020, as a result of they did not see covid.
I discover it fascinating that for the primary full yr of inflation, 2021-20222, markets didn’t worth in any rate of interest rise in any respect. The Taylor rule (elevate rates of interest promptly when inflation rises) wasn’t that forgotten on the Fed! The one time when it made considerable sense to forecast the Fed would elevate charges, markets didn’t mirror that forecast.
When the Fed lastly did begin to elevate charges, amid raging inflation, the market much more curiously thought the speed rises would cease shortly. This being a pasted graph, I am unable to simply add inflation to it, however with the federal funds price considerably beneath inflation till June 2022, it is fascinating the markets thought the Fed would cease. The story of “transitory” inflation that might go away by itself and not using a repeat of the early Eighties — with out rates of interest considerably beneath inflation — was robust.
The market forecast appears to me nonetheless remarkably dovish. GDP simply grew like gangbusters final quarter, and the Fed believes within the Phillips curve (robust development causes inflation). We’re operating a historic finances deficit for an economic system at full steam. The Taylor rule (rates of interest react to inflation and output) remains to be a reasonably good description of what the Fed does, ultimately. So, if you happen to have been to commerce on the historic sample, you’d guess on charges falling rather more shortly than forecast. Hmm.
That is an previous phenomenon. The “expectations” in market forecasts do not appear proper. Do not bounce to quick to “irrational,” finance at all times has a approach out. We name it the “danger premium.” There’s cash to be made right here, however not with out danger. When you at all times guess that the funds price will likely be beneath the futures price, you will generate income more often than not, however you’ll lose cash every now and then. First, in lots of such bets the occasional losses are bigger than the small common good points. That’s essential, as a result of the sample of fixed misses in the identical path suggests irrational forecasts, however that is not true. When you play roulette and guess on something however 00, you win more often than not, however lose large every now and then and are available out even total, Extra plausibly, if you lose you lose at instances when it’s significantly inconvenient to lose cash.
Economists typically use the federal funds future to ascertain the “anticipated” federal funds price, after which any motion together with no motion in any respect counts as an “sudden” shock. By that measure the early 2010s have been one collection of “sudden” adverse financial coverage shocks, month after month. The graph makes it clear that is a studying of historical past that wants some nuance in its interpretation.