CoreWeave, a cloud computing firm working 51 information facilities, had a brutal day on the inventory and credit score markets yesterday, and should point out troubles coming for the broader AI business.
The difficulty began when yields on their company debt spiked dramatically.
Enterprise capitalist Chamath Palihapitiya tweeted the next to his 2.4M followers:
It didn’t assist when Elon Musk replied, “Yikes.”
Accompanied by an essay titled “Deep Dive: Is the AI buildout creating a personal credit score bubble?”
The AI buildout is more and more funded by debt, and personal credit score is taking part in a a lot larger function than it did even a 12 months in the past.
Within the second quarter of 2026, Apollo and Blackstone led a $35 billion car to purchase chips and lease them to Anthropic. UBS known as it the most important personal credit score deal on file. For comparability, direct lenders made about $23 billion of loans to private-equity-backed U.S. corporations that quarter. One AI financing was bigger than all the normal PE-backed direct lending PitchBook counted throughout the identical interval.
…
The construction of some AI financings provides one other layer to the image. CoreWeave borrowed for 5 years towards buyer contracts averaging about three, whereas Meta’s Hyperion bonds run to 2049 towards leases renewed each 4 years.
The market can also be already distinguishing amongst these offers. Apollo purchased debt financing chips leased to xAI at 99 cents in December 2025, and after SpaceX purchased xAI, it traded as excessive as 106. Venture Jupiter, an $18 billion AI data-center financing, later traded at 89 to 91 cents as traders reassessed the venture’s credit score.
So quite than ask whether or not AI itself is a bubble, our workforce at Social Capital regarded beneath the floor at a distinct query. Is personal credit score, which is funding a rising portion of the AI buildout, a bubble?
readers might want to take a look at the complete report to search out out Palihapitiya’s conclusion, however what I can let you know is that the impression on CoreWeave’s inventory worth was quick and dramatic:
Yahoo! Finance added that CoreWeave’s debt has tripled in a 12 months:
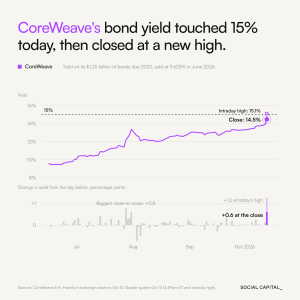
Twitter market analyst Hedgie posted the next graph:
Hedgie commented:
CoreWeave inventory fell about 13% Wednesday after its bonds due in 2032 traded at a file 14.5% yield. CoreWeave bought these bonds in June at 9.625%, so in 4 months the price of lending to it with out collateral jumped about 5 factors. Enterprise capitalist Chamath Palihapitiya posted the yield chart as a warning a couple of personal credit score bubble round AI.
I’ve been saying that the AI bubble lives within the debt greater than the demand, and CoreWeave is an instance. It raised greater than $35 billion this 12 months, carries about $52 billion in debt and leases, and paid $640 million in internet curiosity final quarter, roughly 1 / 4 of its income. The $104 billion backlog sounds nice, however a backlog doesn’t cowl curiosity till the info facilities get constructed and the shoppers pay.
Palihapitiya’s numbers present personal lenders cost AI debtors virtually the identical unfold as everybody else, 6.2 factors versus 6.1. I feel the bond market simply repriced that danger for them. My guess is CoreWeave’s subsequent elevate prices extra, comes backed by chips, or dilutes shareholders, and Nebius and the opposite AI cloud corporations face the identical questions. Should you personal a personal credit score fund, learn the way a lot AI and software program debt it holds, as a result of these loans don’t get repriced day by day the way in which CoreWeave’s bonds do.
A Bit Extra About CoreWeave
This Wired profile from 2024 tells CoreWeave’s story the way in which they prefer it informed.
After beginning out as a bunch of bros who pooled their fantasy soccer cash to purchase GPUs to do some cryptomining as a joke however then took it severely when costs soared in 2016, they needed to pivot when crypto costs crashed:
When crypto costs cratered heading into 2019, Venturo and workforce pivoted. They raised cash to purchase cut-price GPUs from struggling crypto miners, rebranded as CoreWeave, and supplied up their tens of 1000’s GPUs as a specialist cloud service for corporations in want of the highly effective chips, like visible results studios and AI startups. GPUs are important to machine studying initiatives like coaching algorithms to course of pictures or textual content. CoreWeave was unknown in these spheres, however received over purchasers by dropping all the things to handle assist queries. “We’d resolve issues in quarter-hour,” a supervisor from that period says. “The dedication to clients was phenomenal.”
The whole lot modified after OpenAI debuted ChatGPT late in 2022. A rush of curiosity and funding in all issues generative AI induced a GPU scarcity—particularly of Nvidia’s prized chips. With its couple of information facilities filled with GPUs and a long-standing relationship with Nvidia, CoreWeave rapidly turned very important to the accelerating AI hype prepare. The corporate picked up purchasers together with Microsoft, OpenAI’s essential sponsor, and image-generation startup Stability AI, in keeping with former CoreWeave workers. Venturo’s greatest remorse shouldn’t be ordering extra Nvidia chips again when he may. “If I had limitless quantities, I may have all of it bought in two weeks,” he says.
Issues nonetheless labored out. As demand for CoreWeave’s GPUs surged via 2023, the corporate piled its new income into shopping for extra of the chips and constructing out new information facilities. An organization that started as a beer-money aspect venture now doesn’t contact crypto, and is all in on cloud computing. Over the previous 12 months the startup has picked up a $2.3 billion mortgage—utilizing GPUs as collateral—and practically $2.2 billion in funding funding, together with $1.1 billion introduced this week, from traders together with Nvidia. With its newest infusion of money, the startup’s valuation jumped to $19 billion.
By the top of this 12 months, CoreWeave expects to have 28 information middle campuses unfold throughout a dozen or extra US states, Europe, and probably Asia—total greater than 9 instances its footprint initially of 2023.
Word they’ve since greater than doubled the variety of information facilities they function whereas tripling their debt.
As of June, these lovable bros had bought $2.3 billion in inventory since their IPO, per Bloomberg.
However let’s get again to their debt.
Ed Zitron Would Like a Phrase
In his October sixth piece, “Credit score Crunch“, Zitron writes:
CoreWeave, which has Goatse-level spreads of 672bps to 882bps, with the efficient yield on its shortest-dated debt (4 years) sitting at 11.53% and its longest-dated (a mere six years) sitting at 13.49%.
There are, in fact, methods round borrowing in your credit score profile. For instance, when CoreWeave opened an $8.5 billion delayed draw time period mortgage facility in March 2026, it was capable of get it rated as investment-grade and at SOFR (the share on in a single day borrowing from the Fed for banks) plus 2.25%, all as a result of the counterparty was Meta, and thus the underlying funds can be thought-about “protected.”
This may increasingly appear to be the cheat code to get round all these horrifying charges, besides CoreWeave, per analysts at UBS, wants to boost $102 billion in debt via 2030, which implies it must hold elevating by itself two toes.
Effectively, there’s an issue there.
Then he cites the next from The Data saying cracks are starting to type” within the AI information middle debt increase:
Bond markets are getting robust for lower-rated debtors. One instance: CleanSpark, which is creating a knowledge middle for Meta Platforms, needed to provide traders massive concessions to land financing earlier this month.
That deal is among the many clearest indicators but that financing the info middle increase is getting costly throughout the board, and traders are getting choosy about which new initiatives they’ll again. The financial institution mortgage market too is exhibiting indicators of pressure, with some lenders like Société Générale, Sumitomo Mitsui Banking Corp. and Mitsubishi UFJ Monetary Group changing into extra selective in lending to information middle initiatives, individuals arranging the offers say. These dynamics imply corporations may wrestle to borrow for deliberate information facilities, jeopardizing development plans for the broader AI business.
Zitron has extra commentary on CoreWeave in “The Hater’s Information To Junk” from the ninth:
…this business wants a whole lot of billions of {dollars} to fund the theoretical buildout of those potentially-possible information facilities — CoreWeave alone, per UBS, wants to boost $102 billion in debt via 2030 — at a charge with no historic comparability. Even the railroad bubble of the 1800s had, based mostly on tough calculations of inflation, solely round $250 billion in complete funding in comparison with the $400 billion in issuance anticipated from hyperscalers alone in 2027.
He additionally cites Normal & Poor’s dialogue of CoreWeave’s materials weaknesses in its accounting talked about in its S-1:
CoreWeave’s efforts to handle materials weaknesses in inside management over monetary reporting are progressing as we anticipated, however will stay a score constraint till they’re resolved. The corporate is working to handle and remediate these weaknesses via IT danger assessments, enhanced management frameworks, and expanded finance and accounting employees. The measures additionally embrace partaking exterior advisors, finishing an enterprise and IT danger evaluation, and including skilled senior management to strengthen oversight and execution.
Whereas CoreWeave’s progress and timeline for addressing beforehand recognized materials weaknesses align with our expectations, potential credit score dangers may nonetheless come up as long as the weaknesses stay. It’s because the corporate can be required to offer a administration report on inside controls starting with its 2026 Kind 10-Ok, together with diminished reliability of monetary reporting and an elevated danger of monetary restatement or receiving an unqualified opinion from auditors, which might represent a violation of its affirmative covenants beneath its credit score agreements.
Nonetheless, based mostly on the remediation efforts administration intends to undertake all through 2026, we count on the corporate to take action inside this required timeframe.
…
NVIDIA’s $2 billion fairness funding in CoreWeave in January 2026 practically doubled its possession stake and deepened industrial and technological integration. This consists of preferential entry to next-generation GPUs, leveraging their monetary energy for multiyear AI manufacturing facility buildout focusing on greater than 5 GW of incremental capability by 2030, and integration of CoreWeave’s Mission Management and SUNK software program into NVIDIA’s reference architectures.
We view the software program integration as significantly important, as a result of it validates CoreWeave’s proprietary capabilities, enhances differentiation amongst neocloud suppliers, and introduces potential for incremental, higher-margin, asset-light software program income over time.
Zitron goes on so as to add:
CoreWeave sits within the fourth tier of junk at B+, has been unprofitable for each single quarter of its existence, however remains to be solely B+ as a result of, and I quote, it has “broadened its buyer base and diminished focus via latest contract wins with Meta and OpenAI, in addition to focused efforts to have interaction downstream clients, together with enterprises and AI labs.”
Whereas S&P would argue that it’s making clever, market-based judgments, it’s near-entirely basing its “constructive” outlook on hype, to the purpose that it sees NVIDIA’s deeply-circular financing — which includes it renting again its personal GPUs — as a superb factor.
That is virtually completely nonsense, based mostly on no sensible analysis of CoreWeave’s precise capability, revenues or underlying expertise. I’d like to see somebody from S&P clarify what SUNK means, or who really makes use of it — it’s, from what I can inform, a specialist AI mannequin coaching atmosphere (making it unlikely for use by any main AI lab, as all of them have their very own), and the one buyer I can discover is Unattainable Inc, which I can’t discover a lot about apart from Naval Ravikant’s incomprehensible posts about it.
I must also add that NVIDIA’s $2 billion fairness funding was not a method of “deepening its industrial and technological integration,” however a blatant try to ensure the corporate was capitalized sufficient to retain its present score and proceed to boost debt, and by some means NVIDIA backstopping CoreWeave’s information middle leases didn’t come up within the analysis.
This is identical baby-brained logic that potential collectors use too, as a result of, to cite a good friend of mine in fixed-income, no person is aware of what they’re investing in.
Effectively, that’s reassuring.
Comply with and assist my work at NatWilsonTurner.com
Associated Posts