Union Financial institution November 28, 2025
Contents:
The next is a fictional story created for illustrative functions. Whereas the characters will not be actual, their journey displays the targets and challenges many enterprise homeowners in our communities face.
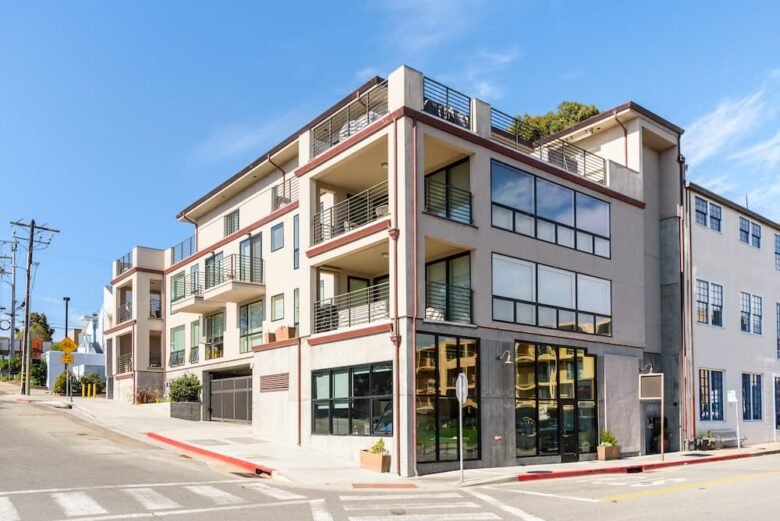
Meet Grace. For 5 years, she’s poured her coronary heart into her farm-to-table café in a leased storefront in Jackson, New Hampshire. The restaurant is an area favourite, bustling with regulars and vacationers having fun with the Mount Washington Valley. Now, her landlord is retiring and has provided to promote her all the constructing—her café house plus two flats upstairs.
Grace’s dream of proudly owning her property is out of the blue inside attain, however the path ahead appears daunting. How does the world of enterprise actual property financing work? She finds herself asking a typical query: precisely how one can get a business property mortgage?
It is a pivotal second that many profitable enterprise homeowners throughout New Hampshire and Vermont face. You’ve constructed a thriving enterprise, and now you have got the chance to spend money on its future by proudly owning its residence. This information will stroll you thru the journey from tenant to proprietor.
The Turning Level: Indicators You’re Able to Purchase
Like many enterprise homeowners at this crossroads, Grace is asking herself, ‘Is that this the best time for such an enormous transfer?’ The reply usually lies in just a few key indicators {that a} enterprise is able to transition from leasing to proudly owning.
She Craves Stability and Management: Grace has dreamed of increasing her kitchen for years, however couldn’t justify the funding in a constructing she didn’t personal. For her, the considered lastly having the liberty to renovate with out asking for a landlord’s permission is a robust motivator. Proudly owning the constructing means her location is safe, free from the specter of a lease not being renewed or a sudden, dramatic hire hike.She Needs to Construct Fairness, Not Simply Pay Lease: She considers the 1000’s of {dollars} she’s paid in hire during the last 5 years—cash that’s gone endlessly. By buying the constructing, every month-to-month fee turns into an funding in her future, constructing fairness in an asset that grows in worth. The rental earnings from the 2 flats upstairs wouldn’t solely assist cowl her business mortgage however would additionally construct her fairness even sooner, turning a significant expense right into a income.Her Enterprise is Robust and Steady: Most significantly, Grace can solely take into account this step as a result of her café is a confirmed success. She has 5 years of constant income and wholesome money move from a loyal buyer base that loves her meals. This monitor document is the one most necessary signal that she’s prepared. It offers her the arrogance—and the monetary standing—to show the dream of possession right into a viable plan.
Along with her “why” clearly established, Grace’s subsequent step is to grasp the “how”—the world of economic actual property loans.
What Is a Industrial Actual Property (CRE) Mortgage?
At its core, a business actual property (CRE) mortgage is a mortgage for a property supposed for enterprise functions reasonably than as a private residence. For enterprise homeowners like Grace, it’s a robust software to transition from renting to proudly owning. Companies throughout Vermont and New Hampshire use CRE loans to:
Buy the constructing they at present function in.Purchase workplace areas, retail places, or industrial warehouses.Purchase mixed-use properties, just like the one Grace is contemplating with flats upstairs.Finance new building or vital renovations.
How Are Industrial Actual Property Loans Completely different from a Residential Mortgage?
As Grace begins her analysis, she rapidly learns that financing a business property isn’t the identical as shopping for a house. Key variations embrace:
Mortgage Buildings and Phrases: Industrial loans usually have shorter compensation phrases than the usual 30-year residential mortgage. Phrases of 5, 10, or 20 years are widespread.Down Fee Necessities: The down fee for a CRE mortgage is usually larger, normally starting from 20% to 30% of the acquisition worth.Eligible Properties: These loans cowl a variety of properties, together with workplace buildings, storefronts, medical facilities, condominium complexes, and industrial websites.Approval Standards: Lenders focus closely on the enterprise’s monetary well being, together with its income, money move, and future projections, along with the proprietor’s credit score.
Exploring Your Mortgage Choices
When Grace sits down together with her banker, she learns she has a number of potential paths to financing her constructing. The precise selection is dependent upon the precise wants of the enterprise.
Typical Industrial Loans: That is the commonest kind of mortgage, provided straight by a financial institution like Union Financial institution. They provide aggressive charges and are tailor-made by the native lender to suit the borrower’s distinctive state of affairs.SBA 504 Loans: This program, backed by the Small Enterprise Administration (SBA), is designed to advertise enterprise development and job creation. SBA 504 loans are used to finance mounted property, corresponding to actual property or main tools. They usually function decrease down funds and lengthy, fixed-interest fee phrases, making them a really enticing possibility.SBA 7(a) Loans: The 7(a) is the SBA’s most versatile mortgage program. Whereas it may be used to buy actual property, the funds can be used for working capital, refinancing debt, or shopping for a enterprise. It’s a flexible software for enterprise homeowners with a number of wants.Development Loans: In case you plan to construct from the bottom up, or carry out renovations to an current property, a building mortgage offers short-term financing to cowl the prices of constructing. As soon as building is full, this mortgage is usually transformed right into a longer-term business mortgage.
Methods to Get a Industrial Property Mortgage: The Software Course of Defined
As soon as Grace decides to maneuver ahead, she begins the formal software course of. Figuring out what to anticipate could make the journey really feel rather more manageable.
Step 1: The Preliminary Dialog and Doc Gathering
This primary part is about getting ready your monetary story. Your lender will present a guidelines of paperwork, which usually characterize the core business mortgage necessities. Be ready to collect:
A number of years of enterprise and private tax returnsUp-to-date monetary statements (Revenue & Loss, Steadiness Sheet)An in depth marketing strategy and projectionsPersonal monetary statements for all ownersStep 2: Formal Software and Underwriting
Together with your paperwork submitted, the financial institution’s underwriting group begins its assessment. It is a deep dive into your corporation’s monetary well being, money move historical past, and creditworthiness to make sure you can comfortably assist the mortgage funds.
Step 3: The Third-Celebration Property Appraisal
The financial institution will order an appraisal from an unbiased, licensed business appraiser. Their job is to find out the property’s market worth, which is essential for verifying that the property is ample collateral for the mortgage.
Step 4: The Dedication Letter
As soon as the mortgage is authorised, the financial institution will challenge a dedication letter which is a proper supply that outlines the precise phrases, rate of interest, and situations of your mortgage. It is a second to have a good time—you’re formally on the house stretch!
Step 5: Due Diligence
As soon as authorised and you’ve got agreed to maneuver ahead with the financing, the financial institution will usually work with an legal professional to analysis the title to the property, get hold of flood determinations on the property in addition to environmental screens. These are all accomplished to make sure that the property you’re buying doesn’t have any avoidable points.
Step 6: Closing
The ultimate step is the closing, the place each events signal all authorized paperwork, and the funds are transferred to the vendor. At this level, Grace will get the keys to her constructing and formally turns into a business property proprietor.
The Benefit of a Native Lending Accomplice
When Grace began exploring her choices, she realized she wanted a banker who understood the Mount Washington Valley market—its seasonal tourism, its year-round group, and the worth of a mixed-use property just like the one she needed to purchase.
At Union Financial institution, we don’t simply finance buildings; we’re a trusted advisor and spend money on native goals. Our business lending group lives and works in Vermont and New Hampshire. We make our selections domestically and are devoted to discovering inventive, versatile options to assist companies like yours succeed. We’ll sit down with you to grasp your story, your corporation, and your imaginative and prescient for the long run.
For enterprise homeowners from Burlington to Jackson, proudly owning your property is the last word expression of permanence and success. It’s an enormous step, however you don’t must take it alone.
Able to discover your choices for a business actual property mortgage? Contact our skilled business lending group in the present day to start out the dialog.