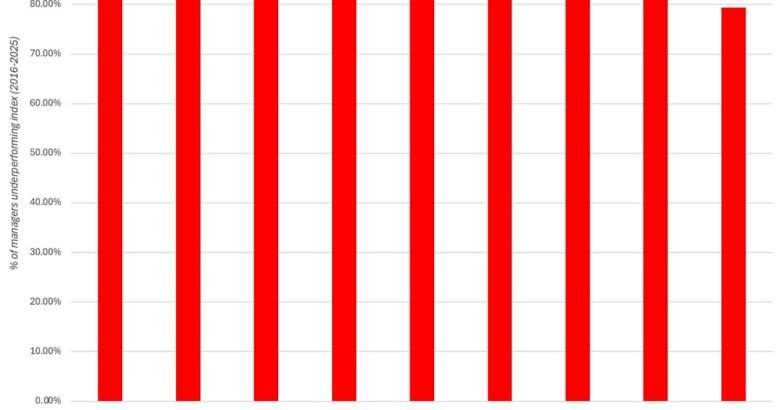
When uncertainty roils markets, as is the case proper now, it’s pure for buyers to get knocked off stability, a when off-balance, to make funding choices that they usually remorse later. It’s throughout these instances that it helps to have a core set of beliefs about markets, and an funding philosophy that displays these beliefs. You could not have the ability to mend the harm to your portfolio, however it can assist you discover stability once more and make sense of the noise round you. As an investor, my funding philosophy has been a work-in-progress, however I’ve had an curiosity in how the buyers round me develop their philosophies, and why variations persist. That curiosity was precipitated by a seminar class that I organized for NYU Stern MBAs within the late Nineties, the place profitable buyers with very totally different market views and investing types introduced their factors of view, and college students struggled to reconcile their totally different and contradictory factors of view. Within the aftermath of the category, I began engaged on a ebook and a category on funding philosophies, the place the tip recreation was to not discover the “finest” philosophy, however to supply a framework for buyers to search out the philosophy that most closely fits them. The primary version of the ebook got here out virtually twenty years in the past, adopted by a second version in 2012. Along side the second version of the ebook, I created a free on-line model of the category on my webpage in the identical 12 months, and NYU created a certificates class about six years for the category. Whereas my core pondering on funding philosophies has nto modified, markets and the financial system have, and each the ebook and the category have been in want of an replace. I spent the previous few months engaged on that replace, and the third version ought to be obtainable at ebook shops within the coming week, and in conjunction, I’ve an up to date (free) on-line model of the category on my webpage and on YouTubeThe Origins Within the late Nineties, I used to be approached by the Stern Faculty of Enterprise with a request to function the organizer for a category on investing, the place MBA college students would spend a session per week, for a semester, listening to from profitable buyers of all stripes, and talk about what they realized from that speak in a second session every week. Over the course of the semester, the category had fourteen audio system, and due to our New York location, it drew from a variety of investing varieties. Thus, college students heard from a widely known worth investor one week, the supervisor of one of many best-regarded development mutual funds the subsequent, a high-profile technical analyst within the third, and so forth. The audio system approached investing in very other ways and had totally different views on monetary markets and the best way to exploit market errors, however all of them had been profitable as buyers. As I led the dialogue of every speaker’s market views and funding practices every week, I observed college students in my class growing whiplash, as they instinctively attempt to incorporate the views and practices of every speaker into their pondering. Because the weeks went on, that turned an issue, since apart from funding success, the audio system shared little in frequent, and their views about markets had been generally contradictory. By the tip of the category, there was a pretty big subset of the scholars who ended up extra confused by what that they had heard throughout the semester, moderately than enlightened. As I reviewed the category, earlier than handing it off to another person, I took a listing of what I had seen not simply within the class, however in investing generally, and got here to the next common judgments about investing:There are only a few energetic buyers, who win persistently over time: Energetic investing is without doubt one of the most tough video games to win at, and one cause is that you simply match the typical investor, effortlessly and virtually costlessly, by investing in index funds. Energetic investing has the unenviable process of attempting to be higher than common, and by sufficient to cowl the prices (analysis, information, personnel, transactions) related to being energetic. Simply as illustration of how a lot of a mountain that is to climb, check out the proportion of energetic institutional buyers who beat their respective indices during the last decade:Whereas there some energetic cash managers who “beat the market” over a 12 months, two years and even 5, only a few are in a position to maintain on to those extra returns as you lengthen their energetic investing stint. Like gamblers in a on line casino, who strike it fortunate early, however keep gambing too lengthy, they usually depart with none of their features, or worse. Earlier than I get a blowback, I’m absolutely conscious that that there are investing legends (Warren Buffett, Jim Simon and George Soros, to call simply three), however the actual fact that we are able to identify them means that they’re the exceptions, not the rule.Even with these profitable few, it is extremely tough to separate luck from talent: A lot as funding books and lessons declare in any other case, investing outcomes are affected by so many forces which are out of your management that disentangling how a lot of your ultimate returns might be attributed to talent and the way a lot to luck could be very tough to do. These profitable buyers have broadly totally different pathways to delivering success: Should you had been to make a listing of the buyers who’ve had essentially the most success in markets within the final century, I might wager that you’d be taking a look at a really various group, not simply when it comes to how they succeeded, but in addition when it comes to persona. The three buyers I named as legends – Buffett, Simon and Soros – clearly had very totally different views on markets, and the best way to exploit market errors, however even with buyers who are sometimes seen as being from the identical grouping, variations stay. Buffett could have realized his early classes from Ben Graham, however the Graham and Buffett approaches to worth investing are different, with the previous extra centered on screening for reasonable shares and the latter extra eager about discovering corporations with stable moats and nice administration. Imitating profitable buyers doesn’t appear to supply a lot payoff: The practices of profitable buyers have been probed and investigated by different buyers and journalists, and a few of them have dozens of books that declare to inform you the key of their success. Warren Buffett is maybe the winner on this race, with not solely a large number of books that observe his investing life but in addition his annual letters to Berkshire shareholders which laid out his investing perspective intimately. That mentioned, the buyers who tried to comply with in his footsteps, usually imitating each side of his method, have, for essentially the most half, not been in a position to match his success. My takeaways from these assessments are two fold. The primary is that there might be nobody dominant funding philosophy that’s the finest for all buyers, and any claims on the contrary, whether or not or not it’s for worth investing or market timing or buying and selling, are disingenuous. The second is that there’s a proper funding philosophy for every person that displays that particular person’s views and beliefs about markets and traits as an individual.The Core Thought The popularity that every investor wants an funding philosophy that’s tailored to his or her beliefs and persona turned the start line for my creating a category, and writing a ebook, in regards to the subject. Earlier than I describe what I attempt to do within the ebook, I ought to begin with a definition of what I imply by an funding philosophy, and maybe one of the simplest ways to try this is by describing what it’s not. First, an funding philosophy is way richer and extra full than an funding technique, with the latter usually popping out of the previous. Thus, making use of a display to search out shares that commerce at low multiples of earnings (low PE ratios or low a number of of EBITDA) is an funding technique, however the funding philosophy that offers rise to that technique is one that’s constructed on markets below pricing corporations with low development or boring companies, maybe as a result of buyers are dazzled by development and drawn to the thrill of newer companies. Second, an funding philosophy will not be an funding slogan. “Purchase low, promote excessive” is an funding slogan, and a meaningless one at that, since that’s the finish recreation of just about each funding philosophy. You probably have been investing for some time, and have by no means stopped and requested your self what your funding philosophy is, it’s comprehensible. In truth, you could marvel why you need to constrain your self to an funding philosophy as an alternative of in search of bargains wherever you’ll find them. The issue with not having a core philosophy is that’s exposes you, as an investor, to an entire host of penalties, most of that are detrimental:Chasing winners: If you do not have an funding philosophy, it’s virtually a on condition that you will discover your self drawn to no matter methods labored finest within the latest previous. Your portfolio will undergo from whiplash as you chase final 12 months’s winners, whether or not that be the Magazine Seven or expertise shares or small cap shares, and whereas your turnover and transactions prices rise, you’ll have little to indicate when it comes to returns.Rip-off goal: Greed is common, and that leads us to search for methods to make numerous cash with little or no danger. With out an funding philosophy constraining you, you may be a straightforward mark for funding scams, drawn in with guarantees of upside with little or no draw back.Empty investing cabinets: Should you do discover an funding technique that works at delivering returns, it’s value remembering that the clock is ticking, and that imitation and market corrections will trigger that technique to cease working, sooner moderately than later. If that’s all you delivered to the market, your investing cabinet might be empty and you will discover your self working to remain in place. The benefit of getting a coherent, effectively thought by way of funding philosophy is that you may return to it and mine it for different methods that will exploit the identical market errors. Thus, in case your funding philosophy is that markets undervalue boring, low-growth corporations, and low PE ratios are not doing the trick (of discovering low cost shares), you could search for different screens (low volatility) that discover you boring corporations which are mispriced.Merely put, each investor wants an funding philosophy to information her or him within the tough process of attempting to delivering success. Fairly than create a laundry record of philosophies, I’ll use the funding course of because the automobile to explain how and the place the totally different funding philosophies emerge from, in addition to diverge:Utilizing this course of, the alternatives in funding philosophies emerge:1. Energetic investing versus Passive indexing: If, as we famous within the final part, doing nothing can ship returns approximating the typical, and 9 out of ten buyers who attempt to beat the typical fail, there isn’t a disgrace in adopting a passive indexing philosophy, the place your allocation throughout asset lessons is set by your danger aversion and want for liquidity, and index funds fill out the remainder of the dance card. It’s human nature, although, to hunt to be higher than common, and it’s maybe that want that drives many into energetic investing decisions, and there are a number of pathways that they’ll undertake.2. Investing versus Buying and selling: The second divide in investing philosophies comes from the distinction between worth, which is pushed by cashflows, development and danger, and worth, decided by demand and provide. Investing requires assessing the worth of an asset, shopping for if the value is decrease than that worth and promoting whether it is larger, and ready for the hole to shut. Buying and selling, then again, is about gauging market temper and momentum, shopping for in case you anticipate these forces to drive the value up and promoting in any other case. Inside every of those groupings (investing or buying and selling), there are sub-groupings. Buying and selling can take totally different tacks, relying on the place you assume that market errors lie. The primary, worth merchants, use the knowledge on costs and buying and selling quantity to detect shifts in temper and momentum, with charts and technical indicators as instruments, to try to generate income. The second group, info merchants, trades round info releases, corresponding to earnings studies, acquisition bulletins and even insider trades, with some buying and selling forward of the information, some on the time the information is introduced and a few within the aftermath, all attempting to reap the benefits of what they see as market errors in reacting to that info. The third group, arbitrageurs, centered on discovering the identical or associated property buying and selling on totally different markets, in search of mispricing throughout these markets, and locking in that mispricing as extra returns. Traders, as an illustration, might be drawn to worth or development, and whereas that distinction is commonly acknowledged when it comes to pricing multiples, with worth buyers shopping for low priced shares (low PE, low worth to ebook and so forth) and development buyers drawn to larger development and excessive priced corporations, I choose to think about the variations when it comes to the place every group thinks it could discover bargains. Utilizing my monetary stability sheet assemble, the place I divide the worth of a agency into the worth of investments already made (assets-in-place) and investments anticipated sooner or later (development property), worth buyers view their odds of discovering market errors to be better with assets-in-place, whereas development buyers really feel that their odds are higher find misvalued development property:Inside worth and development investing, there are additional sub-divides. Worth investing can span the spectrum from passive screening, the place you display for shares which have particular traits (low PE, excessive development, excessive ROE) and label them as low cost, to extra activist poses, the place buyers with deep pockets (particular person activist, personal fairness funds) not solely take positions in corporations that they imagine are below or over valued, but in addition push for change at these corporations. Development investing has its personal model of activist investing, within the type of enterprise capital, invested in younger, development corporations, the place along with supplying capital for development, enterprise capitalists take an energetic position in how these corporations evolve over time and exit {the marketplace} (IPOs, sale to a different firm).3. Market Timing vs Inventory/Asset Selecting: In market timing, your focus is much less on particular person shares or property and extra on deciding whether or not a market (equities, bonds, actual property and so forth.) is below or overvalued. Returning to the funding course of, your focus is on allocating your portfolio throughout asset lessons, based mostly in your market views, underweighting “costly” asset lessons and overweighting “low cost” ones. In inventory/asset choosing, you are taking the market as a given and attempt to discover the perfect particular person investments inside every funding class for you – the most cost effective shares, bonds and actual property that you’ll find. There’s an ironic contradiction in making this alternative. It’s plain {that a} profitable market timer will make far extra money than a great inventory picker, however additionally it is true that it’s rather more tough to be a profitable market timer than it’s to be a great inventory picker. The image under captures the alternatives when it comes to funding philosophy, framed when it comes to the place they enter the funding course of:Even in case you really feel that you’ve got an funding philosophy in place, I feel being conscious of how others method markets and conserving an open thoughts, the place you borrow elements of different philosophies and incorporate them into yours will make you a greater investor.Discovering an Funding Philosophy Wanting on the menu of funding philosophies, from passive indexing to arbitrage, my finish recreation in my ebook and for the category on funding philosophies was to not advance a single philosophy and even evaluate them, however to supply as unbiased and full an image, as I may, of the info backing every philosophy and extra importantly, the non-public traits that you’d must succeed with that philosophy. Step 1: Views on Market Errors and Corrections Step one find your funding philosophy is with a view of the place (and why) markets make errors, and the way they appropriate them. Even the firmest believer in environment friendly markets will concede that markets not solely make errors, however generally make large ones, however the divergence between them and energetic buyers lies within the nature of those errors. In an environment friendly market, market errors might be random, and since there isn’t a systematic sample to them, there isn’t a pathway for energetic buyers to search out these errors, even with entry to information and highly effective instruments. Energetic buyers, in distinction, imagine that there are systematic patterns that you need to use to search out these errors, and to take advantage of them for income, with merchants believing that these patterns are within the pricing and quantity information and buyers hewing extra to fundamentals. That mentioned, energetic buyers can and can disagree in regards to the kinds of market errors, with some shopping for into the notion that markets be taught slowly, whereas others imagine that markets overreact, and it’s wholesome for buyers to have these disagreements. Step 2: Choose an funding philosophy that displays market views Your views on market errors and corrections ought to information you in your alternative of funding philosophies. Thus, in case you imagine that markets overreact to information, good or dangerous, you could determine to grow to be a contrarian, both buying and selling (by shopping for after dangerous information and promoting after good) or by investing (by shopping for corporations with stable fundamentals whose inventory costs have dropped by excess of they need to have). Conversely, in case you imagine that it’s momentum, not fundamentals, that’s the greatest drivers of inventory worth actions, you could select to trip that wave, based mostly on charts and technical indicators. Superimposing time horizon onto the kinds of errors that markets make, you may create a matrix of funding philosophies:Do it’s a must to decide a single philosophy? Not essentially! You’ll be able to meld two or much more than two philosophies collectively, so long as you meet two situations. The primary is that the melded philosophies need to share a core perception about market errors. Thus, in case you imagine that market s overreact, you is usually a contrarian worth investor, shopping for corporations which were overwhelmed up in markets however have intact fundamentals, and timing your purchases proper after dangerous information releases, when markets overreact. The second is that it’s a must to establish which of the philosophies is your dominant one, and which one is secondary, permitting you break ties the place the 2 push you in several instructions. Staying with the melded contrarian philosophy, and assuming that the contrarian worth philosophy is your dominant one, you’ll select to to not purchase a inventory that’s down 15% after a foul earnings report, whether it is nonetheless buying and selling nearer to its highs than lows.Step 3: Test for viable methods Funding philosophies are a essential part, however to become profitable on a philosophy, irrespective of how effectively thought by way of, you must devise funding methods that may generate income for you. In developing with these methods, you’ll confront the 2 realities that trigger many methods that look good on paper to fail: transactions prices and taxes. On the transactions price entrance, the brokerage buying and selling price is only a small a part of the general price, with two different prices that may usually be a lot bigger. The primary is the bid-ask unfold, small for big, very liquid shares, however a lot bigger for smaller and fewer liquid investments. The second is worth affect, once more non-existent if you’re a small investor shopping for or promoting shares in a big market-cap firm, however substantial if you’re a big investor buying and selling on an obscure inventory.On the tax entrance, some methods will create extra tax prices than others, partly due to how funding earnings is taxed (dividends create quick tax penalties however capital features require buying and selling to incur tax liabilities) and partly due to how a lot buying and selling your technique would require of you, with larger turnover typically creating extra tax legal responsibility.In case you are planning on being an energetic investor, there may be one ultimate talent set that you will want to accumulate, and that’s the capability to check whether or not a method can beat the market. The volatility in returns can generally create illusions, the place a method seems like it’s delivering extra returns, however these returns are virtually fully resulting from statistical noise.Step 4: Test for private match Funding philosophies, and the methods that emanate from them, include totally different calls for when it comes to time horizon, with some requiring holding on to investments for a few years and others requiring buying and selling in minutes, totally different danger publicity and divergent tax penalties. Traders who select to undertake these philosophies need to replicate on whether or not they’re good matches, on the next fronts:Capital to speculate: In case you are simply beginning in your funding journey, and have solely a small quantity of capital to speculate, your decisions when it comes to funding methods slim. You’ll positively not have the ability to be an activist investor, since you’ll have no weight (when it comes to cash invested or shares held) to throw round, and you could lack the wealth to purchase illiquid, small corporations, if that’s the place you assume market errors are most frequently discovered, because you will be unable to unfold your bets. The excellent news is that you simply proceed to construct up your capital, your funding decisions will widen, and you may modify your funding methods accordingly. On the different finish of the spectrum, and that is maybe extra the case if you’re managing different individuals’s cash, you may have a lot capital to speculate that some funding methods grow to be infeasible. For example, if you’re planning on investing in illiquid, small cap shares, having billions of {dollars} to speculate will improve your transactions prices (by growing worth affect once you commerce).Time horizon: Many buyers, when requested the query about time horizon, declare to have very long time horizons, actually because they imagine that it’s the reply that “good” buyers give. The reality is that for many buyers, time horizon is as a lot decided by exterior components, corresponding to age, well being and liquidity wants, as it’s by inner motivations. If it’s a must to pay tuition on your youngsters or anticipate to have substantial hospital payments within the close to future, your time horizon simply turned shorter, and that must be factored into your alternative of funding methods.Danger publicity: As with time horizon, the willingness to take danger is partly a operate of your private make-up and partly decided by your life standing. You probably have collected wealth and have a job with a secure (or rising) earnings that greater than covers your bills, you’re higher positioned to take dangers than if you’re on the verge of retirement, and are investing cash that you may be needing quickly to cowl your post-retirement money wants.Private qualities: Your persona and traits additionally come into play in your alternative of funding philosophy and techniques. In case you are, by nature, impatient, it’s unlikely that it is possible for you to to maintain a method of shopping for undervalued corporations and ready for a very long time for errors to appropriate. Equally, if you’re simply swayed by peer strain and what the remainder of the world is pondering and doing, it’s tough to be invested in contrarian causes, short-term or long-term. Lastly, in case your technique requires particular expertise to be put into movement, you’ll have to both have or purchase these expertise; a method constructed round discovering undervalued corporations would require that you understand how to worth corporations and one constructed round analyzing massive and complicated datasets in search of mispricing wants statistical and information evaluation knowhow.When investor traits and funding philosophy wants are mismatched, there are two detrimental penalties. The primary is that, missing endurance, buyers will abandon methods effectively earlier than they need to, just because they’re uncomfortable with how they’re enjoying out. The second is {that a} mismatch creates an emotional price, the place buyers battle with their portfolios and fail what I name the sleep check, the place their portfolio’s gyrations hold them awake at night time.Step 5: Preserve the suggestions loop open You probably have discovered an funding philosophy that maps on to your market beliefs, discovered viable methods that replicate that philosophy and matched it to your private make-up, you could have reached regular state, however just for the second. That’s as a result of virtually each a part of this course of is topic to alter, some due to exterior forces, and a few due to private adjustments.Financial setting: Over time, financial settings and constructions change, and funding philosophies need to adapt and even be deserted. For example, I’ve argued that expertise and disruption have created winner-take-all companies within the twenty first century, and in case you purchase into that argument, an funding philosophy (and techniques) constructed round small cap corporations will not ship the payoff it did within the twentieth century.Market classes: Your views on market errors come from taking a look at information and your personal experiences available in the market, and as a consequence, they need to be revisited as markets change. Simply on this century, markets have been examined by crises (the monetary disaster of 2008, the COVID meltdown in 2020 and the tariff bulletins final April, simply to call three), and it’s turning into more and more apparent that property throughout lessons (shares, actual property and so forth) and geographies are shifting way more in sync with one another than they did within the final century. That actuality must be built-in into your market views and the funding philosophy/methods that you simply use.Buying and selling microstructure: It’s plain that entry to info and buying and selling on most property has grow to be simpler over the previous few a long time. That’s good, nevertheless it does include a value. Funding philosophies constructed across the assumption that the majority buyers, particularly retail and particular person, wouldn’t have the ability to entry information or commerce simply, might have tweaking, adapting and even abandonment.Private adjustments: It will not come as no secret to you, however you’re going to get older, the quantity of capital it’s a must to make investments will change, your well being and household obligations will shift, and you could even grow to be roughly affected person or roughly vulnerable to see strain. These components will all feed into your funding philosophy.The investing world doesn’t lend itself to absolutes. One of many pink flags in buyers (retail or institutional) is certitude about their funding decisions and views, and an unwillingness to even contemplate alternate options, an indication that they are going to be unable to alter because the world adjustments round them.E book, Class, each or neither? I like writing, not a lot for its business potential, however as a result of it permits to get my ideas so as. I wrote the primary version of my funding philosophies ebook in ___, and it adopted a construction that I’ve stayed true to, in subsequent editions. I begin the ebook, with an outline of what an funding philosophy is and the way it first into the funding course of, shifting on a foundational part, the place I take a look at danger measures, the best way to learn accounting statements and do intrinsic valuation, how transactions prices and taxes drain returns, and at the best way to check funding methods that declare to beat the market. In chapters 7 by way of 12, I spend every chapter taking a look at a broad funding philosophy (and associated methods), inspecting proof for and in opposition to every one within the information earlier than outlining what you (as an investor) must convey to the desk to succeed with every one. I shut the ebook, by offering the sobering counter proof to energetic investing, the place I take a look at how tough it to win at that recreation and the promise and peril of different investments (gold, cryptos, superb artwork, actual property). You probably have one among my earlier editions, is it value upgrading? You probably have the primary version, I do imagine it’s time, however in case you do have the second version and are budget-constrained, you may maintain off. You will discover the ebook on-line at Amazon and Barnes and Noble, with the latter providing a 25% low cost, beginning right now (March 24). In parallel, I developed a category that had the identical content material, and whereas the NYU certificates model of the category will price you, I’ve had a free on-line model on my webpage, which I created in 2012. That class was in want of an replace, and as I completed up the third version of the ebook, I created a brand new model of this class, with forty two periods protecting the identical materials because the ebook. Once more, in case you have taken the sooner model of the category, you could discover the fabric repetitive, however I hope that the up to date information and the add ons enable for a richer expertise. You probably have by no means taken this class, and on-line studying works for you, it’s designed for buyers, particular person in addition to institutional, and requires little when it comes to technical information, and I hope that give it a shot.The Investing Finish Sport All of us share the identical finish recreation in investing, which is to generate the best returns on the capital we make investments, although there are broad variations in how a lot danger we’re prepared to take and the way lengthy we’ll wait earlier than cashing out. That’s the definition of funding success, however on condition that there are such a lot of forces which are out of our management, you are able to do every part proper and nonetheless fail to satisfy your targets, leaving you pissed off and questioning your self. It’s for that cause that a greater endgame is to hunt out funding serenity, the place you find yourself with an funding path that you’re snug with, and settle for the outcomes that emerge, good or dangerous. I’ve spent this complete publish speaking about funding philosophies, and in case you haven’t observed, I’ve not proven my hand, on my funding philosophy. I’ve by no means believed in hiding behind imprecise and opaque generalities, and my funding philosophy is constructed round three rules:Intrinsic worth issues: I imagine that each asset (something that generates money flows) has a intrinsic worth, and that with creativeness and a willingness to make errors, you may estimate that intrinsic worth for any firm, from start-ups to corporations on the verge of default. I imagine that a lot of what passes for valuation in follow is pricing, the place individuals utilizing pricing metrics (corresponding to PE ratios or EV to EBITDA multiples) to make pricing judgments, and {that a} good valuation requires understanding enterprise fashions, telling tales and changing these tales into valuation inputs and worth estimates.Markets are for essentially the most half proper, however make errors in periods of uncertainty and alter: I by no means stop to marvel at markets, the place thousands and thousands of people with disparate views and data attain consensus on a worth. In an age the place we’ve turned over our decisions on what motion pictures to look at to Rotten Tomatoes, and which restaurant to eat at to Yelp!, it’s value remembering that markets had been the unique fount for crowd knowledge. That mentioned, additionally it is true that markets have offered us with illustrations of crowd insanity, the place the collective knowledge is hopelessly fallacious, and I imagine that that is usually the case when buyers face important uncertainty, as is the case when corporations transition from one stage of the life cycle to a different, whole business teams are confronted with the specter of disruption and markets are put into upheaval by crises. Do no hurt: Whereas I hunt down investments to make that may beat the market, I’m cognizant of the truth that I’m not entitled to rewards, simply because I put within the work, and that luck and likelihood nonetheless can wreak havoc on my best-laid plans. Particularly, I’ve realized, by way of expertise, that my greatest errors come from overreach and overactivity, and I’ve constructed that studying into my funding philosophy by:Spreading my bets: I’ve written earlier than in regards to the focus versus diversification argument, and that what you select to do as an investor might be a mirrored image of how a lot confidence you could have in your funding decisions, or “conviction”, in investing parlance. I have to confess that I don’t share the conviction that concentrated buyers convey to the sport, and never solely unfold my portfolio over three dozen shares, but in addition comply with inflexible guidelines on not letting any single funding exceed 15% of my portfolio.Appearing not often: I don’t commerce usually, and after I do, I comply with the previous adage of measuring twice (or 3 times) earlier than chopping (buying and selling). It helps that I don’t observe the market or my portfolio holdings all day, virtually by no means watch the monetary information and am not simply swayed by funding gross sales pitches. Staying away from my weaknesses: I steer away from energetic market timing and sector bets for a easy cause. I’m not good at both, and what I would achieve from an occasional win might be worn out by what I lose in the long run. Being conscious of my blind spots: I attempt to be self-aware, although I don’t all the time succeed. I do know that I’m thrown off my recreation plan by taxes (I don’t like enjoying them, and that generally will get in the way in which of doing what I ought to be doing) and I generally fall in love with firm narratives, as a result of I need them to be true. That is my philosophy, it displays my strengths and persona, and it really works for me. I sleep effectively at night time and I’ve no regrets, however I’m fortunate since I’ve an clientele of 1 (or maybe two) to fulfill. My hope, with each my ebook and sophistication, is that it gives you with the alternatives and materials so that you can discover an funding philosophy that works for you and that it delivers the returns you hope to earn, and even when it doesn’t, helps you to sleep effectively at night time!YouTube VideoInvestment Philosophies BookInvestment Philosophies Class
In Search of an Funding Philosophy