Yves right here. This text argues that although banks in sanctioned nations have made effort to maneuver to make use of different currencies, the variety of “hops” in doing so is an obstacle. The result’s that use of the renminbi has not elevated as a lot as most observers anticipated.
By Gregor Matvos, Howard Berolzheimer Chair in Finance, Kellogg College of Administration Northwestern College and Brent Neiman, Edward Eagle Brown Professor of Economics, Sales space College of Enterprise College Of Chicago. Initially revealed at VoxEU
Direct proof on the consequences of economic sanctions stays restricted. This column makes use of correspondent banking information to check how sanctions have an effect on entry to world fee networks. The greenback and euro networks supply probably the most environment friendly connections to banks in different nations. Moreover, monetary sanctions imposed throughout 2021-2026 lowered focused banks’ entry to major-currency networks, making it tougher for sanctioned establishments to make or obtain funds. Non-sanctioned banks in closely sanctioned nations additionally misplaced connectivity to those networks however reoriented in direction of alternate options, notably the Chinese language yuan. Extra usually, shifts away from the greenback and in direction of the yuan stay minimal.
The US Treasury’s current ‘Operation Financial Outcast’ marketing campaign towards Iran goals to sever Iran’s monetary connections to the remainder of the world. Do sanctions reminiscent of these levied towards Iran’s banks work? If that’s the case, how? Does utilizing sanctions as we speak weaken their effectiveness tomorrow?
A quickly rising theoretical literature addresses these questions. Farrell and Newman (2019) and Clayton et al. (2024, 2025) focus on how nations can use management over key networks to exert geopolitical energy. Bianchi and Sosa-Padilla (2025) mannequin how the usage of sanctions would possibly result in lowered future use of the greenback. However onerous empirical proof is proscribed on why overseas corporations depend on the greenback community or whether or not sanctions have an effect on banks’ entry to it.
In a recnent paper (Matvos and Neiman 2026), we study these questions utilizing correspondent banking information. We use industrial information from LexisNexis Threat Options on correspondent banking relationships – the accounts banks maintain with each other to ship and obtain funds throughout borders – overlaying greater than 17,000 monetary establishments in rising market and creating economies (EMDEs). We merge these information with information on monetary sanctions designated by the US, EU, and the UK from September 2021 to August 2026.
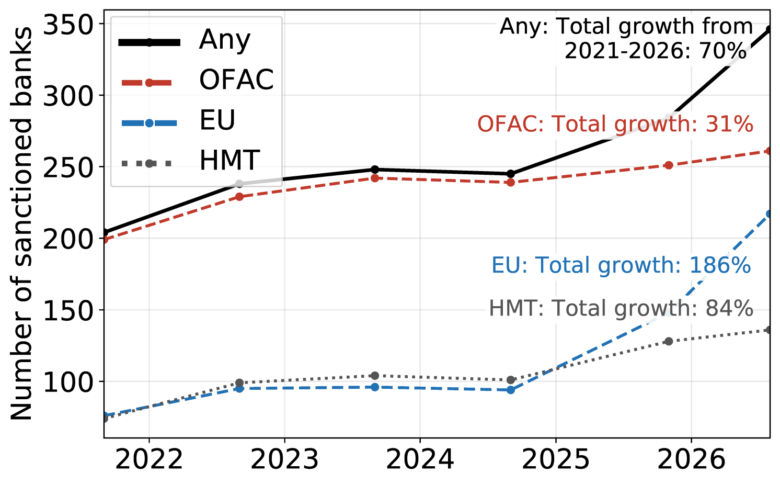
Understanding how monetary sanctions work is more and more pressing as sanctions exercise of every kind has trended upwards for many years (Felbermayr et al. 2020). The variety of entities on the US Treasury’s major sanctions record has grown from underneath 1,000 in 2000 to just about 20,000 as we speak. In our pattern, the variety of rising market and creating financial system banks sanctioned by the US, EU, or the UK rose by about 70% in 5 years, from 204 to 346 (Determine 1). Russian banks account for many of the improve, with substantial expansions additionally in Belarus and Kyrgyzstan.
Determine 1 Rising market and creating financial system banks underneath sanctions, by authority, 2021-2026
Supply: Matvos and Neiman (2026), Determine 3.
Our work asks and solutions 4 key questions:
1) Are the greenback (and euro) networks probably the most helpful for world funds?
Sure. To point out this, we begin by explaining the function of correspondent banks in cross-border funds. Whereas home transactions profit from a shared central financial institution, this isn’t the case for worldwide transactions. As such, a financial institution that wishes to obtain {dollars} does so by holding a greenback account at one other financial institution, known as a correspondent, which could be credited. Take into account an importer paying an exporter. If their banks share a correspondent, the correspondent can settle the fee by debiting one financial institution’s account and crediting the opposite’s. If not, the fee should go by means of a sequence of intermediaries. Every hyperlink within the chain – every ‘hop’ – provides charges, compliance checks, the price of prefunding accounts, and counterparty danger.
Greenback and euro networks usually join banks in fewer hops than different forex networks. Of rising market and creating financial system banks that record any correspondent, 90% have one for {dollars} and 88% have one for euros. Against this, solely 62% have one for British kilos, and 34% for yuan. Additional, greenback and euro chains join 4 to 5 instances as many cross-border financial institution pairs as yuan chains, and accomplish that in fewer hops – under three on common, versus practically 4 for the yuan. For roughly three-quarters of related financial institution pairs, the shortest fee path runs by means of the greenback or euro community. The yuan presents the shortest path about 3% of the time.
Additional, the better connectivity supplied by the greenback community is owed largely to the presence of key hubs that sit within the US jurisdiction. The ten most central banks – hubs within the community – account for 77% of the full PageRank of the greenback community, indicating a excessive focus of community centrality. The comparable determine is about half for the euro and the yuan. Entry to probably the most environment friendly fee infrastructures runs by means of a small set of establishments to which US and European authorities can deny entry.
2) Do sanctions reach reducing targets off?
Largely, sure. Sanctions sharply reduce focused banks’ entry, throughout practically all currencies and counterparty nations.
Sanctioned banks lose their correspondent relationships. Of these banks which are finally sanctioned and that report at the very least one correspondent relationship, the chance that they’ve greenback correspondents drops from 89% to twenty% after being sanctioned by the US. The share with a US-based greenback correspondent falls to 11%. Comparable losses happen for sanctioned banks’ euro, pound, and yuan correspondent relationships.
Additional, their remaining community entry additionally deteriorates. Earlier than designation, finally sanctioned banks preserve relationships with greenback correspondents that collectively account for about 15% of the full PageRank of the greenback community. After designation, they lose entry to crucial correspondents, so this share falls to under 2%.
Consequently, the size of fee chains from sanctioned banks to the remainder of the world grows considerably. The variety of hops sanctioned banks want to attach with reachable banks of their residence nations’ 5 largest buying and selling companions rises in all currencies we research, apart from the Russian ruble.
Sanctions make funds costlier, slower, and riskier, usually routed by means of oblique clearers in third nations.
3) What occurs to untargeted banks in closely sanctioned nations?
In closely sanctioned nations like Belarus, Kyrgyzstan, Myanmar, and Russia, even untargeted banks lose entry to Western fee networks. They equally lose entry to greenback, euro, and pound correspondents. The seemingly driver is de-risking: correspondents reduce ties with whole jurisdictions relatively than danger secondary sanctions or compliance failures. The country-level penalties are substantial. Throughout all Belarusian banks, cross-border correspondent relationships in {dollars}, euros, and kilos fell from 139 in 2021 to 19 by 2026. Additional, the greenback correspondents that remained had been positioned in Kazakhstan and China, not within the US.
Non-sanctioned banks in these economies, nevertheless, shifted in direction of different fee networks. The yuan’s share of their cross-border correspondent relationships rose sharply. As proven in Determine 2, the shift has stark penalties for the relative effectivity supplied by every forex’s community. In 2021, the greenback or euro supplied the shortest fee path from Belarusian banks to greater than 80% of reachable overseas banks. At the moment, the yuan virtually by no means supplied the trail with fewest hops. Nevertheless, by 2026, the image had modified. Greenback and euro networks collectively accounted for lower than half of the set of shortest paths, whereas the yuan accounted for about 20%, greater than the greenback alone. Kyrgyzstan and Russia present related patterns.
Determine 2 Foreign money delivering the shortest fee route, 2021 versus 2026
Supply: Matvos and Neiman (2026), Determine 15.
4) Is that this proof of a world decline within the greenback’s function?
No – not in our information, and never but. As proven within the closing bars of Determine 2, throughout all different EMDEs, the forex composition of shortest fee routes was primarily unchanged between 2021 and 2026. The greenback and euro nonetheless present the shortest route for roughly three-quarters of reachable financial institution pairs. The yuan’s share rose by about one share level.
Brunnermeier et al. (2022) predicted firstly of the Russia sanctions that the greenback’s dominance would survive, and Eichengreen (2023) reached an identical verdict from information on official reserves. Up to now, our funds information agree and solely doc a shift away from the greenback within the small set of economies the place sanctions hit hardest.
See authentic publish for references