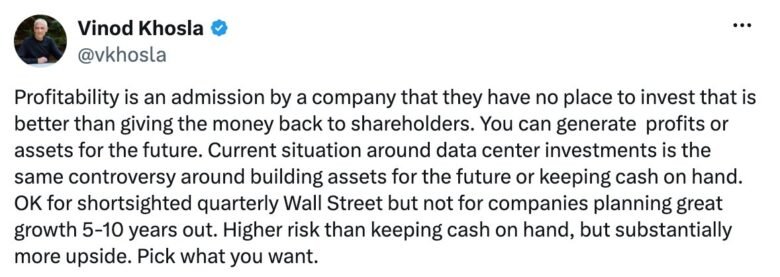
It’s simple expertise corporations have discovered their most hospitable setting in the US and whereas there are various causes for the US dominance of expertise, simpler entry to capital for younger companies has been a key ingredient. Enterprise capital within the US, in its institutional and arranged kind, can hint its roots again to the Fifties, and over the previous couple of many years, it has generated its share of legendary buyers. Vinod Khosla is a type of legends, and it’s for that motive that I used to be stunned to see him tweet the next:
I perceive that utterances on social media, usually in response to feedback by others or made in anger, are sometimes rapidly regretted, and I consider (although I’m not sure) that Mr. Khosla didn’t fairly imply what he mentioned right here, complicated profitability with money flows, and arguing that each enterprise ought to put scaling forward of profitability. That mentioned, his view that scaling needs to be given precedence over profitability is extra the norm, than the exception, amongst many enterprise capitalists, and whereas it most likely all the time has been the case, I consider the lean in the direction of scaling has grow to be pronounced within the final twenty years. On this put up, I need to zero in on the scaling and profitability commerce off, how the emphasis on the previous over the latter performs out at start-ups and really younger corporations, and why we reside with the results, whether or not they need to or not.
Scaling versus Enterprise Constructing
To place the alternatives you’ll face on scaling up versus enterprise constructing into perspective, let’s assume that you’re a founder, and that your start-up has a examined product and that you simply consider there’s a marketplace for that product. You’ll be able to stick with what you’ve constructed and construct a enterprise to benefit from the rapid market, specializing in monetary well being and profitability. The truth that you’ll keep small, and maybe unrecognized in markets aside from your personal, is a minus, however there are pluses. You should have no use for exterior capital, and you’ll personal a lot or all the enterprise, dealing with little strain from outdoors to alter the way in which you do issues. Alternatively, you may take a extra bold route, the place you search out a much bigger market, augmenting present or including new merchandise, and whereas that path will ship bigger revenues, you could have to work tougher to get it to ship income and money flows, and maybe have to surrender extra of your possession and management of that enterprise.
The Scaling Alternative
Earlier than beginning on the determinants of scaling, it make ssense to start with the metric being scaled. For many companies, it’s revenues that’s the chosen metric, with scale capturing how huge revenues can grow to be over time. With some earlier-stage companies, a lot of that are pre-revenue, the metric can grow to be a variable that these companies hope to transform to revenues; with tech intermediaries and social media corporations, it may be customers or subscribers.
Specializing in scale, although, there are elements that come into play that permit scaling to have the next probability of success in some companies than others:
Market dimension: It’s simpler to scale up an organization, whether it is small participant in an enormous market, than if if the market is small, and scaling up will rapidly offer you a dominant market share. That mentioned, the way in which you describe your corporation, after which run it, can play a job in how huge a market you’ll have in your merchandise. In my posts on valuing Uber, as an example, I famous that describing it as a logistics firm (automotive service, transferring, supply) relatively than only a automotive service firm might triple its potential market. Market progress: It’s also simpler to scale up an organization if the general market that it’s focusing on can also be rising, since progress doesn’t require going after rivals’ clients. A smartphone firm (Apple or Samsung, as an example) in 2010 had a rising market to work with, as clients switched from flip telephones and smartphones made inroads into giant rising markets. In 2026, that benefit had largely dissipated, because the smartphone market has matured.Business Construction: There’s a pure construction to industries, pushed by economics and enterprise sort, with some industries splintered throughout many gamers, and a few concentrated in just a few huge gamers and even in a winner-take-all. You’ll be able to scale up extra within the latter, however you’ll have to confront the chances favoring you being one of many winners within the trade.Capital depth: It’s simpler to scale up a enterprise that doesn’t require giant capital investments to have the ability to generate extra in revenues. Utilizing Uber for example once more, scaling up was made simpler within the early years, because it didn’t personal the vehicles or rent the drivers that comprised its automotive service, and progress got here rapidly and with little added funding.Buyer inertia: Companies can develop sooner and get greater if there may be much less inertia amongst clients and extra willingness to check out new services or products. On the threat of generalizing, this will clarify why scaling up can occur extra rapidly in youthful industries (like expertise) than in older ones (well being care, schooling).Key particular person(s): There are some companies which might be constructed across the particular ability units of an individual (often a founder or enterprise proprietor) and these ability units should not simply transferred or taught to others. A grasp craftsperson, say a furniture-maker, could have a harder time scaling up that enterprise, as a result of with out having the ability to move his expertise on to his or her apprentices (which might take time and require intense oversight), she or he is constrained in how a lot new enterprise he can tackle. If that craftsperson has a recognizable identify, it’s doable that you could possibly construct a scalable franchise mannequin, as has been tried by some grasp cooks (Wolfgang Puck, Gordon Ramsey and many others.)
The graph beneath captures the scaling decisions that corporations make as a perform of those elements:
As you may see, some companies can scale up rapidly, some take extra time to scale up and a few by no means scale up, and the companies that scale up rapidly usually scale down simply as quick. Thus, the choice of whether or not to scale and the way rapidly to take action is as a lot pushed by the character of the enterprise (capital depth, trade construction, competitors) and the traits of the market that it’s focusing on (dimension and progress, buyer inertia).
Enterprise Constructing
Whereas gaining access to an enormous, rising market can permit you to scale up extra rapidly, your capability to generate income and construct a enterprise will in the end come from different forces:
Unit economics: Unit economics measures the profitability of the marginal unit offered by a enterprise, and is thus decided by the value charged for that unit and what it prices the enterprise to provide that unit. Companies like software program, the place the marginal unit prices little or no to provide and might nonetheless be priced extremely, have superior unit economics and can discover it simpler to transform rising revenues into income, since a lot of the rise in income will stream into income. Conversely, companies like electrical vehicles, the place every extra automotive offered prices cash to make, will wrestle to transform scaled up revenues to income.Economies of scale: Companies with giant fastened prices, whether or not they be related to sustaining platforms and infrastructure, or gross sales and advertising, face obstacles to profitability. Whereas rising can present scaling advantages, that works provided that the fastened prices do not develop with revenues and if they don’t seem to be so onerous, that you simply nonetheless have losses after scaling up. Competitors: & Aggressive Edges (moats): Giant and rising markets present companies with alternatives to develop, however for that progress to translate into sustainable income, these companies will want pricing energy and that energy comes from boundaries to entry that retains new entrants out and offers present gamers benefits.
It’s true that the working decisions that companies make play out on each the scaling and revenue dimensions, typically pitting them in opposition to one another. A choice to decrease product costs could improve revenues on the expense of unit financial income, and a choice to spend extra on promoting and promotion could broaden markets, however the increased advertising prices will impose a drag on profitability.
One option to illustrate the mix of forces that go into enterprise constructing is to to return to fundamentals, and to have a look at what lies below each:
As you may see, scaling up shouldn’t be a mantra that mechanically interprets in profitability, and the pathway to income shall be decided by variables which might be usually out of the management of a enterprise.
Scale & Profitability Mixes
With the multitude of things figuring out each scaling potential and enterprise mannequin viability, it ought to come as no shock that the outcomes that we observe can vary the spectrum, beginning with extraordinary corporations that scale up rapidly, whereas delivering large income, to corporations that by no means scale up, both by alternative or as a result of they might not, and a few of which by no means generate profits.
Lightning in a Bottle: Are scaling and profitability mutually unique? Put in a different way, can an organization scale up, whereas delivering income and maybe optimistic money flows because it grows? The reply is sure, nevertheless it does require a reasonably uncommon mixture of circumstances – an enormous and rising market, being an early entrant into the market with few rivals, low capital depth and wonderful unit economics. There are just a few corporations that meet these circumstances, and we’ll name them “Lightning in a Bottle” companies, partly as a result of they’re uncommon, and partly as a result of success can come from being on the proper place on the proper time. Google and Fb, of their early years, had been good examples, with revenues rising exponentially and profitability in place.Subject of Desires (Shoeless Joe Jackson model): As a baseball fan, I’ve all the time had a delicate spot for the film, Subject of Desires, the place a farmer (Kevin Costner) builds a baseball discipline within the cornfields, and when requested why, responds with “when you construct it, they’ll come”. There are corporations that appear to be constructed round this motto, the place scaling up comes first, usually accompanied by giant losses, however with the promise that “in the event that they construct (revenues), they (the income) will come. Throughout Amazon’s first decade and a half of existence, I described their enterprise mannequin as a Subject of Desires mannequin, and gave credit score for Jeff Bezos for being steadfast in not solely telling this story, but in addition appearing constantly with it, and carrying buyers alongside. (If you’re questioning what Shoeless Joe is doing on this story, I’m afraid you need to watch the film all the way in which to the top.)Subject of Nightmares: Amazon was not the primary profitable Subject of Desires firm, however as one in all its highest profile winners, it gave rise to a legion of younger corporations, all labeling themselves the “subsequent Amazon”. Evidently, Amazon’s success got here from being a disruptor of an enormous enterprise (retail), which had atrophied and weakened over time, and lots of the Amazon wannabes that attempted to mimic it managed to take action on the expansion dimension, with immense quantities of capital invested in scaling up, however by no means turned the nook on profitability, partly as a result of that they had neither the unit economics nor the economies of scale to drag it off.Area of interest Star: Scaling shouldn’t be all the time the optimum alternative, and there are some corporations that acknowledge this actuality early, selecting to remain small and specializing in a portion of the market the place they’ve determined benefits. To that extent that they will convert these benefits into premium pricing and area of interest market dominance, they will have values which might be disproportionately giant relative to their working metrics, i.e., commerce at excessive multiples of revenues and earnings. Ferrari, as an example, sells just a few thousand vehicles yearly, however with an working revenue margin in extra of 20%, it trades at a market capitalization similar to that of auto corporations that promote tons of of 1000’s of vehicles annually.Massive and Damaged: It’s no secret that there are some companies that begin with enterprise fashions with a deadly flaw, i.e,, a damaged enterprise mannequin, and relatively than being shut down, they’re fed rising quantities of capital and allowed to scale up. An actual-estate based mostly enterprise that leases properties long run, after which sub-leases them brief time period, has a length mismatch born in hell, and increasing it geographically and permitting it to lease tons of of properties, as WeWork did, simply makes it a extremely huge, dangerous enterprise. If you’re puzzled as to why buyers would provide capital to those companies, chances are you’ll need to learn on.Small winner & Small losers: If you happen to have a look at all companies, personal and public, most stay small, some resulting from enterprise and trade construction and a few due to proprietor constraints on capital and management. These small companies, although, over time, bifurcate into good small companies, incomes greater than their price of capital and delivering worth, and dangerous ones, incomes lower than the price of capital, however nonetheless price extra as going issues, than liquidated.Minimize your losses: Lastly, there are companies that begin up with goals aplenty, and over time uncover that they will neither scale up, nor generate profits. Within the absence of capital infusions, these companies fail early, but when capital suppliers maintain funneling assets into these corporations, they nonetheless fail, however achieve this later and with a a lot increased price ticket.
Within the matrix beneath, with scaling on one axis and profitability on the opposite, I plot all eight of my scale/revenue mixtures:
Any investor or founder who blindly follows the pathway of scaling first and profiting later for each enterprise is utilizing a cookbook method to enterprise constructing, and runs the chance of creating small failures into huge ones.
The Tradeoff between Scaling and Profitability: Determinants
As you overview the elements that govern the commerce off between scaling and profitability, it’s clear that the appropriate alternative (on how a lot to scale) will rely on the agency, and that not each small agency is destined to grow to be or be extra helpful as a bigger agency, and that not all giant companies have the identical profitability traits, as soon as scaled up. That mentioned, is it doable for companies to undertake scaling pathways that look, at the least from a enterprise standpoint, to be suboptimal? In fact! There are small companies which have viable pathways to scaling up that select to remain small, and on the similar time, there are small companies which might be designed to be small, area of interest companies embark on scaling that’s worth harmful, and the explanations are a mixture of human frailties on the a part of founders, system constraints (from governments and regulators), entry to capital (too little or an excessive amount of) and exit choices (promote, liquidate or go public).
1. Founder Traits
The founder or founders of a enterprise not solely play a key position in guiding the enterprise by its early days, when most start-ups fail, however in addition they make key decisions that may decide in its finish recreation. In making these decisions, they might be guided by the basics we outlined within the final part, that have an effect on scalability, however they’re additionally a perform of their private make-up, on at the least a few dimensions:
Management versus Ambition: There’s a pure rigidity between wanting to manage the levers of decision-making in a enterprise and scaling that enterprise, because the latter nearly all the time requires elevating capital from suppliers who will both constrain your decisions (if borrowed cash is used) or demand a share of possession rights (if fairness). With the latter, founders will discover their management diluted over time, and with sufficient scaling up, it’s doable that founders find yourself with lower than controlling stakes. For some founders, that worry of dilution and dropping energy over their enterprise creations runs deep sufficient to cease them from embarking on progress plans, although these plans make financial and monetary sense.The flip aspect of management is ambition, and for some founders, the need to construct huge companies that aren’t restricted geographically or in product choices can drive the choice to scale up, although the basics could not assist that enlargement. This works provided that they will persuade buyers that their ambitions Actually, this rigidity between a founder’s should be in management and that very same founder’s want to construct huge performs out in what Noam Wasserman referred to as the Founder’s Dilemma, the place to make a enterprise greater, its founder has to step down or at the least compromise on management.Longevity versus Scale: There may be an argument to be made that in case your intent as a founder is to construct a enterprise that’s long-lived, your odds of success enhance when you maintain your corporation smaller and extra centered on what it does properly. Whereas there are various exceptions to this generalized rule, it’s price noting that among the longest lived companies on the planet are household owned small companies, that serve a distinct segment market, and are handed down era to era in the identical household. It’s also true that companies that see a sudden surge in revenues, often as the results of an exterior elements or happenstance, usually reside to remorse their success, as they scale up in a single day. Within the aftermath of the Covid shutdown, as an example, companies like Moderna and Peloton boomed, however in addition they overreached, and did long-term harm to their enterprise fashions.
In abstract, the selection between scaling and profitability will play out in a different way throughout companies, relying upon what founders worth most, thought it’s wholesome for an financial system to a have a mixture of founders, because it creates a mixture of companies.
II. Entry to capital
It’s true that companies want entry to capital, to various levels, to scale up, and the simpler it’s to lift that capital, the simpler it’s to make a enterprise greater. Capital can come from completely different sources, starting from household wealth to enterprise capital to public fairness, with each carrying its pluses and minuses.
Household (or pal) wealth: Each enterprise, by human historical past, having lived by its early days (when failure threat is excessive and its services and products are nonetheless untested) has confronted a alternative of whether or not to remain small, serving a market that it is aware of and understands, or whether or not to get greater, going after a much bigger market. For a lot of that historical past, although, with companies funded with household funds and entry to capital was restricted, most companies selected the primary path and remained small companies, specializing in constructing enterprise fashions that delivered income, with vast variations in success charges. For just a few, owned by wealthier households, entry to a a lot bigger pool of capital (from household financial savings and bankers prepared to lend to those households) created household teams that dominated economies, and proceed to take action in some components of the world. Enterprise capital: The expansion of public fairness markets within the late 1800s and far of the final century did little to alter the household management dynamic, since buyers in these markets had been primarily interested by funding bigger corporations with established enterprise fashions. Recognizing this hole between capital want and capital entry at youthful companies, and the alternatives that the hole introduced, allowed for the rise of enterprise capital within the Fifties, primarily in the US. These enterprise capitalists offered seed capital for start-ups, utilizing winners to cowl their failures, and obtained the majority of their winnings after they exited these investments, both by going public or promoting to a different entity. Over the previous couple of many years, enterprise capital has grown, and within the final 12 years, that progress has not let up: Supply: NCVA 2026 Yearbook
On this century, enterprise capital has additionally grow to be extra world, rising in Asia and Europe, however it’s nonetheless true that it’s simpler for a small enterprise to lift capital to scale up in the US than it’s in a lot of the remainder of the world.
Public fairness: There are some progress companies that bypass enterprise capital and go after public fairness, a a lot greater pool of capital and one that will give founders higher phrases. In some circumstances, this entry to capital is perhaps enabled by going public, even with unformed enterprise fashions and little to indicate when it comes to present operations (revenues or earnings), however in most others, it takes the type of capital invested by bigger, extra mature public corporations in return for a share of possession. These investments could also be labeled as strategic, however the motives for making these investments differ throughout corporations. Some make investments to get entry to a promising expertise or product. some to pre-empt rivals and a few for a similar motive that enterprise capitalists do.
The underside line is that companies that search out capital, whether or not from household, enterprise capital or public fairness, have to simply accept that the capital suppliers will demand and often get a say in enterprise choices, and the extra capital you search, the extra sway they’ll have.
III. Investor Preferences
Companies get their cues on whether or not to scale up or construct enterprise fashions from the buyers who fund them, and far as founders need to map their very own path, investor preferences matter, as do their finish video games. Put merely, a household that invests in a enterprise with no plans for exit will select a really completely different path for that enterprise than a VC that invests in the identical enterprise with the intent of exiting that funding by promoting it to a different investor or firm, or taking it public.
Enterprise capitalists are sometimes considered because the sherpas who guided younger companies to success, each operationally and in markets, the mythology about enterprise capitalists and what they do has additionally constructed up. Since that mythology extends to nearly each side of enterprise capitalist exercise, maybe the easiest way to dispel myths and herald actuality checks is to have a look at what enterprise capitalists are “assumed” to do in every section, and distinction it with what they really do:
If you’re studying this as a critique of enterprise capitalists, you might be misreading it. My intent is to not paint an image of enterprise capitalists as lazy and grasping, however to convey house the fact that given how enterprise capitalists make investments, act and are judged, it’s unrealistic to anticipate them to do the heavy lifting of constructing companies for the long run and to even make enterprise sense, after they discuss corporations.
There are two components of the enterprise capital rulebook that you must concentrate on, to grasp why many VCs prioritize scale over profitability. The primary is that they worth corporations, relatively than worth them, and in a put up from just a few years in the past, I made the argument in additional depth. VC pricing based mostly on what different enterprise capitalists are paying for comparable companies, usually scaled to simplistic metrics, customers and subscribers for pre-revenue corporations and ahead revenues or earnings in what passes for VC valuation:
The second is that VC success is measured based mostly on worth at entry and worth at exit on an funding, relatively than the standard of the enterprise constructed, and utilizing that metric, the median enterprise capitalist has not been significantly better at harvesting alpha than the median mutual fund supervisor or PE investor:
Supply: Cambridge AssociatesThere are, after all, standouts in every of those classes, fund managers who’ve delivered properly above the market, however in mutual funds and to an rising extent, hedge funds, that success is fleeting. There are two facets on delivering returns the place enterprise capital stands out, relative to different energetic investing courses. The primary is that failure, all the time a priority in investing, is way more a component and parcel of investing in enterprise capital than in different investing grouping. Put merely, not solely are there extra VC funds that exit of existence yearly, however even probably the most profitable VC funds lose on many and even many of the investments that they make, particularly in angel financing offers. The second is that enterprise capital investing, when it really works, can generate outsized returns on winners that (hopefully) cowl the price of failures.
You’ll be able to see each of those at play within the graph beneath, which appears at returns that VCs guide after they exit investments:
Supply: CF Non-public Fairness, from Pitchbook knowledge
As you may see, throughout on a regular basis durations, it’s the high 10% of VC investments that ship the majority of returns to VC buyers, and over time, that focus has elevated: within the 2023-2026 interval, 80% of all returns to VC buyers got here from their high 1% of investments. The mix of those two forces (losses on most investments and outsized winners), i.e., the facility regulation in enterprise capital, has two penalties. The primary is that solely a couple of quarter of enterprise capitalists in annually ship above-average returns, making the common VC returns within the desk above extra palatable. The second is that success in enterprise capital, not like in different areas of energetic investing (together with mutual funds, hedge funds and even personal fairness), has been extra enduring. The ability regulation attribute additionally feeds into VC incentives, main enterprise capitalists to direct their capital extra into chasing the largest winners than in constructing companies. Actually, the extra top-heavy VC returns grow to be, i.e., depending on huge payoffs, the extra strain enterprise capitalists really feel (and move on to their portfolio corporations) to seek out the following huge winner, pushing the ecosystem dangerously near playing.
A Altering Recreation
With the dialogue of the size versus profitability on the enterprise stage main in, and the evaluation of the incentives of capital suppliers following, I believe that we’re properly positioned to look at how modifications in private and non-private markets have elevated enterprise incentives to scale, versus constructing enterprise fashions. There are two developments, particularly, which have taken the lean in the direction of scaling in enterprise capital and made it much more pronounced – the entry of public fairness into the funding of personal companies and the fading of reversal, as an antidote to momentum, in public markets.
The Grey Market Impact
For a lot of the final half of the final century, after enterprise capital established a presence in the US, it remained the one or major supply of capital for younger companies. That has modified particularly int the final decade, as public fairness buyers have elevated their investments in younger, personal companies, supplementing enterprise capital in some and even displacing it in others. An early measure of this development is captured within the charts beneath:
Whereas this graph appears at solely the variety of mutual funds investing in personal companies, and stops in 2016, there was a corresponding surge in capital invested by mutual funds in younger, progress corporations, with T.Rowe Value and Constancy investing billions in excessive profile tech corporations like Uber. They had been joined by sovereign funds, who invested closely in these corporations both straight or not directly, by stakes in entities like Softbank’s Imaginative and prescient fund.
We are able to debate the explanations for why we noticed this surge, with worry over lacking out (FOMO) and desirous to partake in tech taking part in roles, however regardless of the causes, capital entry surged for younger corporations, particularly in tech, through the interval. In impact, relatively than two largely separated markets – one for younger, smaller, personal enterprise dominated by VCS and one for bigger corporations extra superior within the life cycle, the place public fairness suppled the funds, a grey market was created the place VC and public fairness fund entry allowed personal companies to remain personal for longer.
Public Markets: Momentum, Fundamentals and Reversals
Public fairness markets have all the time been momentum-driven, permitting merchants who journey that momentum to prosperity, earlier than bringing them down when the momentum shifts. On the similar time, fundamentals act as an anchor, working as a counter to momentum, resulting in reversals and permitting buyers to carry their very own over time. Whereas the congruence shouldn’t be all the time good, scaling feeds into momentum and profitability is probably the most essential elementary, and in markets with stability, when one will get out of sync, the opposite restores concord.
Over the historical past of inventory markets, worth buyers have usually claimed dominance, and pointed to the returns you could possibly have earned by shopping for corporations that look low cost on a price foundation (low worth earnings or low worth to guide) and ready for worth reversals. Merchants push again by noting that over the identical historical past, momentum has had a decisive impact on returns, particularly over shorter time intervals. Whereas the momentum impact exhibits up throughout the many years, there may be proof that the reversal impact has weakened over time, leaving buyers who wager on imply reversion and a return to fundamentals within the lurch:
Supply: Ken French’s datasets
The explanations given for this shift differ, and are sometimes reflective of the biases of the buyers giving the explanations.
The Fed did it: For many who view central banks as omnipotent, and consider that the low rates of interest of the final decade had been their doing, these low charges have additionally grow to be the proximate motive for market pricing habits and reckless threat taking. Their argument is that rates of interest which might be near zero induce buyers to shift from bonds to shares, and inside shares, to maneuver from low progress, excessive earnings shares to high-growth corporations with little or destructive earnings.The rise of passive investing: Within the battle between energetic investing and passive investing, with ETFs supplementing index funds, the latter has had a decisive edge when it comes to returns over the past twenty years, and its share of the market now stands are properly above 50%. There are some who argue that the stream of funds to passive investing autos has contributed to the elevated energy of momentum, since extra new funds stream to the most important market cap corporations than to the smaller ones. As well as, it’s argued because the variety of energetic investing declines, there are fewer buyers taking a look at enterprise fashions and profitability, lowering the pull of fundamentals on worth.Public market composition: It’s noteworthy that the reversal impact began weakening within the Nineteen Nineties, a decade when younger dot.com corporations with unformed enterprise fashions flooded the market, bypassing the extra conventional route of utilizing enterprise capital to develop. With these corporations, the place worth is nearly totally pushed by potential and never by working metrics right this moment, the catalysts wanted for reversal could take longer to manifest.Info sources and entry: It’s simple that buyers and merchants get data from a wider ranges of sources now than two or three many years in the past, with social media and on-line sources supplying data that used to come back from newspapers and monetary information channels. In extra to being much less curated and managed, that data can also be instantaneously accessible to the general public, and worth reactions are inclined to observe.
Whereas I take situation with components of every of those arguments, there may be some reality to all of them, and so they have contributed to creating pushing again in opposition to momentum a extra hazardous train for buyers.
The Penalties
With bigger quantities of capital being deployed by VCs at younger, progress corporations, substantial capital infusions from public fairness funds into personal capital markets, and public fairness markets which might be extra used to and receptive to younger firm listings, it shouldn’t be stunning that it’s altering how personal corporations behave. Within the graph beneath, I have a look at the traits of corporations going public in the US, utilizing the info that’s generously made accessible by Jay Ritter:
Supply: Jay Ritter’s IPO knowledge
There are three clear modifications over time which might be seen on this graph:
1. Non-public companies are ready longer earlier than going public: As you may see, the common age of an organization going public has risen over time, with the median age rising about 11 years within the final 15 years.
2. Non-public companies are scaling up (revenues) extra, whereas ready: Whereas personal companies wait longer to go public, they’re spending that point scaling up greater than they used to. The inflation-adjusted revenues on the median IPO have tripled and even quadrupled, relative to IPOs within the Nineteen Eighties.
3. Non-public companies are deferring constructing enterprise fashions & profitability: Probably the most putting characteristic of the info, to me, is that whereas personal companies are ready longer and scaling up extra earlier than going public, in addition they appear to be deferring enterprise constructing for for much longer as properly. Whereas it was routine for corporations going public within the Nineteen Eighties to be worthwhile (>80% had been), much less {that a} quarter of the businesses which have gone public within the final decade have been worthwhile.
Whereas corporations which might be going public are greater (in income phrases) and fewer more likely to be worthwhile, markets are attaching giant market capitalizations to those newly minted corporations, as you may see on this graph which zeros in on tech IPOs:
Supply: Jay Ritter’s IPO knowledge
Additionally, you will discover that corporations going public are issuing smaller parts of their shares to the general public, at the least within the preliminary providing, suggesting that the necessity for capital that drove corporations to go public has grow to be much less urgent over time, maybe due to extra capital entry as personal companies. Whereas the median market cap of an organization going public within the final six years has exceeded a billion, the most important IPOs command market capitalizations that might have been unimaginable just a few many years in the past. From Fb, with a pricing of $104 billion, in 2012 to SpaceX, going public in June 2026 at $1.8 trillion, the development traces are pointing upwards, particularly if Anthropic and OpenAI ship on their trillion-dollar plus pricing promise.
Implications
By itself, the development in the direction of personal corporations scaling up extra, whereas public, and going public at eye-popping market capitalizations could also be comprehensible and explainable, however there are implications that we have to contemplate each from an investing and governance standpoint.
Company governance: One of many causes that personal corporations usually delay going public is as a result of governance necessities, from board composition to high administration compensation, are extra stringent at public than personal companies. Whereas Sarbanes-Oxley, which wrote into regulation lots of the present governance guidelines for public corporations, is commonly toothless and ineffective, it nonetheless forces disclosures about governance (on conflicts of curiosity and board member relationships) at public corporations. As well as, public market buyers can strain public corporations to alter governance practices or high administration, if corporations underperform available in the market place. One of many perils of letting corporations scale up extra earlier than these governance questions get raised is that the highest administration in these corporations could have few checks on their actions. It’s true that enterprise capitalists might function as a disciplinary mechanism, however in an age of founder worship and the place VCs may be divided and conquered, you may have corporations with market pricing of a billion, tons of of billions and even trillions run by people who find themselves ill-suited for the duty.Delayed enterprise mannequin constructing: If the primary crucial for a non-public enterprise is to scale up, as a result of scaling pushed up pricing each in personal and public markets, the problem of enterprise constructing will get deferred to a later stage. The issue with scaling up first, and constructing a enterprise mannequin later, is that it could be too late, because the decisions made to permit for scaling up could impede the pathway to profitability. Once more, in case your response is that VCs will work on fixing this downside, they’ve little incentive to take action, since they profit from scaling up and exiting these companies, earlier than the enterprise issues grow to be too huge to disregard. Scaling tales: If you happen to consider, as I do, that valuation is a bridge between tales and numbers, and that the stability between the 2 shifts over the life cycle, with tales dominating early within the life cycle and the numbers taking heart stage within the later phases, it’s comprehensible that VCs and founders, when advertising their corporations are primarily story tellers. I haven’t got an issue with that, however as I famous in my final put up on AI as a enterprise, the tales which might be being informed for these corporations are sometimes incomplete, and nearly totally centered on the scaling query. Thus, within the Anthropic gross sales pitch it’s the progress within the annualized income run price (ARR) and the scale of the AI market (large, however with no specifics) that includes the majority of the story, with little or no point out of enterprise fashions or profitability.Disruption with out substitute: Disruption has been a key element of the tales that underlie lots of the largest corporations which have gone public on this century. Accepting the premise {that a} wholesome financial system wants a shaking up of the established order, and that disruption can result in financial progress and higher practices, it’s nonetheless official to have a look at disruption’s particles. One of many perils of supplying capital in nearly infinite portions to non-public companies that purpose to disrupt, with out difficult them on enterprise fashions, is that you could be succeed at disrupting the established order (driving present gamers out of enterprise) however your disruptor could not be capable of construct a enterprise that may be self-sustaining in the long run.
Conclusion
I’m certain that you’re already conscious of the core message of this put up, which is that however the present emphasis on scaling up companies, not all companies are supposed to scale up, and that scaling up comes with challenges that founders could also be ill-equipped to satisfy. That mentioned, bold founders will really feel the urge to make their companies greater, and in the event that they increase capital (from enterprise capitalists) to make this occur, the incentives to scale up will improve, even when it makes little or no enterprise sense to take action, with all events hoping to exit by promoting to others (public or personal) who will worth based mostly on scale. Whereas this has all the time been the case, modifications in personal and public capital markets have tilted the size even additional in favor of scaling, and it’s doable that corporations, each private and non-private, with sky-high pricing have been constructed on dangerous enterprise fashions which might be irredeemable.
YouTube Video
Weblog posts on Enterprise Capital and Scaling
Blood within the Shark Tank: Pre-money, Submit-money and Play-money Valuations (February 2015)Billion-dollar Tech Infants: A Blessing of Unicorns or a Parcel of Hogs (June 2015)Enterprise Capital: It’s a pricing, not a price recreation! (October 2016)Danger Capital in Markets: A Short-term Retreat or a Lengthy-term Pullback (July 2022)