Which is best? A Roth or conventional IRA? Preserve your reply in thoughts as a result of we’ll get again to your reply in a bit. Oh, and over 95% of individuals get the reply improper so put together for a watch opening expertise.
There are two camps in terms of retirement planning. Some insist the Roth is best on account of all that great tax-free progress. Others say conventional retirement accounts are higher as a result of you’ll be able to make investments all that cash from the tax deduction. So, is the tax-free progress of a Roth higher? Or the tax deduction from the normal IRA?
Let’s do some math. (I’ll do the heavy lifting, however should you suppose I’m enjoying it quick and unfastened with the quantity you might be welcome to confirm my work. In truth, I insist!)
First, we have to guarantee we’re evaluating apples-to-apples.
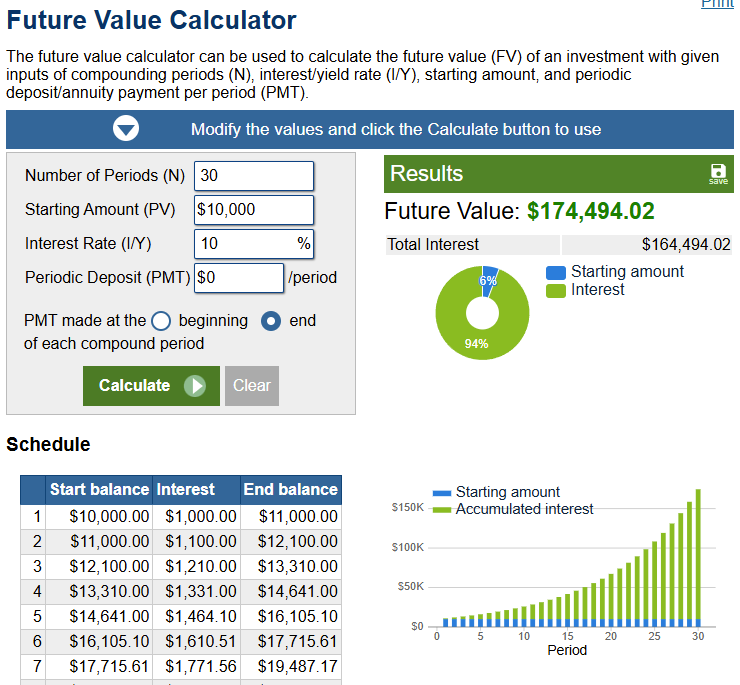
In our illustration we now have $10,000 to speculate right into a retirement account. We are going to then let the funding develop for 30 years at an annual progress price of 10%.
Since our instance solely has $10,000 we are able to’t stack the deck by dropping $10,000 right into a Roth with out contemplating the taxes that can be paid on that $10,000.
Lastly, we’ll assume a 20% tax bracket for our hypothetical particular person. (Sure, I do know there isn’t any 20% tax bracket and that you may’t drop $10,000 into an IRA in a single yr (but). We’re utilizing the great spherical numbers as illustration solely. You possibly can develop the maths as a lot as you need as a result of it would give the very same reply each time!)
Right here is the Roth future worth printout. Taxes claimed $2,000 with the remaining $8,000 going to work. No worries. All that progress is excluded from taxable revenue! In 30 years you may have $139,595.22. Not dangerous.
The long run worth of $10,000 invested in a Roth IRA after 30 years at a ten% annual return. Bear in mind, you needed to pay tax on the $10,000 since there isn’t any deduction. Subsequently, you solely make investments $8,000, assuming a 20% tax price.
Now we now have the normal, and deductible, IRA. The complete $10,000 goes to work as a result of the $10,000 invested is deducted from revenue. Nevertheless, when the day of reconning arrives all of the distributions are taxable.
The long run worth of a $10,000 funding in a conventional IRA in 30 years with a ten% annual price of return.
Properly, it seems like the normal IRA with deductible contributions has $174,494.02 in 30 years whereas the poor Roth investor has a mere $139,595.22. Conventional wins.
WAIT! The normal IRA has to pay tax on these distributions. So we’ll assume a whole distribution from the Roth and conventional IRA accounts, only for illustration.
We are going to assume tax charges haven’t modified in retirement for our instance particular person. The normal IRA will face a 20% tax on distributions. It seems like this:
$174,494.02 – $34,898.80 (20%) = $139,595.22
WHAT!!!
If the tax price doesn’t change the Roth and conventional are precisely the identical? It is just timing once you pay the tax? Get out of right here!
However it’s true. On the finish of the day the Roth and conventional IRA are precisely the identical when all parameters are unchanged. It could possibly even be argued that investing in a conventional IRA is a guess in your tax bracket being decrease sooner or later. Type of like day buying and selling. And we all know how that goes.
In a vacuum, with out another concerns, the Roth and conventional IRA are the identical.
In a vacuum. And the actual world shouldn’t be so neat and clear.
Roth vs Conventional IRA Within the Actual World
If taxes have been easy and simple our above instance can be advantageous. And as we’ll see shortly, taxes don’t go down as a lot as you suppose in retirement and might really go up. That places the normal IRA at a drawback.
Then there are the benefits of having a decrease revenue (as a result of conventional IRA contribution) throughout your earnings years. You may get a Saver’s Credit score or different credit.
Let’s assessment parameters that may change the reply to our authentic query.
Contributing to an IRA
Roth IRA
The Roth IRA is a straightforward product. You get no deduction entering into.
Conventional IRA
Contributions to a conventional IRA may be both deductible or non-deductible. Since we aren’t evaluating the non-deductible conventional IRA we is not going to say extra about it than that it’s the least useful retirement plan possibility except backdoor Roth methods.
Deducting retirement plan contributions offers you the flexibility to govern your tax return for optimum effectivity.
The Saver’s Credit score applies to each Roth and conventional IRA contributions. And the Earned Revenue Credit score shouldn’t be modified by making an IRA or different retirement plan contribution.
The Premium Tax Credit score is one other story. In case you have medical insurance from the healthcare.gov website you may have the chance to make use of the Premium Tax Credit score. You need to use this calculator to see how a lot of a credit score you’ll be able to get pleasure from.
A deduction for a conventional IRA contribution may push extra of your long-term capital beneficial properties and certified dividends into the 0% tax bracket.
The listing of potential benefits to an up entrance deduction for IRA contributions is lengthy. From lesser recognized tax methods like tax-gain harvesting to the Premium Tax Credit score, present deductions can save severe cash.
Distributions From an IRA
Roth IRA
Whereas the Roth IRA is easy in idea, placing cash in and taking cash out with out tax penalties, a number of the biggest worth the Roth has to supply is above and past a easy tax break at your present stage tax bracket.
In contrast to the normal IRA, the Roth IRA doesn’t have required minimal distributions. You can even take a distribution of your contributions at any age with out tax or penalty when you meet the 5-year holding interval that begins from the day of your first ever Roth contribution. (Because of this you wish to begin a Roth as early as potential.)
Roth distributions don’t add to your revenue. That appears straight ahead at first, however the penalties are even greater than imagined.
Suppose you wish to make a big buy as you enter retirement, for an RV, for example. You want $300,000 (you count on luxurious in your retirement) for the RV. If the funds come from a Roth there aren’t any tax penalties, however, as we’ll see shortly, if the funds come from a conventional IRA not solely will your taxes be greater, however extra of your Social Safety advantages may get clawed into taxable revenue in your federal return and your Medicare premiums could also be greater for a yr.
Whereas the Roth is easy in idea, the Roth can do greater than decrease your taxes. That turns into a problem when stacked towards the normal IRA.
Conventional IRA
On the open of this text we in contrast the Roth and conventional IRA. In case your tax bracket stays static the tip result’s a tie. However there are extra issues to think about than taxes.
As famous within the Roth part above, Medicare premiums when you attain age 65 turn into a priority. Medicare premiums usually are not a tax, however they’re nonetheless cash out of pocket. In my view, we have to take into account all advantages and all prices when evaluating the Roth with the Conventional IRA.
For 2025, most individuals on Medicare, Half B pays $185.00 per 30 days, or $2,220 for the total yr. This premium is per particular person. Each pay the premium in a wedding as soon as each attain Medicare age. The $185 per 30 days most individuals pay in Medicare premiums can climb to $628.90 per 30 days (and per particular person for married {couples}). This provides as much as $7,546.80 in 2025. A married couple each on Medicare get to double this to $15,093.60.
In my workplace I spend severe time with retirees optimizing how a lot they’ll withdraw from their conventional IRA with out clawing extra Social Safety advantages into revenue and avoiding a bump in Medicare premiums. Conventional IRA distributions add to revenue. This could push extra Social Safety advantages into the Taxable Quantity column. Mixed, this will push you into a better tax bracket for a few of your revenue.
Now that we acquired the dangerous information out of the way in which I need you to pay attention to one huge profit conventional IRAs have over the Roth, the Certified Charitable Deduction (QCD).
The QCD works like this: when you attain 70½ you’ll be able to have as much as as much as $108,000 (for 2025) despatched on to the charity of your selection. QCD distributions are excluded from revenue with out itemizing. It is a very highly effective device for taxpayers that have a tendency to provide extra to charity. The QCD additionally satisfies the required minimal distribution requirement (RMD) too. In different phrases, in case your RMD is $22,500 for 2025 and you might be 70½ or older and have your conventional IRA ship $10,000 on to your church, you solely must withdraw $12,500 extra to fulfill your 2025 RMD. The overall distributions meet the RMD stage of $22,500. The Roth IRA can do the identical, however the conventional IRA had a deduction entering into.
Your retirement plan decisions will have an effect on your high quality of life in retirement. Select properly.
Roth vs Conventional IRA (Which Is Higher?)
A easy, one dimension suits everybody reply, shouldn’t be out there. What works for one might not work for one more. Your details and circumstances will decide your plan of action.
The Roth, in its simplicity, appears to be the default selection. However that doesn’t imply it’s best to take the simple method out and simply go together with the Roth. Laziness will value you. Present deductions can save severe cash, particularly should you get a bigger Premium Tax Credit score.
The decrease your tax bracket in your incomes years the better it’s to make use of the Roth. You already qualify for many credit and deductions with out extra coming off the highest. Additionally, the decrease your tax bracket the yr you contribute to your IRA the extra doubtless you’ll have a better tax price once you take a distribution. (Bear in mind, conventional IRA distributions improve your revenue. That may end up in a better tax bracket.)
If you’re in a excessive tax bracket, contributions to a conventional deductible IRA (if allowed) is usually a more sensible choice because it turns into extra doubtless your high tax bracket in retirement can be decrease for the reason that bar is so excessive going into the IRA. That is the place I remind you that you may additionally contribute to your retirement plan at work. IRA and 401(ok) guidelines differ so I attempted to stick with the IRA on this article. Bear in mind, your work retirement plan in all probability will get transferred to an IRA once you retire.
The Rich Accountant’s Resolution
If the reply shouldn’t be clear, what’s the reply, based on The Rich Accountant?
Personally, I bifurcate my retirement plan investments. I put some into the Roth and a few into the normal. Every year I assessment my tax scenario to find out what proportion goes into every to maximise my tax advantages.
I’ll not hit the proper candy spot. However I can be nearer to the actual world optimum with my method.
If I want a big chunk of cash early in my retirement I can faucet my Roth. I additionally are likely to contribute closely to charitable organizations. Once I hit 70½ I’ll make full use of the QCD. As soon as RMDs kick within the QCD will fulfill that requirement. And I don’t must itemize. I get the total customary deduction plus the flexibility to fund charities of my selection with out making a taxable occasion.
In different phrases, I set my scenario to have one of the best of each worlds. I depart room for decisions and when I’ve decisions I can extra simply maintain my tax burden low.
One final level to debate earlier than I am going. Your beneficiaries may have a really totally different expertise when inheriting a Roth or conventional IRA. Roth IRA beneficiaries do have RMDs, however the distribution shouldn’t be included in revenue. Inherited conventional IRAs usually require RMDs with full liquidation by the tip of the tenth yr. A partner and minor kids have totally different guidelines.
The important thing takeaway is that it’s essential to assessment your private tax and monetary scenario yearly to make your best option for you. What I do is irrelevant to what’s finest for you. It is advisable to uncover what’s finest for you. After which do it.