Earlier this yr, I used to be requested what I thought of Leopold Aschenbrenner and I admitted that I knew little about him apart from what I had examine him, extra in social media, than within the press – that he was a 25-year-old wunderkind who had began at OpenAI however had left to start out a hedge fund. That hedge fund, constructed completely round a wager that AI would repay massive time and close to time period, shopping for corporations within the AI orbit and promoting quick on the companies (particularly software program) that AI would disrupt, had been capable of elevate billions of {dollars} from well-heeled and presumably subtle traders, and had posted eye-popping returns, up virtually 450% by means of late June. Success of that magnitude wants no nitpicking, however it’s price remembering that there’s nothing that markets get pleasure from greater than reducing inflated egos and reputations right down to measurement. On this case, the autumn from grace was precipitous, and over the course of 4 weeks, the fund’s public fairness holdings misplaced greater than two thirds of its worth, however was additionally compelled to liquidate, with Citadel shopping for virtually all of its public fairness holdings.
The reads on the swift rise and fall of Leo have been fascinating, a Rorschach check of investing priors. For older traders, the lesson was which you can be blessed with intelligence, however that knowledge required expertise, which, not less than of their saying, conveniently comes with age. For worth traders, a lot of whom chafed at Leo being hailed as the following Buffett, there was vindication that there’ll by no means be one other Buffett. For AI skeptics, who’ve lengthy been looking out for catalysts that can break AI fever, there was not less than a short second of hope that this was the catalyst. There’s some fact and a few overreach in every of those responses, and I do not plan to rehash them. As an alternative, I want to use this story to speak about investing conviction, phrases used largely in a good approach, when individuals speak about success in markets. I’m not as satisfied that investing conviction is a web plus, however to get to that conclusion, I believe we have to take a look at what it’s, the place it comes from and what it leads traders to do.
The Story of Situational Consciousness
The Situational Consciousness story is inextricably tied to the story of Leopold (Leo) Aschenbrenner. The quick model of his life story is that he was born in Germany in 2001, and enrolled at Columbia College when he was 15. After graduating with a level in economics in 2021, doing analysis briefly at Oxford College and dealing at Sam Bankman-Fried’s FTX fund, Leo joined OpenAI as a part of the workforce engaged on AI security. He was fired in 2024 for leaking knowledge on the agency, although his motivations for doing so are murky and he contests the allegation, and he revealed an extended (167 web page) paper titled “Situational Consciousness: The Decade Forward”, which was not solely broadly circulated, but additionally grew to become the blueprint for the fund that he created.
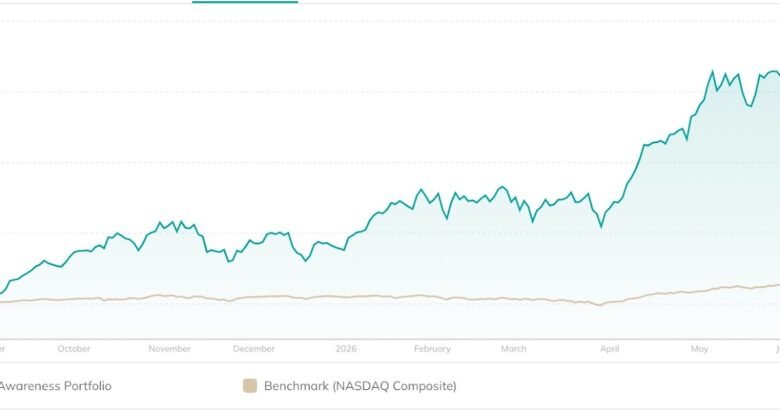
The Situational Consciousness fund, based in July 2024, and initially funded by tech luminaries, shortly took off as its bets on AI chips and infrastructure and in opposition to AI-damaged sectors paid off. Its early success allowed it to draw more cash, with Jane Road being one of many extra outstanding names concerned., and with the extra capital in play, it expanded its presence. Whereas a lot of the corporations that made the fund’s listing had been publicly traded, it additionally had a stake that Leo had acquired in Anthropic, nonetheless a personal enterprise. The numbers posted by the fund made traders discover, as might be seen by its rise From August 7, 2025, to June 23, 2026, its highest mark day:
Measuring returns from August 7, 2025, Situational Consciousness was up about 367% by means of June 19, 2026 and its returns since founding are much more stratospheric. Even at its peak, there have been three caveats that any investor with expertise out there would (or ought to) have introduced up. First, in market time, the place many years of over efficiency are wanted to separate luck than ability, a fund that has been profitable for a bit greater than two years qualifies extra as a capturing star than as a beacon of sunshine. Second, to ship returns of this magnitude, you not solely should be proper in your guesses, however these guesses have to be super-charged by including substantial leverage to your technique, both explicitly (by borrowing) or implicitly (through the use of choices). Third, the fund adopted the traditional 2% (of funds below administration) and 20 (% of specified upside) payment construction, an abomination that not solely creates an virtually insurmountable handicap, in the long run, for traders within the fund, but additionally encourages reckless threat taking up the a part of administration.
If the rise of the fund was breathtaking, its fall was much more so, and you’ll see the meltdown within the 4 weeks of July within the graph beneath, which appears on the fund efficiency from June 19, 2026 to July 29, 2026, the final day of buying and selling for the day, earlier than the fund was liquidated:
Observe that the lack of principal (of greater than 43%), with the Anthropic holding worth retaining largely intact, as a personal holding, however with the general public funding portion of the portfolio down by virtually 67%. I’m positive that there shall be case research and forensic evaluation of what occurred in these weeks, however for me, the lesson is considered one of market symmetry. What the market provides simply, it additionally takes away simply as simply, and should you put into place methods which can be designed to ship outsized returns, you must stay with the truth which you can have outsized losses. The shock, although, for a lot of just isn’t that the fund misplaced cash in July, however that it didn’t survive the month, and was compelled to promote a lot of its public funding portfolio to Citadel, at costs, that not less than in hindsight, seem like discount basement ranges.
Conviction: What’s it and the place does it come from?
How do I get from the Situational Consciousness story to a dialogue of funding convictions? Easy! Leo’s core perception that AI would win the battle with the established order in most companies, and that the win can be decisive and fast, was not distinctive, and never solely are there different traders who shared that view, however there are additionally corporations which can be investing in AI cap ex, pushed by that view. That mentioned, to get from that view to a hedge fund constructed completely round shopping for AI winners and promoting AI losers requires that the idea to be deeply set and utilizing debt to enlarge these returns suggests sturdy conviction.
What’s funding conviction?
Earlier than we embark on a dialogue of funding conviction, it’s worthwhile to start out with an understanding of what it means. Whereas there a myriad of definitions on the market, the final consensus is that funding conviction measures the idea that an funding alternative will generate important returns, relative its dangers, and with that definition, you may see that conviction is a continuum, quite than an absolute.
At one finish of the spectrum, you’ve got absolute conviction, the place you realize (or assume you realize) with certainty that an funding will repay. On the different finish of the spectrum is funding mush, the place your emotions about an funding paying off are so weak that you’re unwilling to even voice that opinion, not to mention put cash behind it. With most investments, you fall within the center, with the variations being within the diploma of confidence that you’ve in being proper.
As you may see, the elevation of conviction as one thing to be wanted in investing is as a result of within the full absence of conviction, you’ll not act and that paralysis can lead to portfolios completely or virtually completely held as money. I do not assume, although, that even the strongest proponents of conviction as a very good high quality in investing would make the argument that you need to really feel sure in regards to the consequence of investments, when uncertainty is an element and parcel of investing.
The place does conviction come from?
So, what’s it that determines funding conviction or the dearth of it? To generate a foundation for that dialogue, let’s return to fundamentals, and begin with an evaluation of what has to occur for an funding to be seen as a cash maker. It doesn’t matter what your funding philosophy, the method begins with a market value for an funding, and an evaluation of what you imagine is a “truthful value” for that very same funding. I’m being agnostic about the way you arrive on the truthful value, leaving the door open for chartists, who could discover it by taking a look at previous value patterns, fundamentalists, who imagine which you can assess truthful value, solely by wanting on the fundamentals of the funding and merchants, who could also be in possession of data that leads them to imagine that the present value is mistaken. For the method to ship winnings, although, there’s a second half to the method that usually will get much less consideration, which is that the market has to appropriate, with the market value transferring in direction of and even to your truthful value.
To have conviction in an funding, you subsequently must imagine strongly in three points of this course of:
That your evaluation of “truthful” value is true (or not less than extra proper than the market consensus) That the market will appropriate, i.e., that the market value will transfer to, or in direction of, your truthful priceThat this correction will occur through the time you intend to carry the funding (your time horizon), both as a result of the funding has an expiration date (maturity) or since you really feel that there shall be a catalyst that causes the correction.With this description in place, you may see that funding conviction will rely upon the funding in query, the market that it’s priced in and on the investor making the judgment.
a. Funding Mispricing
If the funding course of begins with an evaluation of a good value that’s completely different from the market value, there are not less than 4 the reason why you could be extra assured in your evaluation of the value of an funding, relative to the market consensus:
Non-public info: On the threat of treading on or crossing the road between the authorized and the unlawful, you could be in possession of details about an funding that isn’t out there (or not less than broadly sufficient out there to the general public to be priced in) that you simply imagine will change its value.Data processing: To the extent that non-public info isn’t out there to traders, and even when out there, troublesome to behave on legally, a lot of energetic investing is constructed round amassing and processing info that’s out there to the market. That personal info can vary from previous costs and buying and selling quantity (utilized by technical analysts) to public filings (the monetary knowledge that the corporate gives, usually the premise for basic traders) to quasi-public info (analyst forecasts and revisions, hedge fund and mutual fund holdings). In case you are utilizing this info to evaluate a good value, it’s since you imagine that you’ve discovered patterns within the knowledge that others haven’t.Enterprise understanding: In some instances, your truthful value will derive out of your perception that you simply perceive the enterprise economics for a corporation higher than different public traders do, together with your superior understanding coming both from working within the enterprise or from technical coaching. That is very true in complicated companies (like bio pharma) and sophisticated belongings, and prone to be extra the case with younger corporations, the place monetary historical past can stand in for enterprise understanding.Pricing mistake: There are some funding theses that begin with a market mistake, whether or not it’s in pricing a person asset or a pair of belongings. With a pair of belongings, usually with comparable fundamentals, the mispricing manifests with one of many belongings being mispriced in opposition to the opposite, and the correction happen when the mispricing disappears. It’s on the coronary heart of derivatives buying and selling, the place choices or futures on a traded asset might be mispriced sufficient which you can lock within the earnings from the pricing mistake, with the assure of correction, when the choice or futures expire.
In sum, you may see that the diploma of funding conviction that an investor has can range throughout completely different asset markets (actual property, equities, fastened revenue, derivatives), geographies (developed versus rising markets) and inside equities, throughout business teams and sectors (much less for know-how and extra for utilities, for instance).
b. Market correction
Funding conviction could begin with the recognizing of a market pricing mistake, however for conviction to construct, you could get a measure of when, why and the way the market will appropriate its mistaket. Listed here are a few of the forces that may trigger variations available on the market correction dimension:
Finite maturity versus indeterminate finish recreation: An funding with a finite maturity date comes with a larger probability that costs will appropriate than one with out. A bond that’s mispriced, by itself, or in opposition to different bonds of equal maturity, comes with a larger probability of correction than a inventory that’s mispriced in opposition to its personal fundamentals or a paired inventory. For a similar causes, should you can lock in a mispriced choice in opposition to its underlying asset (or inventory) or in opposition to different choices of equal maturity, you might be transferring the percentages in favor of correction. It ought to come as no shock that true arbitrage, i.e., positions that may lock in assured earnings that exceed the riskfree price are virtually all the time within the fastened revenue or derivatives markets and that a lot of what passes for arbitrage in equities is quasi or pseudo arbitrage, the place threat stays within the place.Market frictions: Market mispricing can generally replicate market inattention or irrational buying and selling, however they extra usually are the consequence of market frictions, together with restrictions on promoting quick and exerting management over an funding (resembling shopping for and liquidating an organization). If that’s the case, it’s potential that market errors, whereas seen and seeming apparent to everybody concerned, could by no means get corrected, or not less than not get corrected till the friction is eliminated.Market liquidity and depth: In fairness markets, the place there is no such thing as a date by which mispricing has to vanish, corrections usually require catalysts, i.e., occasions that lead market members to reassess a market value, and to appropriate it. These catalysts can come from company disclosures (earnings reviews, as an illustration) by the mispriced firm, company restructuring (divestitures and spin offs) or excessive profile traders (activists taking a stake in a below priced firm or promoting quick an overpriced one). All of those catalysts usually tend to be current in liquid and deep markets, the place info flows are extra frequent and various.Funding time horizon: It doesn’t matter what the market mistake, it may be argued that having time as an ally, and having the ability to look forward to longer intervals, for market corrections, mustn’t solely offer you a larger probability of gaining from a market correction, but additionally offer you extra conviction in your funding, different issues being equal.
The underside line is which you can really feel (comparatively) sure that an funding is mispriced, however haven’t any conviction in that funding, when you have no sense or religion that the market will appropriate in your timeframe for investing.
c. Investor traits
Is it potential for 2 traders to seek out the identical market mistake, with the identical underlying rationale for the mispricing, and have completely different levels of conviction in following by means of? Completely, and whereas a part of the reason being differing time horizons, there are different investor-specific forces that additionally come into play:
Intelligence and academic background: This can be a generalization, and should you disagree, you need to take exception, however the smarter an investor is, and the extra distinctive his or her instructional background (the appropriate colleges, credentials and certification), the larger the conviction that investor is prone to convey to investments. One purpose is that it turns into simpler to attribute perceived market errors to the dearth of intelligence of different market members than it’s to take a better take a look at actual the reason why they might not be errors within the first place.Persona: Like conviction, self-worth falls on a spectrum with broad variations throughout human beings. Some traders measure low on the self-worth scale, and look to others for large selections. Others measure greater on the self-confidence scale and are keen to make selections with incomplete info and within the face of uncertainty and disagreement. Nonetheless others have a lot self-worth and so little self doubt that they threat having convictions which can be out of sync with actuality. Over 5 many years of analysis in behavioral finance has highlighted overconfidence as one of many key drivers of irrational investor habits, and underscored the truth that not solely does this trait range broadly amongst people, but additionally that essentially the most overconfident gamers usually rise to the highest of the funding and company world. Within the conviction dialogue, overconfidence enters the sport early and is maybe the most effective explainer of why some traders, taking a look at what they assume is a market mistake, really feel a lot extra satisfied that they’re proper than different traders taking a look at precisely the identical mistake.Monitor document: Whenever you make investments, you obtain virtually instantaneous and steady suggestions on whether or not your investments are paying off, and whereas funding success is all the time preferable to failure, it’s plain that a few of the worst funding classes are realized from that success. A lot as Wall Road likes its adages of “not mistaking dumb luck for ability”, traders are fast to overlook them when an funding wager that they make pays off, particularly when their success results in iconic and admiring profiles (“the following Buffett”) and investor capital pouring in.
You’ll discover that I do not listing age as an extra attribute, however that’s as a result of I do not equate growing old with knowledge or temperance. It’s true that growing old normally muddies your funding monitor document, and that there is no such thing as a higher certain on over confidence than dropping a lot of cash on what you thought was a positive wager.
The Penalties of Conviction
At this level within the submit, I do not blame you for questioning why conviction is such an enormous deal, since shopping for Palantir or SpaceX with low conviction counts simply as a lot shopping for shares in these corporations with excessive conviction. Conviction issues in investing as a result of it impacts two selections that traders make – the sizing of positions (with extra conviction resulting in bigger positions in the identical funding) and the usage of monetary leverage (with extra conviction usually translating right into a willingness to borrow more cash to fund the funding).
Focus
One of many basic questions in investing, and one which evokes sturdy disagreement, is how a lot, if in any respect, traders ought to unfold their bets. The controversy is an outdated one and there are lots of views that fall between two extremes. At one finish is the recommendation that you simply get from a believer in environment friendly markets: be maximally diversified, throughout asset courses, and inside every asset class, throughout as many belongings you may maintain. The proverbial “market portfolio” contains each traded asset out there, held in proportion to its market worth. On the different is the “go all in” investor, who believes that should you discover a considerably undervalued firm, you need to put all or most of your cash in that firm, quite than dilute your upside potential by spreading your bets. The dialogue of funding conviction ties into the reply to this query.
I’m not an absolutist on this entrance, as a result of what you do as an investor ought to replicate your circumstances. At one restrict, if you’re sure about your evaluation of worth for an asset and that the market value will modify to that worth inside your time horizon, you need to put your whole cash in that funding. This may increasingly appear to be an unattainable dream, however it it’s what you hope to drag off should you discover mispricing within the bond or derivatives markets (true arbitrage), the place you may lock within the mispricing, with a assured value correction at maturity (of the bond or choices). On the different restrict, when you have doubts aplenty and no conviction in your funding selections, you need to be as diversified as you may get, given transactions prices. In case you have no transactions prices, you need to personal a bit piece of every part, a really actual alternative in a world of index funds and ETFs. In any case, you acquire nothing by holding again on diversification and your portfolio shall be ship much less return per unit of threat taken. In case you are energetic investor who is consistently on this place (of getting no conviction), it’s best to retire the “energetic” a part of your funding profile and go all in on index funds.
For many energetic traders then, the query of how a lot to diversify will rely largely on how sturdy or weak their funding conviction is, and that, in flip, depends upon what investments these traders are targeted upon. On this context, I might argue that the correct quantity of conviction and by extension focus (or diversification) will rely on the sorts of corporations you spend money on (with extra diversification wanted while you spend money on youthful corporations) and your time horizon (with focus growing with time horizon)
Leverage
Monetary leverage is an instrument that traders can use to boost returns, however its use in investing has all the time been controversial. Whereas borrowing cash to fund an funding will enhance upside, if you’re proper, it would additionally enlarge draw back, and in some instances, precipitate collapse, if you’re mistaken. Within the early yr of investing, monetary leverage typically took the type of borrowing cash to purchase riskier investments (shares), however the wave of default and misery triggered for traders by the nice despair led to restrictions on the usage of margin in inventory markets. Nonetheless, these restrictions various throughout investor teams (with people going through extra restrictions than establishments) and throughout asset courses (with extra leverage in actual property than in shares). The expansion of derivatives markets opened the door to bypassing these borrowing restrictions, since shopping for a (bare) name choice is equal to borrowing the underlying asset with debt, with leverage growing with how out of the cash the decision choice is.
Since leverage magnifies each upside and draw back, it stands to purpose that traders with extra conviction of their funding, i.e., that it’s below priced and that correction is imminent or very prone to occur, will borrow more cash than traders with much less conviction:
When you find yourself sure that an funding will repay, you need to use maximal leverage, and in true arbitrage, this leverage can be utilized to transform small mispricing into pure earnings. Actually, when choices and futures are mispriced relative to their underlying belongings, you may borrow 100% of your funding wants, and for the reason that pricing error will disappear at maturity, make a pure revenue.
In sum, monetary leverage magnifies your core funding judgments. If they’re good, leverage will make them look higher over time, and if they’re unhealthy, they are going to make them worse. That mentioned, there’s a element to the usage of leverage that must be introduced into the image. Even if you’re a very good investor, with strong conviction in your funding concepts, utilizing debt to turbocharge your returns can generally shrink your time horizon by forcing you to liquidate your mispriced investments earlier than the market corrects its errors. That truncation threat eliminates the likelihood which you can come again out of your losses, and even perhaps have your funding thesis vindicated.
A Company Life Cycle Perspective on Conviction, Focus and Leverage
I exploit the company life cycle assemble in virtually each facet of finance, as a result of it not solely helps perceive company and investor habits, but additionally gives perspective on why one measurement (or proposal) doesn’t match all. The company life cycle maps out a agency’s evolution from a start-up to a development firm to maturity and eventual decline, and traces out adjustments in revenues, earnings and threat over the growing old course of:
There is no such thing as a deep mental perception right here, however as corporations age, the challenges that traders face in pricing them shifts. With younger corporations, the place there may be little historical past, the enterprise mannequin continues to be in flux and the worth lies virtually completely sooner or later, the pricing shall be much less exact than for extra mature corporations, the place there may be a longtime enterprise mannequin and extra monetary historical past, and extra of the worth comes from investments already made. For declining corporations, the place liquidation looms as a viable choice, the pricing train turns into considered one of estimating liquidation worth, i.e., what others pays for the person belongings owned by the agency. The upper pricing uncertainty that traders face when valuing youthful corporations is accompanied by a second drawback, which is that pricing errors, in the event that they exist, want catalysts for market correction. These catalysts are much less frequent and decisive with youthful corporations, the place earnings reviews have little of substance to report and working targets are diffuse, creating extra open questions on whether or not a market mistake shall be corrected, and in that case, when that can occur.
Utilizing this framework, you may see which you can be extra tolerant of concentrated portfolios, with debt added on, while you spend money on mature corporations than you need to be when investing in youthful corporations. By the identical token, traders who discover pricing errors in youthful corporations, however are daunted by the noisiness of their estimates or uncertainty about markets correcting, and thus are low on the conviction scale, can overcome their reluctance to behave by spreading their bets throughout many such corporations. As a few of you could remember, I did worth SpaceX on the time of its IPO at about $100 a share, and because the value has drifted down in direction of that value, I’ll very nicely be confronted with an underpriced inventory (the place the market value drops beneath $100). Given the uncertainty that’s related to my estimate, and you’ll see it within the simulation that I reported in my submit, it’s unlikely that I might ever have adequate conviction to make SpaceX the most important or solely funding in my portfolio, however I stand prepared to purchase the inventory as a part of a portfolio, the place it’s considered one of many bets that I make on markets.
Classes from Leo
I began this submit with the story of Situational Consciousness and Leo Aschenbrenner, however I spent most of it speaking about funding conviction, what it’s, its sources and penalties. I need to finish the submit by returning to Leo’s story and what we will study from it as traders.
Lesson 1: Funding actions which can be inconsistent with funding conviction threat damage
I’ve no points with Leo’s story of AI successful massive within the near-term and shopping for the winners and promoting the losers that can end result. It’s macro story investing, and it has labored for some prior to now and failed for others, but when timed proper, it will possibly ship important returns. Actually, I’ll concede that Leo is aware of way more about AI than I ever will and is utilizing that information in developing his AI story. I additionally haven’t any bone to select with traders utilizing monetary leverage to supercharge their returns, with low-risk investments, although I stay involved that the (2 & 20) payment construction could cause them to use an excessive amount of debt. My concern with Situational Consciousness, as a fund, and this might have been true on June 19, even at it peak, is that combining a macro story about AI successful with maximal leverage creates a time bomb. The AI story, regardless of how nicely instructed, has a number of obstacles to beat, some associated to enterprise economics and a few to politics and regulation, and is a dangerous wager, and it makes little sense to fund it with important quantities of debt. I do know that there are defenders who will level to the truth that the fund, even after its markdown, was up considerably from its inception date, however the truth that leverage reduce the fund’s life quick solely strengthens the case that if it had been run with much less debt, it will have had a foul month in July, however lived to inform the story and even perhaps ship on its AI promise.
Lesson 2: Momentum is a wild card in each funding technique, and also you ignore it at your personal peril.
It’s a well-established discovering in fairness markets that momentum is without doubt one of the strongest forces transferring markets and that it will possibly overwhelm the most effective deliberate methods of most traders. In case you take a look at the composition of State of affairs Consciousness portfolio by means of a lot of its rise and fall., the lengthy positions had been primarily in corporations that profit from the build-up of Ai structure, promoting their services to the hyper scalers and LLM corporations, and the quick positions had been in software program and different companies that might be disrupted by the rise of AI. With each teams, Situational Consciousness was taking bets that had been in step with what the market was pricing in already, albeit in a extra concentrated and leveraged kind. Whereas market observers had been fast to hyperlink each the rise and fall of Situational Consciousness to the AI story, you can also make simply as sturdy a case that a lot of that occurred on the fund over its temporary existence might be defined by momentum, with leverage performing as a brilliant charger; continued momentum generated the outsized return although June 19, and the market reversal in July induced the correction.
Lesson 3: Humble cash beats good cash
The legend of good cash persists in markets, the place traders who’re smarter than the remainder of us, with entry to info and capital that others don’t possess, ship supersize returns for themselves and those who they invite into their internal circle. That legend serves everybody’s pursuits, for the reason that good cash makes use of its repute to draw extra capital and the not-so-smart cash has another person (hedge funds, insiders, activists) in charge for funding setbacks. Whereas many cash managers aspire to be a part of the good cash group, most by no means make it into that rarefied circle, and those who do usually should pay their dues over lengthy intervals. Leo Aschenbrenner, in distinction, broke into the group in just some months, maybe helped by his pedigree as an AI insider and with an help from his submit on the approaching AI revolution. The issue with good cash is that its self-regard makes its inclined to attributing extra precision to its personal convictions, than merited by the circumstances, and that, in flip, ends in over attain (portfolios which can be a lot too concentrated or levered). Situational Consciousness clearly overused leverage, and whereas some will attribute that to the youth and inexperience of its lead supervisor, it’s price remembering Lengthy Time period Capital Administration, the place John Merriweather, after an extended and distinguished buying and selling tenure at Salomon Brothers, aided by two Nobel Prize winners in economics, introduced the fund to its knees by borrowing an excessive amount of on dangerous trades. In a submit from years in the past, I drew a distinction between good cash and humble cash, with the previous together with traders who attribute each foundation level of extra return earned to their investing brilliance, and the latter open about the truth that their efficiency, regardless of how stellar, has as a lot to do with being in the appropriate place on the proper time (being fortunate) because it has to do with ability. Traders in search of somebody to handle their cash are prone to do a lot better with the latter than the previous.
I hope that you do not view this as successful piece on Leo or AI, since that was not my intent. Actually, I hope that Leo persists and even perhaps comes again as a fund supervisor, since he strikes me as an authentic thinker who’s keen to take a stand, each scarce qualities amongst energetic fund managers. I additionally hope that he has realized some classes, particularly on humility and restraint, for his subsequent go round, and that he adopts a payment construction that provides his traders an opportunity of beating the market in the long run.
YouTube Video
Hyperlinks to the Leo Aschenbrenner story