by Ashley
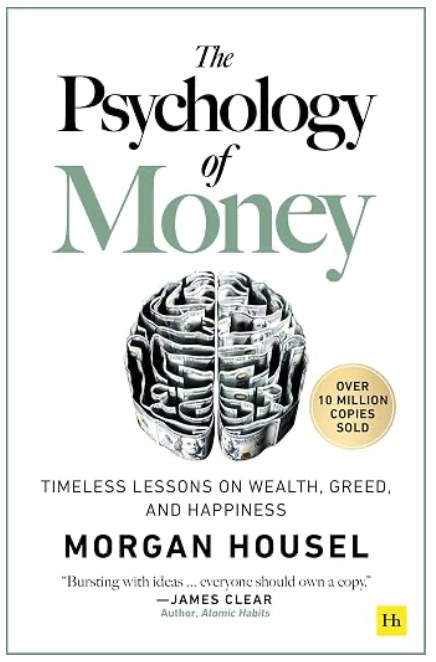
I only recently completed listening to an audiobook, The Psychology of Cash: Timeless Classes on Wealth, Greed, and Happiness by Morgan Housel.
The Psychology of Cash has nice classes about constructing wealth and studying the artwork of “sufficient.”
I’ve to be trustworthy. I made a decision to test it out as a result of I just like the subjects of Psychology and Cash, however I didn’t suppose I’d get lots out of the e-book. I figured I already know fairly a bit about cash and psychology (every individually), so I most likely would already know every part that was written within the e-book.
That turned out to be so, so flawed.
There have been so many nice tidbits from the e-book which have caught with me, and I need to share a few of them with you.
Wealth is what you don’t see…and debt is, too
With debt, folks would possibly see a brand new automobile within the driveway, a elaborate trip with first-class airfare, and designer garments, sneakers, or purses. What they don’t see is excessive bank card balances, HELOCs, or buy-now-pay-later plans with excessive rates of interest and the sleepless nights that accompany all that stuff.
With wealth, folks would possibly see an previous used automobile, modest holidays, and relative “homebodies” who eat at house and don’t have a variety of extravagance. What they don’t see is the rising 401K, funding account, and financial savings.
It’s simple to confuse debt for wealth. Once we see an individual with all of the “stuff”: good vehicles, good garments, good journeys, we predict wealth. And for some that could be the case. However for a lot of, the stuff is bought with debt. It’s not wealth. It’s the precise reverse.
It’s simple to realize wealth, however more durable to maintain it.
This was one of many basic rules of the e-book and though I urge to vary a bit on simply how “simple” it’s to realize wealth, I perceive the sentiment behind it. Housel’s level is that to realize wealth, you simply should dwell under your means and save and make investments persistently (particularly in down market occasions) over a protracted time frame.
That’s it.
I keep in mind from when I was a constant listener to the Dave Ramsey present how Dave would discuss his research of millionaires and one of the crucial constant options is that they lived under their means and all the time saved/invested. Most individuals don’t turn out to be rich by way of inheritance (although, sure, that occurs). Many of the millionaire-next-door sort of individuals accomplish that by residing frugally and squirreling away no matter additional they’ve over many, a few years. It doesn’t matter their wage, their common fee of return, and so on. It’s extra about consistency throughout time.
In distinction, how do you keep rich? By not spending it. Interval.
In his e-book, Housel talks in regards to the psychological side of wealth. When folks get cash, their “way of life” tends to creep up. They purchase a much bigger home, or go on extra lavish holidays or begin treating themselves to extras as a result of they really feel they deserve it. All that’s nicely and good. However in case you spend your wealth, then it’s now not wealth. It’s stuff. And most stuff depreciates in worth throughout time.
Know when sufficient is sufficient
Some of the compelling elements of the e-book to me was a bit anecdote of two buddies chatting at a billionaire’s celebration. When one of many males identified that their host made extra money in a single day than his pal had produced from a whole best-selling novel, the creator retorted, “possibly that’s true however I’ve one thing he’ll by no means have…sufficient.”
How many people get caught up within the lure of wanting extra and higher on a regular basis? The issue is, there’ll all the time be extra. How a lot home is sufficient? There’s all the time larger and higher. How a lot automobile is sufficient? There’s all the time newer and quicker.
How many people can actually say we’re glad with our life the best way it’s. That we have now sufficient.
Not too long ago I used to be chatting with some buddies who’re available in the market for an RV. They have been planning to get a selected model however, when taking a look at them, they’re too small. So that they determined they needed a much bigger RV. The issue is, which means they’ll want a much bigger truck (their present truck isn’t sufficiently big to tug the larger RV). However they need to have the ability to park their vehicles of their storage and the larger truck received’t match of their storage – it’s too lengthy by actually one inch (they measured). So now they want a brand new home with a much bigger storage.
I *suppose* they have been joking. However I imply…..????
I feel we will all get trapped in that cycle typically. I discover myself typically excited about and eager for a unique home. Even after we purchased our house, I by no means absolutely beloved it. I might have most popular a one-story or having the first bed room on the primary degree (it’s a two story house with the first upstairs). I’ve completely thought in regards to the thought of transferring. However we obtained our home for a killer deal – it was a short-sale through the pandemic and the earlier homeowners have been simply making an attempt to off-load it as quick as they may. It’s as a result of we have now locked in such an awesome rate of interest and comparatively modest mortgage that we’re in a position to afford to cashflow the journey we get pleasure from. With charges and residential costs as they’re now, far more of our month-to-month revenue can be spent on housing. We don’t need to do this.
Possibly that’s the largest lesson I took away from the e-book.
Private finance isn’t nearly math. It’s about psychology.
It’s about resisting the urge to match your life to another person’s spotlight reel. It’s about recognizing that each “improve” has an ongoing value. It’s about deciding what truly provides happiness to your life and what merely appears spectacular from the surface.
The irony is that lots of the habits that construct wealth don’t look rich in any respect. Driving an older automobile or staying in the home that’s “ok.” Packing lunches and saying no to issues you may technically afford. These selections hardly ever get likes on social media however they quietly create one thing far more worthwhile: freedom. Monetary independence. And the power to say sure to the issues that really matter.
I consider that always now, particularly if I ever really feel a tickling of wanting extra or higher. I’ve sufficient. That’s all you may actually ask for from a monetary perspective. And I’m very proud of the life we’ve constructed for ourselves.
I’m nonetheless on the lookout for readers who I can highlight in an upcoming sequence about paying off debt. In case you’ve paid off a variety of debt and wish to share your story and methods you used alongside the best way, please go away a remark and I’ll attain out by way of e mail to speak!
Hello, I’m Ashley! Arizonan on paper, Texan at coronary heart. Lover of operating, running a blog, and all issues cheeeeese. Early 40s, married mom of twins, and dealing in academia. At the moment working towards monetary independence with the objective of (hopefully!) retiring early at 50.