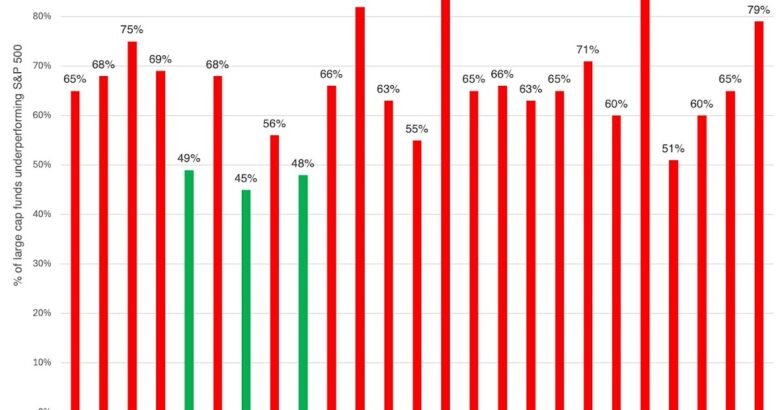
Over the previous couple of weeks, consideration has (rightly) been targeted on three probably trillion greenback corporations all lined as much as go public, and far of the dialogue has been about what SpaceX, Anthropic and OpenAI are value (and will probably be priced at). In parallel, there was a debate about indices and index inclusion standards, a often bland subject, however one which has grow to be heated on the questions of whether or not these new mega-cap additions to the market needs to be included within the S&P 500. Whereas I stay open to arguments from each side of this debate, a lot of it appears to return down on the facet that the index mustn’t embrace these corporations, with totally different causes provided. I’m skeptical, since I see a mixture of hidden agendas and misguided views about investing behind every of the three teams which are most vehemently in opposition to inclusions. First, you’ve got a cadre of lively traders, a lot of whom have been left bruised by a dropping battle that they’ve waged during the last 20 years in opposition to passive investments (index funds and ETFs), who view inclusion within the index as a fait accompli, and current this as an added threat to passive investing that may be prevented by paying these skilled cash managers to keep away from that threat. Second, you’ve got investing specialists and teachers who declare to be searching for for retail traders and retirees, and consider together with these massive, money-losing corporations in indices as harmful for these small traders, partly as a result of they will not be conscious of their publicity and partly as a result of they shouldn’t be investing in most of these corporations. Third, you’ve got politicians, usually not founts of funding knowledge, talking out about how together with these giant corporations in authorities pension funds will reward billionaires, who’re the villains of their storylines. On this submit, I’ll attempt to step again from the warmth and attempt to forged some gentle on the query of index inclusion, beginning with an understanding of how indices are constructed earlier than shifting on to the roles they carry out in markets and ending with a dialogue of whether or not and the way inclusion of those corporations will have an effect on the passive versus lively investing debate.Index Building – Inclusion, Weights and Returns Indices have been round virtually so long as property have been purchased and bought in markets, however it’s plain that the extraordinary progress of monetary markets in the previous couple of a long time, throughout geographies and asset lessons, has added rocket gas each to the variety of indices in existence in addition to their visibility. However what’s it that units one index aside from one other, and why do indices that purport to measure the identical market generally transfer in several methods? To grasp the reply to those questions, we have to deconstruct indices and see how they’re put collectively:Constituents: The primary and maybe most crucial determinant of an index are its constituents, and what determines their inclusion. Take, as an example, the S&P 500, which Normal & Poor’s (its creator) describes because the “gauge of large-cap US equities”, and is no doubt probably the most broadly tracked and adopted index in world markets. As its identify signifies, this index has 5 hundred of the biggest market-cap corporations listed and traded in america, with caveats on inclusion regarding itemizing age (listed not less than a yr), liquidity (measured by shares which are obtainable for traders to commerce out there, i.e., free float) and profitability (constructive earnings within the 4 quarters main into the itemizing). There are native indices that exchanges (NYSE, NASDAQ), fairness markets in different geographies (the Bovespa for Brazilian shares and the Sensex for Indian shares) and particular person sectors or industries. Throughout asset lessons, there are indices for fastened revenue, in addition to for actual property, nice artwork and crypto currencies.Weights: You may have two indices that include the identical corporations that register very totally different outcomes over time, relying on how these corporations are weighted, with three frequent selections. The primary is to weight each firm in an index equally, with the profit being simplicity, however the associated fee being that to the extent that corporations in an index have very totally different sizes, the efficiency on an equally weighted index is not going to seize combination market efficiency, as a result of will probably be skewed in the direction of smaller corporations. The second, and one utilized by some older indices just like the Dow 30, is price-weighting, the place the businesses with the very best value per share are weighted greater than corporations which have decrease priced shares. I can not consider a single redeeming high quality to cost weighting, because it measures little or no of consequence, and suffers from breakdowns, proper after inventory splits. The third and most generally used mechanism for building indices is market capitalization, with tweaks generally added on for float (traded shares). The S&P 500, as I famous earlier, makes use of market capitalization, primarily based on free float, to weight corporations and as a consequence, Meta punches in under its true weight, for the reason that bulk of sophistication B shares (that are voting shares held by Zuckerberg) should not counted, as does Walmart, the place some family-controlled holdings are handled as non-traded.Index degree mechanics: As soon as constructed, an index needs to be measured, and to the extent that these indices are designed to seize market costs, step one is making a mechanism for changing market costs on the constituents to an index degree. Take into account, as an example, the S&P 500 which ended buying and selling on June 15, 2026, at 7554.29, and relating that quantity to the market capitalization of the businesses that make up the index. At shut of buying and selling on June 15, 2026, the cumulative float-adjusted market capitalization of the five hundred corporations within the index was $63,498.44 billion and the index items for the conversion could be computed as follows:Index items = Index degree / Float-adjusted market capitalization = 7554.29/ 63498.44 = 0.1190 Notice that there isn’t a intuitive significance to the index items standing alone, however its actions over time could be an indicator of modifications taking place at corporations, due to issuances and inventory buybacks, in addition to modifications in index constituents. If requested to compute earnings or dividends on the S&P 500, these index items come into play once more, when changing the aggregated dividends and earnings throughout the entire S&P 500 corporations into index dividends and earnings. In 2025, as an example, the aggregated greenback dividends on the S&P 500 was $664.90 billion, and multiplying that worth by the index items (0.1190) yields an index dividend of 79.12 for the yr. Worth updating: Whereas index ranges are beginning factors, most traders observe indices for modifications within the index, with rising inventory costs translating into larger index values. Indices that observe publicly traded shares, just like the S&P 500 and the Dow 30, ought to regulate instantaneously as the costs of their constituent corporations change in the course of the course of a buying and selling day, making the index a real-time measure of market actions. Indices that seize solely value modifications miss the opposite part of returns on a inventory, which is dividends, and setting up an index that comes with dividends paid on a steady foundation does take work and requires assumptions about whether or not the dividends are reinvested within the index or extracted by traders. Although not as broadly disseminated because the pure-price model, there’s a variant of the S&P 500 that computes the entire return on the index, with dividends included. Indices of property that aren’t constantly traded, most notably actual property (just like the S&P Case-Shiller residence value index), attempt to overcome the absence of value information on the property by extrapolating from the pricing of the subset of property that get traded, resulting in noisier estimates for index worth and lags in value adjustment.Index modifications (inclusions and exclusions): Even the most effective constructed indices must confront change and have mechanisms to cope with that change which are clear and fast to place into apply. A few of that change will come from corporations being faraway from public markets, both as a result of they’re acquired, taken non-public or due to chapter. Some change will probably be brought on by new corporations being listed in the marketplace or some will probably be created by modifications in market cap in corporations that carry them into competition for inclusion within the index, both as a result of the market cap has risen (making them giant sufficient to qualify for a big cap index) or has dropped, eradicating them from giant cap standing. Since you don’t want abrupt modifications within the index degree coming simply from changing an organization with a low market cap with one with a a lot larger market cap, the adjustment has to return from altering the index items. Thus, assume that an organization goes public with a trillion greenback market cap and that will probably be changing an organization with a one-billion market cap, the adjusted index items for the S&P 500 will probably be as follows:Index items = Index degree / Float-adjusted market capitalization + Market cap of added agency – Market cap of eradicated agency = 7554.29/ (63498.44+ 1000 -1) = 0.1171This will then percolate by means of into the index earnings and dividends estimates, for the index. Notice that whereas the index degree will probably be unchanged by the addition of the trillion greenback firm, the opposite elements that it brings with it, together with larger progress and maybe detrimental earnings, will alter the basics of the index going ahead. With these index mechanics in thoughts, it’s fairly clear that if S&P does embrace SpaceX, OpenAi and Anthropic within the S&P 500 index, the index is not going to change on the time of the substitute, however it can change the index essentially going ahead, bringing in additional threat, a close to time period hit to earnings and maybe a long run improve in progress.The Index Finish Recreation When indices have been first created for markets, their main goal was to create composite measures of market efficiency, with a single quantity (the index worth) capturing the efficiency of a a lot bigger group of property. Over time, although, using indices has expanded, first as proxies to evaluate the efficiency of lively traders, to see whether or not they over or underperformed, after which as funding autos, with the arrival and progress of index funds and ETFs. Measurement I began in fairness markets in 1981, and at the moment, indices have been primarily measures of market efficiency. On the time, for many traders with out intraday entry to markets and with out monetary information channels, information of market efficiency, on most days, was a snippet on the night information, the place the anchor would point out the market’s change in the course of the day, often utilizing the Dow 30 as a stand in for the market. Indices proceed to carry out the measurement function, although our entry to information has modified dramatically, with actual time updates on our gadgets occurring all by means of the day. From the measurement perspective, it’s value wanting again at index building and on the lookout for indices that finest seize what you are attempting to measure. The explanation that the S&P 500 has acquired primacy is that whereas it contains solely 500 corporations in a US fairness market that has virtually 6000 publicly traded corporations, the truth that these are the businesses with the biggest market capitalization implies that the index represents greater than 80% of the market capitalization of all US equities, and because of this, it’s the single finest proxy for combination fairness market efficiency within the index. That mentioned, a unique framing of the measurement query can lead you to a unique index selection. Thus, if you’re attempting to measure how the common US fairness did throughout a interval, you could be higher served utilizing an equal-weighted fairness index for that measurement. Efficiency Analysis Traders who belief professionals to handle their cash, and pay them for his or her companies, both as up-front entry charges or in annual administration bills, are entitled to wonder if they’re receiving a compensatory profit, within the type of larger returns. It shouldn’t be stunning that evaluating a mutual fund’s returns to the returns on an index turns into a proxy for fund efficiency, and within the early years of efficiency analysis, the S&P 500 grew to become the default comparability index. Utilized in that context, one of the crucial jarring numbers in lively investing is the proportion of lively giant cap funds that earn returns which are decrease than the S&P 500, annually for the final 20 years:S&P GlobalOver the final twenty 5 years, there have been three years the place greater than 50% of lively funds have overwhelmed the S&P 500 index, and barely so, and the extent of underperformance within the remaining years i staggering. The pushback from some lively fund managers is that, given their funding types, the S&P 500 is just not the best index to make use of to evaluate them. Worth fund managers, who invests in low-risk and high-dividend paying inventory will argue that the portfolios they create are much less dangerous than the S&P 500, making their decrease returns extra of a threat impact than underperformance. Educational research that used threat and return fashions to tweak the index returns have been rapidly dismissed as being improper, as a result of the fashions that have been used (the CAPM, the APM, Multi-factor fashions) have been flawed. This impasse was damaged by S&P, when it created SPIVA, the place the returns earned by fund managers in any class (small cap vs giant cap, progress vs worth, home vs international) are in comparison with returns that traders might have earned by investing in index funds in the identical class, and by Morningstar, utilizing a variant of the identical method. Thus, a fund supervisor who invested in small-cap, excessive dividend paying shares would see his or her returns compares to the returns you’ll have earned on a small-cap, worth index fund, making it way more tough to elucidate away underperformance. There are lots of causes for the slippage in lively investing’s share of general investing within the final 20 years, however the SPIVA outcomes are devastating and damning for any declare of lively investing superiority. Right here, as an example, are the outcomes, by funding class, on the proportion of lively fund managers who underperfomed index funds of their funding fashion, during the last decade, on the finish of 2025:There’s little or no hope in these numbers, as fund managers underperform their respective indices in each single class, and by extra, over longer intervals. In actual fact, there’s not a single fund group in any fashion that outperforms its respective index previous ten years. For these of you who’re studying this different geographies, and believing that it’s totally different in your native markets, both as a result of insiders have privileged entry to data or market inefficiencies, SPIVA additionally tracks fund supervisor efficiency exterior america, and stories related outcomes:At this level, there’s virtually no counter to the argument that lively investing collectively creates a drag on portfolio efficiency, and lively traders searching for to defend the career are left wanting by means of the info entrails, hoping for niches the place “alphas” exist. Thus, 20 years in the past, the notion that non-public fairness traders and hedge funds have been smarter than the market and will beat the market fueled a push of retirement and endowment cash into these autos, however as they’ve grow to be bigger, they’ve come to resemble mutual funds, when it comes to efficiency. Investing Autos There’s a third use of indices that, in my opinion, has overwhelmed the measurement and efficiency analysis roles that they play, and it’s that they’ve grow to be autos for investing within the type of index funds and exchange-traded funds (ETFs). That risk was already existent in 1981, however at the moment, the one index with an index fund obtainable to most traders was the S&P 500. As we speak, you cannot solely put money into index funds throughout geographies, sectors or sub-groups primarily based on fundamentals (together with volatility, measurement and earnings), however the trade traded fund explosion has given you an alternate route, with barely larger prices (than index funds) and extra liquidity. Vanguard, a pioneer when it listed the S&P 500 index fund in 1976, now lists greater than 100 ETFs and greater than 2 hundred index funds, permitting traders to not solely put money into virtually any market, but additionally within the subsets (sectors, small corporations and so forth.) that they selected to. The scale of the index fund enterprise and the charges its creates for the index creators has created some tensions within the course of, and confronted with a selection between a poorly constructed index that index fund traders would like to commerce on and a greater constructed one which traders discover much less enticing, it’s potential and even perhaps possible that the fund creators will choose the previous.Indexing and Passive Investing – Unintended Penalties There are two forces that the final part spotlight which have performed out in altering monetary markets structurally and dramatically within the final 20 years. The primary is that the underperformance of lively investing has grow to be simpler to doc and extra seen for everybody to see. The second is that traders who see this underperformance have extra passive investing autos within the type of index funds and ETFs accessible to them, and may transfer their cash into them. As a consequence, within the battle between lively and passive investing for investor {dollars}, the struggle is getting so one-sided that, in the event you have been a referee, you’ll invoke the mercy rule and attempt to cease it:It’s plain that the rise of passive investing autos has empowered traders, who’ve gained when it comes to selection and prices, but it surely has additionally created an existential disaster for lively traders, and particularly so for individuals who make a dwelling out of managing different folks’s cash. Whereas some lively traders maintain on to hope – that they’re higher than the remainder, that this can be a cycle that can reverse, that some new know-how (massive information, AI) will save them- there are others who’ve taken a unique tack. Principally conceding that index funds and ETFs have outperformed fund managers, they’ve taken to arguing that the rise of passive investing is creating prices and results that outweigh its advantages, and that motion is required urgently, although it’s unclear from whom. On this part, I’ll spotlight three of these results.1. The Index Inclusion Enhance The addition of an organization to a well-known or broadly adopted index (the S&P 500, Dow 30, MSCI International) yields pluses, rising its visibility to traders and probably making it extra investable, in addition to rising buying and selling quantity on the inventory and making it extra liquid. The query of how these advantages get priced in when a inventory will get added to an index (and the prices of being faraway from an index) have been studied over time, with a deal with additions to (and removals from) the S&P 500. As passive investing has grown, with extra selections in index funds, it stays true {that a} vital share of passive traders maintain S&P 500 index funds, and that, within the eyes of some, this could make inclusion within the S&P 500 index an excellent larger constructive at this time than in a long time previous. Trying throughout these research, there appears to be a consensus that there’s a bump up within the inventory value from an organization being added to the S&P 500, and bump down, when an organization is deleted from the index, however disagreements each in regards to the magnitude of the bump and whether or not it’s everlasting and transitory. The final sense that you simply get from research is that bump in inventory costs from being included within the index has grow to be smaller and extra transitory over time, and within the final decade or 20 years, it has largely disappeared. To again this up, I take a look at one of the crucial full research that I’ve seen of the index inclusion query, the place S&P took a take a look at the 715 corporations added and 711 firm deletions made to the S&P 500 between January 1995 and June 2021, and look at the surplus returns within the days across the change:As you possibly can see, the positiv eprice results of being added to the S&P 500 index have depleted over time, as have the detrimental value results of being faraway from the index. Notice that this discovering cuts in opposition to the argument that as passive investing has elevated within the final 20 years, the attract of being within the S&P 500 must also have gone up. As an alternative, as the worth of funds listed to the S&P 500 has surged during the last 20 years, the impact of being added to or taken out of the index has grow to be smaller, not bigger, and there’s proof accumulating that corporations that get added to the S&P 500 usually tend to underperform than outperform within the twelve months after the addition. As the controversy about whether or not SpaceX, OpenAI and Anthropic needs to be included within the S&P 500 index heats up, I’d counsel that the proof of a small and dissipating value impact of inclusion has to grow to be a part of the dialogue. I’m positive that there will probably be some who will disagree with me, however I do not suppose the worth trajectories of any of those corporations will probably be altered by whether or not they’re included in or excluded from the S&P 500. For individuals who disagree with me, and imagine that being added to index is bullish for traders in these corporations, I’d suggest that you simply take a look at the chart from this research which took a take a look at Tesla’s inventory value habits earlier than, throughout and after its substitute of Residence Funding and Administration (AIV) within the S&P 500 on December 18, 2020. Tesla not solely beneath carried out the S&P 500 within the months after its inclusion within the index, however massively underperformed the corporate (AIV) that it changed within the index.2. Momentum versus Fundamentals Because the funds invested in index funds and ETFs has surged, the argument that some are making is that being added to an index provides you a lift, largely due to index fund flows to corporations in that index, and extra of a lift if you’re a big cap firm. Because the cash flows from different shares, this line of thought additionally means that fundamentals will obtain much less consideration and disconnect extra from costs, particularly as a result of there are fewer lively traders doing analysis and on the lookout for market inefficiencies. As well as, they word that since indices are principally market cap weighted, this momentum advantages bigger market cap corporations, in impact permitting them to grow to be bigger. As proof in favor of this argument, they level to the truth that markets have grow to be high heavy, the place just a few winners are carrying your complete market, that the small cap premium, an everlasting characteristic of fairness markets within the twentieth century, has largely disappeared on this one and the dominance of momentum in investing success within the final decade. I concede that these phenomena are in keeping with the “passive investing feeds momentum” story, however I’m skeptical that passive investing is the trigger for the next causes:Momentum can lower in each instructions: It’s true that funds flowing into index funds circulation into the businesses in that index, with extra flowing into giant cap corporations, however it is usually true that funds can circulation out of index funds, and when that occurs, the momentum can lower within the different course. In actual fact, the conclusion is that inclusion in a widely-tracked index (just like the S&P 500) will improve intraday and brief time period volatility, however not value ranges. In actual fact, the fading value bump from being added to the S&P 500 that we famous within the final part is a sign that the market doesn’t purchase into the momentum story.Winner-take-all economics: If momentum is the rationale for the large corporations profitable, there needs to be divergence between small and massive corporations on how fundamentals get priced. Put merely, it’s best to see the pricing metrics (PE ratios, EV to EBITDA) for big cap corporations rising relative to small cap corporations, as passive investing surges. Trying again on the fading small cap impact and top-heavy markets of the final decade or two, I’d word that not all giant cap corporations have been winners, and the profitable giant cap corporations have delivered a disproportionate portion of elevated earnings. Within the context of the Magazine Seven, I’ve talked about how know-how and disruption has modified extra industries into winner-take-all companies, with just a few corporations dominating these companies, and why that phenomenon will play out in markets as nicely.Lively investing and fairness analysis: In my opinion, the notion that almost all analysts and lively traders are on the lookout for market inefficiencies and searching for out data strikes me as misplaced. A lot of lively investing is constructed round publicly obtainable data and a perception within the energy of imply reversion, not unique analysis and searching for data. It’s true that there’s a subset of lively traders and fairness analysis analysts who contribute to creating costs extra informative, however that subset is a small one, and one that’s higher outfitted to outlive the passive investing shift.Doomsday tales about how passive investing is making markets much less environment friendly and fewer inclined to mirror fundamentals strike me as overwrought, and whereas lively investing will proceed to lose market share, and deservedly so, it is not going to disappear. Since these tales are sometimes being informed by fund managers who not so way back spoke contemptuously about environment friendly markets as an educational fever dream, additionally they strike me as each hypocritical and self-serving. Even in the event you settle for the argument that passive investing is making markets much less environment friendly and extra momentum-driven is true, I’m not sure in regards to the implications for investing. Asking particular person traders, retirees and endowment funds to pay charges to professionals to handle their cash whereas underperforming indices, in service to the bigger explanation for market effectivity is tone deaf and a non-starter. In actual fact, any endowment or pension fund supervisor who makes use of this argument to steer endowment funds to lively cash managers could be in violation of his or her fiduciary accountability. Maybe, the argument is being made to regulators to limit index funds (on which indices they’ll index, how a lot cash they’ll handle), I can see why lively cash managers could also be in favor, as a result of I perceive that they’re attempting to guard their livelihood, however they need to dispense with any speak about defending particular person traders or making markets extra environment friendly.3. Hidden dangers An undercurrent in a number of the opinion items that I’ve examine why SpaceX shouldn’t be included within the S&P 500, written by funding specialists and teachers, is that it’s going to expose retail traders and retirees to dangers that they’re unaware they’re taking, or even when made conscious of the actual fact, shouldn’t be taking within the first place. Particularly, these opinion-writers appear to be arguing that the dangers related to investing in an enormous, money-losing corporations (like SpaceX, and presumably OpenAI and Anthropic, once they go public) are so giant that particular person traders and retirees wouldn’t put money into these corporations, and even they might, they shouldn’t be allowed to take action. I discover this chain of reasoning to be each misguided and condescending, and reflective of misconceptions which are deeply and broadly held within the funding professional class:Danger and Diversification: Is it true that particular person traders, if made conscious of the businesses that they owned in index funds, would blanch on the dangers that they’ve uncovered to in particular person holdings? Investing simply in a portfolio of some corporations like SpaceX could be imprudent, however an investor in a S&P 500 index fund is much much less uncovered to underperforming the market than the standard lively cash supervisor who both over invests in SpaceX (if it goes down) or chooses to not put money into it (if it goes up). Sensible and Silly Cash: Whereas the funding specialists and teachers who push to guard retail traders and retirees from their very own errors won’t ever put into phrases this perception, implicit on this push is the view that these small traders are uninformed and naive, and will probably be exploited by good cash (institutional traders and hedge funds). The notion that the good cash will know whether or not SpaceX (and corporations prefer it) is overvalued or beneath valued, and is positioned to time investments higher is fanciful, since institutional traders are extra merchants than traders, making them market followers, not chief. Good companies and good investments: The weakest hyperlink within the argument in opposition to placing your cash in money-losing corporations is the implicit perception that money-making corporations are good (secure) investments and that money-losing corporations are dangerous (dangerous) ones. I’ll wager than an investor who was constrained to take a position solely in money-making companies within the final 20 years would have beneath carried out an investor working with out these constraints, even after adjusting for threat. On the proper value, a money-losing firm generally is a good funding and on the improper value, an organization with stable and steady earnings generally is a dangerous funding. I’m usually skeptical of makes an attempt to guard particular person or retail traders from their very own errors and choices, since extra harm has been accomplished to this group by these claiming attempt to assist and defend them over time than by those that are out to use them.Conclusion Within the week previous to the SpaceX IPO, S&P eliminated a number of the suspense within the query of whether or not the corporate could be included within the index by saying that they might keep on with their requirement that an organization be listed and traded not less than a yr earlier than turning into eligible for index inclusion. That call additionally implies that OpenAI and Anthropic, in the event that they do go public this yr, can even have to attend a yr for consideration. I’m glad that S&P is just not altering the principles to permit these corporations to leap the queue to get into the index, however I hope that it’s not framed as a call that was taken to guard traders or within the hope that these corporations would grow to be magically cash making, higher ruled and with working enterprise fashions. The reality is {that a} yr after they record and begin buying and selling, these three corporations will nonetheless be cash dropping companies, with enterprise fashions which are nonetheless works in progress and can stay company governance horror tales. S&P wants the time to handle the transition of three trillion-dollar corporations into the index, even because it confronts the problem of claiming to be a big cap index that doesn’t embrace three of the biggest market cap shares out there. As for the businesses (SpaceX, OpenAI and Anthropic), I’ll wager that they are going to lose little in market momentum from not being included within the index, and that their value paths will probably be decided by how the AI story continues to play out when it comes to each substance (progress, unit economics, reinvestment) and notion (hype and momentum). The underside line is that S&P wants these corporations in its index greater than they should be within the index, with the consequence that the businesses is not going to exit of their approach to meet index necessities that they really feel are pricey to them, and that if there’s any bending, will probably be S&P that does it.YouTube Video
The S&P 500 Inclusion Query and Funding Penalties!