For the primary time since its launch a decade in the past, retailers will quickly should pay charges to make use of the system. Some are suggesting that Washington could also be behind the transfer.
In September, India’s Narendra Modi authorities unveiled a radical change to its Unified Funds Interface (UPI), the nation’s immediate digital fee system. That change concerned the introduction of charges for the primary time since its pilot launch in 2016. In September, the Nationwide Funds Company of India (NPCI) stated a 0.4% price would apply from October 15 (i.e. yesterday) to sure UPI funds above 2,000 rupees ($21) made to companies by clients.
The preliminary announcement sparked fears that the charges may elevate bills for companies, and by extension their clients, and discourage them from utilizing the system. As these fears rose, the authorities made a partial U-turn. On October 13, simply two days earlier than the price was to return into impact, the NCPI postponed the rollout till after the Diwali pageant. However it is just a short lived respite.
UPI is the world’s largest actual time funds system, with over 500 million customers. In August alone, it processed 24.51 billion transactions value ₹29.82 trillion ($314 billion). Nevertheless, one of many major causes for UPI’s plain success is that it’s (or at the least was) free to make use of for everybody. Many distributors initially made the swap to UPI as a result of it was promoted as a free, handy fee resolution.
Launched in 2016 as a private-public partnership, UPI lets folks ship and obtain cash immediately by way of cell apps, very like Brazil’s Pix system. The velocity and ease of use has made it an integral a part of the Indian economic system, utilized by everybody — from small distributors to giant companies. As Enterprise Occasions notes (with the media’s ordinary disdain for money), “paying for items not entails dealing with grubby previous forex notes.”
The fee rails undergirding the system are operated by the Nationwide Funds Company of India (NPCI), an umbrella organisation established as a not-for-profit initiative by main banks. The underlying protocol standardises real-time bank-to-bank transfers in order that any financial institution or pockets can discuss to every other with out closed, proprietary partitions.
This has allowed personal firms to construct client and service provider apps that sit on prime of the general public fee rails. Till now, the federal government, banks and fee firms have borne the price of operating and increasing the system, which is at the moment dominated by two foreign-owned apps: Walmart’s PhonePe and Alphabet’s GooglePay, which collectively get pleasure from round 80% market share by worth of UPI transactions.
The brand new cost, often known as the Service provider Low cost Fee (MDR), is predicted to assist cowl a few of these prices, and will probably be distributed amongst fee system suppliers — together with banks — to assist operations and continued growth, the finance ministry press launch acknowledged. That’s the official cause, however it is probably not the one one. As some are mentioning, the US authorities may have performed a component within the choice.
Fascinating Timing
The announcement of the introduction of the MDR got here simply as India and the US are working to finalise their bilateral commerce deal. This has fuelled hypothesis that the Modi authorities was pressured by the Trump administration into imposing the price. Earlier this week, Congress Congress common secretary Jairam Ramesh stated the federal government had damaged the belief of UPI customers and requested whether or not it had carried out so on behalf of US firms to appease Trump.
Whereas there is no such thing as a definitive proof to again that assertion, Washington has persistently pushed most of its commerce companions to create a degree taking part in discipline of their respective digital transaction ecosystem, stories India Categorical:
Since UPI’s launch in 2016, US funds market intermediaries Visa and Mastercard have cited lack of potential enterprise as shoppers in India more and more turned to free UPI funds moderately than utilizing playing cards.
The Delhi-based suppose tank International Commerce Initiative (GTRI) stated that the businesses object to the “Zero transaction fees for UPI and RuPay, authorities promotion of RuPay, and RuPay’s early entry to credit-card funds by way of UPI. This has strengthened RuPay and lowered the price earnings of US card firms, it stated.
It stated that the 2 firms function below a mannequin the place banks, fee processors and card networks earn charges from service provider transactions. A broadly accessible, interoperable and zero-Service provider Low cost Fee (MDR) platform, comparable to UPI, limits this income pool. An MDR is levied on retailers by banks that course of funds to assist meet transaction processing, settlement and infrastructure prices.
Additional, RuPay challenges their place by offering an Indian card community that may be built-in carefully with home coverage targets, GTRI stated.
In March, the USA Commerce Consultant (USTR) had categorized India’s digital fee insurance policies “favouring” home gamers as a international commerce barrier. Such boundaries in numerous sectors are distinguished calls for below the proposed US-India commerce deal.
The USTR stated that “it has expressed considerations associated to the lack of US digital fee providers suppliers to take part within the UPI ecosystem, together with credit score transactions on UPI on a degree taking part in discipline with RuPay”.
“In November 2020, Nationwide Fee Company of India (NPCI) introduced a market share limitation of 30% (measured by transactions) for third-party app suppliers initiating on-line funds made by way of India’s UPI. Whereas this market share cap for third-party fee apps was initially mandated for January 2023, the NPCI has deferred enforcement, with the present deadline set for December 2026. As of December 31, 2025, two US-owned EPA suppliers collectively processed greater than 80% of all UPI transactions,” USTR stated. These suppliers are Walmart-backed PhonePe and Google Pay.
In different phrases, the USTR is anxious not solely in regards to the danger of UPI and its accompanying international card fee community, Rupay, eroding the market share of VISA and Mastercard in India (and probably past), but additionally about India’s plans to cut back the dominance of the 2 US-owned fee apps, Walmart’s PhonePe and Alphabet’s GooglePay, over the UPI area.
Parallels With Brazil
This isn’t the primary time the US has tried to bully a rustic into altering its indigenous fee system. As we have now beforehand reported, Brazil’s improvement of Pix, a publicly owned and managed digital funds system that has lowered the nation’s dependence not solely on Visa and Mastercard’s international duopoly but additionally on the cell fee apps of US tech giants, has induced consternation on Wall Avenue and Silicon Valley, and by extension Washington DC.
The Workplace of the US Commerce Consultant started investigating PIX final 12 months, warning that Brazil has given an unfair benefit to the digital funds system by requiring all banks to supply it. In line with the NY Occasions, US commerce authorities are additionally involved that, by defending client knowledge that Pix collects, the Brazilian authorities is hurting American firms that use such data to make enterprise choices and develop new merchandise.
“U.S. firms see this knowledge as essential,” stated Ignacio Carballo, a senior marketing consultant at Funds and Commerce Markets Intelligence, a analysis agency based mostly in San Francisco. “This locations loads of energy within the palms of Brazil’s authorities.”
By embracing a largely publicly led digital funds infrastructure that cuts out the same old center males, Brazil has turned monetary innovation on its head. In most superior economies, money’s dominant function within the retail funds system has been eroded by digital fee options, primarily from the personal sector, specifically contactless debit and bank cards. Cell wallets operated by US tech giants are additionally on the rise.
This has been an enormous boon for Visa and Mastercard, which have carried out the whole lot they’ll to supplant their greatest rival (to this point), money. In Brazil, nevertheless, Pix has not simply overtaken money; it has overtaken the whole lot. As an article in Remainder of World notes, it overtook debit card transactions in January 2022 and bank cards in February 2022, and now dwarfs transactions by way of bank cards, debit playing cards, financial institution slips, wire transfers, pay as you go playing cards, and checks mixed.
One main distinction between Pix and UPI is that Pix is a public funds system created, owned, and operated by the Central Financial institution of Brazil (BCB) whereas UPI is a private-public system that’s already dominated by two US-owned apps. Additionally, Brazil’s President Luiz Inácio Lula da Silva has resisted US strain to convey Pix into line. A couple of months in the past, he rejected any chance of Pix being altered or privatised with a view to profit US monetary pursuits.
“We defend Pix from any try at privatization. Pix is from Brazil. It’s public, it’s free and it’s going to remain that approach.”
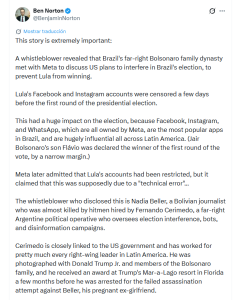
That stated, Lula could quickly not be president of Brazil, if latest polls for the second spherical of the upcoming presidential elections are any indication. Lula already misplaced the primary spherical to his major rival, Flavio Bolsonaro, who has already agreed to make sure concessions on Pix. Because the tweet beneath explains, Bolsonaro is benefitting from the assist not solely of the US and Israeli governments but additionally US tech corporations like Meta.
A Sticky Dilemma
Again in India, the proposed imposition of a price on UPI leaves Indian enterprise homeowners dealing with a sticky dilemma: soak up the extra expense themselves or cross it on to their clients. As a direct end result, these transaction fees are prone to elevate the costs of fundamental items and providers. All the things from meals gadgets and gas to routine retail purchases over 2,000 rupees will successfully turn out to be costlier for unusual buyers.
Until, after all, they return to money, which continues to play a significant function within the Indian economic system, whilst digital funds have exploded. Certainly, the amount of money in circulation continues to develop as its share of on a regular basis funds shrinks, stories the BBC:
The Reserve Financial institution of India (RBI) – the nation’s central financial institution – now has 176 billion banknotes in circulation. It’s printing 28-30 billion contemporary ones throughout six denominations yearly and retiring roughly 21 billion. It’s a huge logistics operation.
And but, as Unified Funds Interface (UPI) digital transactions surge in direction of a billion a day, money sloshing across the economic system retains climbing at a brisk tempo.
The puzzle just isn’t that Indians nonetheless use money – 94% of transactions had been cash-based as lately as 2019, in line with new analysis by Anirudh Tagat, Mehmet Ozmen and Pushpa Trivedi. It’s that money is rising whilst its share of on a regular basis funds shrinks.
“The money paradox has been examined globally, and India is a singular and novel case examine of the identical given the size of each money and non-cash funds,” Tagat, an economist who research Indian fee behaviour, instructed the BBC.
He notes that the phenomenon of money rising alongside digital funds has been particularly distinguished because the 2007-08 international monetary disaster, with Financial institution for Worldwide Settlements analysis exhibiting the same sample worldwide.
In Tagat’s framing, forex nonetheless serves three functions – as a way of fee, a retailer of worth and a hedge in opposition to calamity. Apps are changing solely the primary. That helps clarify why digital funds alone can not inform the entire story of money demand.
It will likely be attention-grabbing to see what penalties the introduction of charges to UPI has for India’s native fee system. In any case, the Modi has carried out greater than any authorities in Indian historical past — and greater than most governments all over the world — to advertise digital fee strategies.
It was the Modi authorities, with the assist and steering of the Invoice and Melinda Gates Basis, that launched India’s demonetisation marketing campaign in 2016, whose disastrous penalties Jerri Lynn Scofield coated in nice deal for this website. It was the Modi authorities that launched UPI simply months earlier, in addition to Aadhaar, India’s biometric digital identification system, years earlier.
There have been solutions that USAID, the CIA’s soft-power arm, performed a key function in selling UPI. It’s definitely coincidental that months after the launch of UPI, USAID introduced the launch of a brand new initiative, referred to as Catalyst of all issues, in partnership with the Indian finance ministry, to scale digital funds programs in India.
A Transient Delay in Implementation
On Tuesday, the Nationwide Fee Company of India introduced that it had determined to postpone the rollout of charges on UPI till after the Diwali pageant. From Reuters:
“Diwali, which will probably be celebrated throughout India on November 8, usually marks the height of client spending in Asia’s third-largest economic system, with buyers splurging on automobiles, garments and residence home equipment”:
The proposed price, which might finish greater than six years of zero-cost UPI funds in India, had drawn opposition from retailers…
The delay in implementation would probably permit funds corporations to improve programs and never cross on prices to clients, whereas addressing points that retailers could face through the festive interval, Reuters reported final week, citing sources…
Shares of digital funds corporations Paytm (PAYT.NS), opens new tab, Pine Labs (PINL.NS), opens new tab and One MobiKwik Techniques (ONEM.NS), opens new tab gained 1%, 1.8% and 1.3%, respectively, after the information.
“The discover…brings certainty that the MDR (Service provider Low cost Fee) goes to be applied and there’s no extra scope of any pushback…versus the earlier uncertainty across the timeline,” stated Rahul Jain, director of analysis at Dolat Capital.
“That could be a constructive for the businesses,” he added.
Mentioned firms presumably embrace VISA and Mastercard.