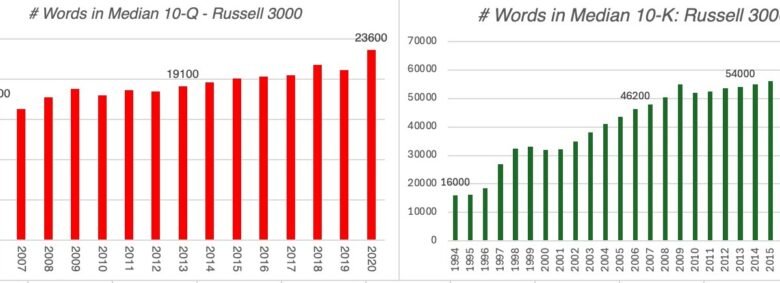
I’m a lapsed educational, insofar as I’ve not submitted a paper for publication in additional than 20 years, however to amass educational standing, I did should earn a PhD within the distant previous. My doctoral dissertation, which like most doctoral theses is little famous and lengthy forgotten, was accomplished in 1984 and targeted on how the frequency of and delays within the launch of knowledge performs out in inventory value volatility, skew and jumps. I do not plan to rehash that paper, however there have been two lengthy working information tales that jogged my memory of it. The primary is a proposal being floated by the Securities Alternate Fee (SEC) to exchange quarterly reporting of monetary statements by corporations with semi-annual reporting. The second is the opinion voiced by Kevin Warsh, the brand new Fed Chair, that the Fed ought to present much less steerage to monetary markets on future choices. The 2 tales could seem unconnected, however they’ve two frequent options. First, each actions (eradicating quarterly reporting necessities and lowering/eliminating Fed steerage), if carried by, will take away “information” that markets have turn out to be used to receiving and utilizing to calibrate costs. Second, the arguments for and towards every of those proposals have parallels. The advocates for eradicating quarterly experiences argue that they feed into market myopia and improve short-termism in markets, and the supporters of much less Fed steerage imagine that this steerage creates gaming amongst merchants and traders, growing deal with the FOMC actions on the expense of fundamentals. The pushback towards each proposals comes from those that imagine that withholding quarterly experiences and Fed steerage removes data that markets use to set costs, making these costs extra unstable and fewer informative. As is sort of all the time the case with these debates, there may be each reality and hyperbole on each side, and I’ll attempt to thread the needle.Earnings Stories Most traders and merchants in fairness markets, and particularly so in america, have spent their investing lifetimes in an surroundings the place corporations not solely launch full monetary statements each quarter, however achieve this with fan fare. As we are going to word on this part, that has not all the time been the case, even within the US, and has more moderen origins, with setbacks, in lots of overseas markets. The Historical past of Earnings Reporting Periodicity The Securities Alternate Act of 1934, which created the SEC, arrange foundational annual reporting necessities (10-Ks) for publicly traded corporations, modified in 1955 to require semi-annual reporting and in 1970, quarterly experiences, inside 45 days from the top of every quarter. That mentioned, there have been forces which have induced companies to report earnings on a extra frequent foundation to traders nicely earlier than these regulatory necessities had been put in place. The primary had been the inventory exchanges that imposed their very own constraints, with the NYSE requiring most companies to report on a quarterly foundation as early as 1939. The second was the popularity by companies that monetary transparency (within the type of extra frequent and extra detailed monetary experiences) may make them extra enticing to traders. As a consequence, it’s estimated that in 1931, previous to both the SEC or NYSE mandating disclosure, greater than 60% of publicly traded corporations had been already disclosing data on a quarterly foundation. The shift to extra frequent reporting was slower in the remainder of the world and has seen extra reversals. Europe, for a lot of the final century, has a patchwork of guidelines, with some international locations adopting stricter disclosure legal guidelines than others. The UK imposed obligatory quarterly earnings reporting in 2007, however allowed a shift again to semi-annual reporting in 2014, and the EU additionally adopted an identical timeline, introducing quarterly experiences in 2007 and withdrawing that requirement in 2013. In 2003, Singapore began requiring quarterly reporting for companies with market capitalization exceeding S$20 million, however in 2020, shifted away to requiring it just for a subset of companies with monetary and regulatory issues. Japan began its quarterly reporting necessities in 2003 as nicely, but it surely too reversed that requirement in 2024. In rising markets, there are giant variations throughout international locations. In India, publicly traded corporations are required to report their financials on a quarterly foundation, and the identical is true for a lot of Brazilian and Chinese language corporations. In Africa, Nigeria requires quarterly reporting however South Africa has a semi-annual reporting mandate, although many corporations voluntarily launch quarterly financials; a lot of the remainder of Africa has semi-annual reporting necessities. In sum, the idea firstly of the twenty first century that the remainder of the world would comply with the US mannequin of mandated quarterly reporting for publicly traded corporations has not come to fruition, as many components of the world have experimented with obligatory quarterly reporting, earlier than abandoning it in favor of semi-annual reporting, for a wide range of causes. That mentioned, it’s value noting {that a} important share of companies voluntarily report their monetary outcomes on a quarterly foundation, even when not mandated, albeit with totally different levels of depth.The Content material of Earnings Stories The controversy about how continuously corporations ought to report their financials misses a key element associated to what their monetary experiences embody as content material. Specializing in the US, as an illustration, the magnitude of quarterly earnings experiences has elevated over time, increasing from naked bones monetary statements fin the Seventies to a lot bigger paperwork that go nicely past monetary statements at this time. In 1980, as an illustration, a typical quarterly earnings report contained 2000-5000 phrases, however by the flip of this century, these experiences had tripled or quadrupled in measurement, and the tendencies proceed. The graph beneath, as an illustration, appears on the progress in phrase depend for the median quarterly and annual experiences within the Russell 3000 corporations between 2006 and 2020 (for quarterly) and 1994 to 2020 (for annual):As you possibly can see the variety of phrases in each quarterly and annual experiences has elevated over time, and the bulking up of earnings experiences will be defined by a number of elements:Accounting rule adjustments: Accounting rule writers have been busy including extra gadgets to the record of required disclosures for public corporations in the previous few a long time. A few of this elevated disclosure (stock-based compensation, for instance) displays a altering enterprise world and is merited, some is in response to a company scandal and if usually knee-jerk and a few, in my cynical vie, displays accounting making an attempt to be related to markets once more. Macro occasions: In years of market crises, financial or political, you will notice disclosures improve. Within the graphs above, discover the spikes in 2008/2009 and 2020, the primary in response to the 2008 banking disaster and the latter to COVID. Superimposing the consequences of globalization, the place an organization finds itself uncovered to issues in each nook of the world, it has added to the disclosure bloat.Authorized Safety: One of many culprits accountable for disclosures bulk is the chance publicity part, the place corporations are required lay out an exhaustive (and exhausting) record of issues that may go incorrect of their enterprise fashions. I’ve by no means discovered a danger disclosure helpful in a valuation, because it appears to be written by legal professionals with the target of offering authorized cowl.Steering: Within the Nineteen Eighties, quarterly earnings experiences had been targeted on reporting on operations throughout the quarter in query and administration was not anticipated to, and didn’t present, steerage about future quarters. That began to alter within the Nineteen Nineties, particularly with the passage of the 1995 Protected Harbor Legislation and Reg FD (which prevented corporations from selectively leaking data to analysts), and surged by the second half of the last decade, peaking in 2003, when greater than 50% of all corporations offering earnings steerage. Fortunately, the method has receded, with solely a fifth of all companies now offering steerage with earnings experiences, however it’s simple that there’s rather more forward-looking elements to earnings experiences than was the case.The bulking up of earnings experiences is a part of a phenomena that I time period “disclosure diarrhea” and argue has undercut the usefulness of those experiences, with extra disclosure perversely making for much less data.The Earnings Recreation To make sense of the arguments for and towards quarterly earnings reporting, you must get a measure of what occurs main into and out of those experiences, within the “earnings sport”. The method begins with analysts and traders making forecasts of what the earnings report will include, virtually all the time together with estimates of the earnings per share, however usually additionally containing estimates of anticipated revenues and even working metrics (like margins) for top profile corporations. The analyst forecasts, at the very least from promote facet analysts, turn out to be quasi public data and are sometimes aggregated and reported as consensus estimates by monetary information companies. Zacks, as an illustration, is among the companies that has been doing this for many years, however that data is now broadly accessible on Google and Yahoo! Finance (with the estimates for Apple on July 27, 2026, for the September 2026 earnings report, proven beneath):These analyst forecasts, as soon as made, are revisited, partly in response to company-specific information tales and partly to macroeconomic developments, and revised forecasts are supplied, with companies once more monitoring these revisions for tendencies (as you possibly can see beneath for Apple, from Zack’s):Because the earnings launch date approaches, analysts proceed to revise their estimates, and on the date of the announcement, the precise earnings per share is in comparison with the anticipated quantity, with greater (decrease) than anticipated earnings labeled as constructive (damaging) surprises. The market value response is usually constant, with constructive (damaging) earnings surprises translating into will increase (decreases) in inventory value. The graph beneath, whereas dated, appears at inventory value responses to earnings shocked categorised into ten deciles (from most constructive to most damaging):There may be some proof that the market responses to earnings experiences have turn out to be extra muted over time, maybe due to public entry to analyst forecasts and revisions. The hyperlink between earnings surprises and inventory value adjustments has turn out to be the explanation why analysts spend as a lot time as they do, forecasting earnings per share within the subsequent quarterly report, and why merchants specializing in the identical metric. There may be one other side of the market response to earnings surprises that turns into grist for the buying and selling mill, and it comes from the value drifts within the days after earnings are launched, with constructive (damaging) surprises adopted by upward (downward) drifts. Whereas the value drift is small, it might nonetheless be giant sufficient to make a distinction in lively buying and selling, the place profitable by inches remains to be profitable. As with virtually every thing else that’s market-related, there aren’t any simple wins on this sport, and as increasingly individuals play the earnings forecasting sport, new wrinkles have emerged. First, corporations have discovered to make use of the pliability embedded in accounting guidelines to search out methods to beat analyst estimates, with tech corporations, specifically, standing out. That earnings gaming performs out as a disproportionately giant variety of constructive earnings surprises (at the very least among the many S&P 500 corporations, damaged down by sector), as is obvious from earnings surprises on the S&P 500 corporations within the second quarter of 2026:Second, as corporations routinely beat analyst estimates, markets readjust, creating the phenomenon of whispered earnings, the place traders construct within the expectation that an organization that has traditionally delivered earnings which can be 5% or 10% above estimates will proceed to take action, and a lesser quantity is a damaging shock. Within the graph beneath, I have a look at the market value response to earnings surprises within the second quarter of 2026:As you possibly can see, the linkage between earnings surprises and value response is weak, with a big subset of constructive surprises leading to value drops. The Backside Line A lot of the controversy about whether or not the US ought to shift away from quarterly to semi-annual experiences will be boiled right down to what you consider the time and power traders and corporations spend enjoying the earnings sport, and the place that point and power will probably be spent within the absence of quarterly experiences. Those that are advocates for much less frequent reporting are of the view that the earnings sport, targeted as it’s on subsequent quarter’s earnings estimates and whether or not the corporate can beat them, contributes to short-termism and distracts from fundamentals. Those that are pushing for preserving the established order (of quarterly reporting) imagine that eradicating quarterly experiences will simply shift the sport, maybe extra intensively, into the semi-annual experiences and that there’s worth to long run traders from having quarterly experiences, gaming however. There may be one other situation that comes up within the context of quarterly reporting, and what would occur if these experiences didn’t exist. Authorized strictures however, insiders (from inside and out of doors the agency) commerce and become profitable on materials data that they’ve entry to, however the public doesn’t. Eradicating quarterly reporting will create extra of a gap for insiders to become profitable on the expense of public market traders, and whereas inside buying and selling might contribute to creating costs extra informative, it additionally provides to the sense that monetary markets are an unfair sport. I’m an investor, and I suppose that there’s a compromise resolution that pulls on each side of this argument. I like quarterly reporting for 2 causes. There may be data in these experiences that permits me to replace my firm valuations, although for a lot of corporations, the marginal affect of a quarterly report on worth is small. Whereas I’ve no real interest in enjoying the earnings sport, the value corrections that occur round earnings experiences serve two functions. For corporations that I’ve a place in, they will function as catalysts, bringing down (up) the inventory value of over valued (below valued) corporations. On the similar time, virtually all the data that I discover helpful in an earnings experiences is within the monetary statements and footnotes, not within the prolonged discussions of danger publicity or within the administration steerage, and I’d welcome an elimination of those sections and a slimming down of those experiences. Word that none of my arguments for preserving quarterly reporting are about short-termism, and that’s intentional. First, I’m not certain what short-termism even means, for the reason that cynical reply appears to be that any market motion away out of your most well-liked value path is brief time period, and any motion in your favor is indicative of market knowledge. Second, I imagine that almost all market contributors, and that is true throughout time and markets, commerce to become profitable within the close to time period, and that there’s nothing that regulators or rule writers can do to change this dynamic. In actual fact, the magic of markets is that hundreds of thousands of trades motivated by opportunism and the quick time period can nonetheless yield a value that’s long run and rational. Lastly, it stays true that if we had been all long-term traders who traded solely when the basics drove us to take action, markets could be much less liquid and transactions prices would improve; quick time period merchants present a market service and provide liquidity that all of us (together with long run traders) profit from. I hope that the SEC preserves the present quarterly reporting requirement, whereas scaling again the quantity of disclosure, but when it decides in any other case, it is not going to materially change a lot of what I do. I’ll miss the quarterly updates extra with youthful, higher-growth companies, the place the working metrics (revenues, margins and many others.) can change rapidly over quick durations, however it’s my guess that many of those companies will voluntarily proceed the quarterly reporting custom. Fed Steering on Charges For many traders who began investing after 2008, the Fed, specifically, and central banks, typically, have loomed giant within the investing course of. Many traders attribute the low rates of interest after 2008 virtually completely to Fed actions, and by extension, blame the Fed for the upper charges since 2022. I’ve lengthy argued that not solely is that this notion incorrect, however that it’s unhealthy for traders to view the Fed as both savior or villain. A Brief (and Private) Historical past of the Fed I began in fairness markets within the Nineteen Eighties, when Paul Volcker because the chair of the Fed performed a central function in getting inflation again into verify. I might need been ignorant, however I didn’t know the names of any of the members of the Federal Open Market Committee and had no thought after they met. Adjustments within the fed funds price, the one price successfully managed by the FOMC, would percolate their method into markets, however I do not bear in mind them being central to fairness market actions. Volcker was adopted by Alan Greenspan, and whereas he acquired rockstar standing (at the very least amongst traders) within the late Nineteen Nineties, his views on charges had been outmoded by his views on fairness traders (and their irrational exuberance). The FOMC met eight instances per yr throughout that interval, and you may entry the assembly minutes and actions on the Fed web site right here, but it surely stayed away from specific steerage about future price adjustments, selecting to ship delicate hints as a substitute. The ocean change in Fed conduct and centrality occurred with the 2008 market disaster, when the Fed first launched specific steerage noting that charges would keep low “for a while”, and it has largely continued that apply by the stewardships of Bernanke (2006-2014), Yellen (2014-2020) and Powell (2020-2026). Alongside the way in which, its place in markets has modified, as each bond and fairness traders have turn out to be targeted on the Fed because the arbiter of rates of interest and director of the economic system. The Fed’s Powers (and Powerlessness) To know the extent and limits of the Fed’s capability to information charges and the economic system, it’s helpful to start with an understanding of what it does. Via its twelve districts that span america, the Fed collects data on virtually each side of the economic system, from value pressures constructing on shoppers and producers to the tempo of financial progress. Whereas there are different authorities businesses that additionally monitor these statistics, it’s simple that the Fed has a giant image view and entry to extra information than another authorities company. The Federal Open Market Committee, composed of all the members of the board of governors and representatives of the district presidents, units Fed coverage on open market operations (the place the Fed buys and sells US authorities securities), the dimensions of the Fed’s steadiness sheet and the Fed Funds price (an in a single day price at which banks can borrow and lend their reserves). Along with the FOMC offering coverage path on inflation and the economic system, the Fed chair testifies to Congress each six months, going through and answering questions from legislators. As the important thing rate of interest set by the Fed, the Fed Funds price usually acquires an outsized function and there are good causes to concentrate to it. First, it operates as a sign of what the Fed is seeing within the information it has collected on the economic system, with a rise (lower) in charges indicating that it sees greater (decrease) inflation and an overheated (slowing) economic system. Second, there are rates of interest which can be immediately tied to the Fed Funds price, the place adjustments percolate right down to companies and clients; the prime price and a few bank card and CD charges transfer with the Fed Funds price. That mentioned, I imagine that Fed’s capability to have an effect on rates of interest is much extra restricted than most imagine, for 2 causes. First, whereas there may be constructive correlation between Fed Funds charges and short-term market-set charges (just like the US treasury invoice price), there may be as a lot proof (if no more) that the latter lead the previous, moderately than the opposite method round. Put merely, Fed funds charges are usually elevated (minimize) after quick time period treasury charges have gone up (down), suggesting that the Fed is mimicking the market. Second, the connection between Fed Funds charges and long-term market-set charges, which drive asset valuation and have an effect on debtors extra, is even weaker. To again these contentions, I chart the efficient fund funds price, the three-month US treasury invoice price and the 10-year treasury word price on a month-to-month foundation from January 1962 to June 2026:On the backside of the graph, I’ve a desk the place I have a look at the info on a quarterly foundation, and break it down into three teams – quarters the place the fed funds price decreased, quarters the place it elevated and quarters the place it stayed unchanged. With each fed funds price will increase and reduces, you possibly can see that the hyperlink with quick time period charges is stronger, and with each quick time period and long run charges, the majority of the change in charges occurs previous to or within the quarter that the Fed Funds price modified, however there may be solely a light spill over into the quarter after, with three month charges, and virtually no spillover, with long run charges. Put merely, baed on this historical past, it appears like adjustments in fed funds price are much less indicators of future actions in rates of interest and extra reflectors of adjustments which have already occurred. The Fed’s weaknesses in setting rates of interest additionally performs out in its capability to change the trajectory of the true economic system. Whereas there are clearly durations which you can level to the place Fed actions have had a fabric affect on he economic system, with the Fed Fund price was hiked to twenty% below Paul Volcker in 1981, and triggering a deep recession, being a major instance, the hyperlink between Fed Fund charges and financial progress stays tenuous. Within the graph beneath, I have a look at the adjustments in Fed Funds charges and actual GDP progress within the quarter main into, the quarter of and the quarter after the change:Once more, there may be little backing for standard knowledge, which is that fed tightening (by elevating the Fed funds price) results in drops in actual progress (and even recessions) and that fed loosening (by decreasing the Fed funds price) is a sign of upper financial progress sooner or later. In actual fact, the extra common conclusion that one can draw from the info is that the fed impact on the true economic system has been extra “meh” than “wow”. The hole between investor notion on what the Fed can management on rates of interest and the economic system and its precise powers is not only vast, however probably harmful. From a coverage perspective, it could possibly result in perverse actions, the place central banks are pressured to decrease the charges they management (just like the Fed Funds price) within the face of excessive inflation, resulting in even greater inflation sooner or later. From an investor and enterprise perspective, the deal with what the Fed is doing or will do can take consideration away from the basics, particularly inflation, that finally drive each rates of interest and progress.As you possibly can see, a lot of the variation in long run rates of interest (with the ten-year US treasury price standing in as proxy) will be defined by actions in inflation and actual financial progress over time, not Fed motion or inaction.The Warsh Doctrine? All Fed chairs have needed to wrestle with the issue of being perceived as omnipotent, when their true powers are restricted, however Kevin Warsh is probably extra uncovered than any of his predecessors. The market fixation with the Fed is now deeply embedded in market, and there are politicians on each side of the aisle who appear to suppose that Warsh can carry charges (mortgage, treasury) right down to 2% or decrease, if he so needs, when the reality is that with inflation expectations working at 2.5-3%, there isn’t any probability of that occuring. The pathway out of this downside will probably be lengthy and there will probably be pushback, however the finish sport needs to be a world the place you see and listen to from the Fed much less, no more. I do imagine that the choice to cut back or withhold steerage is an efficient first step, and it must be adopted by extra open humility from the Fed (and from Warsh) in regards to the limits of its powers and honesty about how continuously it follows markets, moderately than leads them. Within the context of at this time’s (July 29, 2026) resolution by the FOMC to go away charges unchanged, as an illustration, the subtext is that whereas inflation is working hotter than desired (3% or extra, versus the focused variety of 2%), a lot of that inflation is being pushed by a battle and its impact on oil costs There will probably be some who really feel that markets will probably be misplaced with out Fed steerage, however I do not suppose so. In any case, monetary markets set rates of interest and inventory costs earlier than the steerage period, and did a fairly good job. In actual fact, I feel that the surge in steerage from the Fed has led many in markets to abdicate their duty for paying heed to fundamentals and gauging what rates of interest needs to be. Conclusion If there’s a takeaway from this put up, it needs to be that there’s nothing inherently good about having extra disclosure. In actual fact, there’s a tipping level, the place data overload could cause traders to behave in perverse methods. Thus, I’m much less of an absolutist in regards to the quarterly versus semi-annual reporting debate than some, although my view is that moderately than cut back the frequency of reporting, the SEC needs to be slimming down experiences, by changing one-size-fits-all disclosure necessities with focused disclosures and retaining the deal with reporting what has occurred moderately than prognosticate in regards to the future. With the Federal Reserve too, I feel much less is extra is a greater technique – much less steerage from the Fed about what it is going to do sooner or later, much less opining from FOMC members about rates of interest and the economic system and fewer consideration to FOMC conferences and the smoke indicators that emerge from these conferences. Markets will step in to fill the vacuum, and that’s good not only for traders however for the Fed, since its choices are knowledgeable by these market judgments.YouTube VideoData
Musings on Markets: Info Timing and Launch: The Gaming of Steering!