Marzio Bassanin
The 2017 finalisation bundle of the Basel III reforms to financial institution capital regulation goals to make capital necessities extra strong and constant throughout banks. Certainly one of its most vital adjustments is the introduction of the ‘output flooring’, which limits how far capital necessities calculated utilizing inside fashions can fall beneath these primarily based on standardised approaches. However the output flooring isn’t just about capital ranges. We discover that it might tilt lending in the direction of company loans and a few riskier mortgages, and away from the most secure mortgages. And if banks’ responses to previous reforms are any information, banks received’t wait till its full implementation in 2030 to begin reacting.
What’s the output flooring?
The Basel framework for financial institution capital regulation goals to align capital necessities with dangers: banks ought to maintain extra capital towards riskier property. The framework does this via threat weights, which decide how a lot capital banks should keep towards several types of lending for their very own security and soundness and to make sure monetary stability. As a result of capital is dear, adjustments in threat weights can have an effect on which loans banks discover most engaging. Throughout banks, selections about which property to carry can, in mixture, have an effect on the kind of credit score equipped, together with higher-risk loans that help productive funding, in addition to the prices of that credit score.
Banks can estimate threat weights utilizing permitted inside fashions or apply standardised approaches set by regulators. The case for inside fashions is that banks with the suitable experience and capabilities are sometimes greatest locations to evaluate the dangers on their steadiness sheets. Inner fashions allow them to flip detailed details about their debtors, such because the likelihood that they default and the losses that will comply with, into estimates of dangers. However inside fashions have lengthy raised concern: they will generate completely different threat weights for portfolios that look comparable by way of the underlining dangers. This isn’t only a theoretical concern – empirical research have proven it. That type of variability raised questions on how strong the system actually is.
The 2017 Basel III finalisation bundle responded with the output flooring, a backstop that limits how a lot banks can cut back risk-weighted property (RWAs) utilizing inside fashions. Beneath the output flooring, banks’ RWAs can not fall beneath 72.5% of these implied by the standardised approaches. When inside fashions generate decrease RWAs, the output flooring turns into binding. In Chart 1, the RWAs calculated utilizing inside fashions (inexperienced bar) fall beneath the ground and due to this fact are changed by the 72.5% of these calculated with standardised approaches (blue bar, proper). By underpinning inside fashions with a typical benchmark, the output flooring goals to cut back unwarranted variations in RWAs throughout banks with comparable portfolios.
Chart 1: The output flooring at work
Standardised approaches aren’t excellent – they apply fastened threat weights which have comparatively restricted risk-sensitivity – however they do provide one thing fashions usually battle to ship: consistency. As a result of these weights are set by regulators and utilized the identical solution to all banks in every jurisdiction, they assist cut back unwarranted dispersion in capital necessities.
The output flooring received’t chunk suddenly. Within the UK, it will likely be phased in progressively from 1 January 2027, beginning at 60% and rising to 72.5% on 1 January 2030. As the ground approaches its closing stage, it’s anticipated to develop into a binding constraint for extra banks – particularly these with concentrated exposures to property the place the hole between internally modelled and standardised RWAs is largest – shaping how they measure and handle dangers.
This put up examines the incentives created by the output flooring. However banks don’t function underneath a single regulatory constraint. In addition they face a leverage ratio, a easy risk-insensitive backstop primarily based on capital and complete exposures. Their selections will replicate which constraint dominates. Our findings converse extra to these banks that aren’t constrained by the leverage ratio.
How are banks anticipated to react when the output flooring is absolutely applied?
In a brand new Financial institution of England workers working paper – Acosta-Smith et al (2026) – we examine how banks are probably to reply to the implementation of the output flooring over the cycle. To discover these results, we use an extension of the macroeconomic mannequin developed by Angelini et al (2014) which options banks that lend to households via mortgages and to nonfinancial corporates. We evaluate two regulatory regimes: one primarily based solely on internally modelled threat weights (RWs) and one other that includes the output flooring.
We simulate an financial growth pushed by a optimistic expertise shock. Ends in Chart 2 recommend that the output flooring moderates the rise within the credit-to-GDP ratio throughout financial expansions by stopping RWAs from falling too far therefore preserving capital necessities tighter.
Chart 2: RWAs, credit-to-GDP and lending
Notes: The chart compares the impulse responses capabilities (deviation from the regular state values – share level deviation for RWAs and credit-to-GDP, per cent deviation for mortgages and company loans) to a optimistic expertise shock with and with out the output flooring. After the shock, each mortgages and company loans enhance however the magnitude depends upon the prudential framework in place. With the output flooring, the rise in mortgages is milder – on the finish of the simulation interval mortgages are 0.4 share level decrease – whereas the rise within the company loans increased – round 0.2 share level increased. Variations appear to be persistent over the simulation interval.
Chart 2 additionally reveals how the introduction of the output flooring impacts banks’ allocation of lending. When the output flooring is in place and it turns into binding, banks increase company lending greater than mortgages relative to the regime primarily based solely on inside fashions.
The important thing driver is the hole between internally modelled and standardised threat weights (IM-SA hole) and the way the scale of this hole varies throughout completely different asset lessons. Standardised threat weights are typically increased than these produced by internally modelled ones, however the dimension of the IM-SA hole varies significantly throughout asset lessons. Belongings with a big IM-SA hole see the largest enhance in capital necessities (as a result of the output flooring is increased than modelled RWs). Against this, property with a small hole are affected a lot much less and, in some case, the required regulatory capital diminished (as a result of the output flooring is the same as or decrease than modelled RWs).
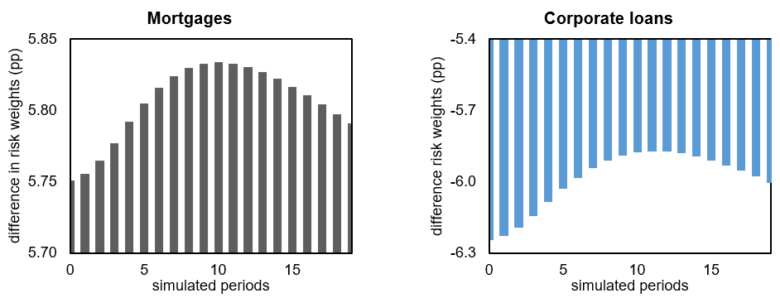
For UK banks, information show that mortgages are inclined to have decrease RWAs than company loans however have a bigger IM–SA hole – so the output flooring is usually extra binding for mortgages than for company loans. Chart 3 illustrates the implications: over the simulated interval, the output floor-implied threat weights (72.5% of standardised RWs) are increased than the internally modelled threat weights for mortgages, however decrease for company loans. Because of this, as soon as the output flooring binds, mortgages develop into extra ‘costly’ by way of capital necessities, whereas company loans develop into ‘cheaper’. Banks due to this fact are incentivised to increase extra company loans than mortgages, to mitigate the prices of the output flooring.
Chart 3: Belongings’ contributions to capital necessities
Notes: The chart stories the distinction (in share factors) between the output flooring implied threat weight (72.5% * SA threat weight) and the SA threat weight over the simulation of a optimistic expertise shock. The distinction is optimistic for mortgages and unfavourable for corporates loans, which means that the previous develop into dearer, whereas the latter cheaper for banks. The magnitude is increased for company loans in comparison with mortgages.
Fashions tidy up a world that’s something however tidy. Ours boils banks’ steadiness sheets down to simply two asset varieties. However mortgages, as an example, span an enormous vary of dangers. Greater IM–SA gaps have a tendency to indicate up for safer mortgages, whereas smaller gaps level to riskier ones. Put merely, when you drop this again into the actual world, the output flooring is predicted to push UK banks in the direction of riskier mortgages and company loans and away from the most secure mortgages – assuming every part else fixed.
What can we are saying at the moment about banks’ reactions?
The output flooring received’t absolutely take impact till 2030. However that doesn’t imply banks which can see the output flooring binding in 2030 will wait till then to react. Whether or not we see early behavioural adjustments depends upon how a lot banks anticipate the longer term regime – and historical past suggests they usually transfer properly earlier than formal implementation.
A examine by Fritsch and Siedlarek (2022) on the Federal Reserve Financial institution of Cleveland seems again on the Basel III reforms. They discover that banks began adjusting their regulatory capital positions shortly after the proposed guidelines have been introduced in 2012. That was years earlier than the brand new regime truly got here into pressure. They discover that the impact was particularly clear for US regional banks, that are usually extra delicate to supervisory scrutiny and have stronger incentives to remain comfortably above regulatory thresholds.
Early reactions aren’t restricted to capital ratios. Hendricks et al (2023) doc strategic adjustments in reporting, lobbying and enterprise fashions that diminished banks’ publicity to the proposed Basel III guidelines earlier than they have been finalised. And a distinct coverage change, Guillaume et al (2020) show that UK banks eligible for Pillar 2A capital aid began altering their asset composition after the related coverage assertion was revealed, not when the aid formally utilized.
Taken collectively, these research recommend a transparent sample: when regulatory guidelines change however will not be but in impact, banks are inclined to react early.
What can we conclude?
As soon as the output flooring is absolutely in place, banks are more likely to rebalance their portfolios in the direction of company loans and a few riskier mortgages, and away from the most secure mortgages. All else equal, these incentives level in the direction of a reallocation of credit score towards comparatively higher-risk finance that will help productive funding.
Previous expertise means that banks won’t wait till the output flooring is absolutely applied in 2030 to reply. Banks almost certainly to be affected by the output flooring could already be adapting their methods, with early indicators of portfolio shifting rising properly earlier than 2030. That makes this an space the place well timed empirical work might add actual worth.
As we famous at first, the put up units apart the leverage ratio, the opposite backstop sitting alongside risk-weighted capital guidelines. A pure subsequent step for future analysis shall be to check whether or not a binding leverage ratio dampens the affect of the output flooring.
Marzio Bassanin works within the Financial institution’s Prudential Framework Division.
If you wish to get in contact, please e mail us at bankunderground@bankofengland.co.uk or go away a remark beneath.
Feedback will solely seem as soon as permitted by a moderator, and are solely revealed the place a full title is equipped. Financial institution Underground is a weblog for Financial institution of England workers to share views that problem – or help – prevailing coverage orthodoxies. The views expressed listed here are these of the authors, and will not be essentially these of the Financial institution of England, or its coverage committees.
Share the put up “When the ground rises: how Basel output flooring might tilt financial institution lending”