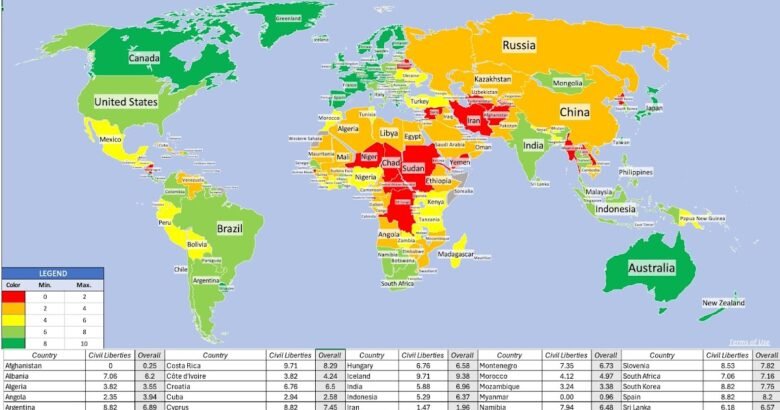
I’m a creature of behavior in my private {and professional} life, and within the context of the content material that I submit on-line, there’s a ritual that I comply with with my knowledge updates. I begin the yr with my normal knowledge replace on-line, and comply with up with a sequence of posts the place I study the implications of this knowledge for investing and company finance. Since 2008, I’ve additionally carried out annual replace papers on fairness danger premiums in March of every yr, with the hyperlink to the 2026 replace right here, and nation danger in July of every yr, the place I take a look at the subjects in additional particulars, making an attempt as finest as I can to combine the info, analysis and my very own pondering. This yr’s nation danger replace paper is now out there, and as in prior years, I’ll spend this submit wanting what causes danger to differ throughout international locations, learn how to measure these danger variations and the implications for companies and traders.Nation Threat: Relevance In my years as a enterprise college pupil, nation danger was given quick shrift and I do not bear in mind spending a lot time speaking or enthusiastic about it. A part of the rationale was that enterprise college schooling was dollar-centric and constructed on the presumption that the majority graduates would go to work in New York, London or Tokyo, and have little must confront nation danger on a day-to-day foundation. For many who raised nation danger as a problem, the response was that you possibly can, as an organization or investor with international publicity, diversify it away. Each presumptions have been flawed even then, and have grow to be much more flawed over time as we’ve got bought each firms and traders on the advantages of globalization. For companies, the publicity to nation danger comes from each the income aspect, as bigger parts of each firm’s revenues come from international markets, and the fee aspect, as manufacturing will get outsourced to locales abroad. That publicity tends to extend as firms scale up, and is larger in some sectors than others; expertise firms, for example, get way more of their revenues from different non-domestic markets than manufacturing or service companies. Outdoors of utilities (energy, water), it’s uncommon for an organization to be totally domestic-focused on each its income and price sides. For traders, the preliminary draw of investing in international markets may need been diversification however the higher pull has come from greed, i.e., the idea that you would be able to larger returns in the remainder of the world. That course of was accelerated by the creation of funding automobiles (index and mutual funds) that made investing abroad simpler, the decreasing of transactions prices throughout markets and a higher standardization of monetary statements and disclosure throughout the globe. The house bias in portfolios, i.e., the skewing of portfolios in the direction of home market investments, has not disappeared however it’s decrease than it was on the flip of the final century. The notion that nation danger is diversifiable, i.e., that if you’re working or investing internationally, the dangers will common out throughout international locations, has been undercut by the elevated correlation throughout international fairness markets, and particularly so throughout market crises (which is if you care probably the most). On the danger of being hyperbolic, there is no such thing as a place to cover from nation danger, for both companies or traders, and ignoring or dismissing nation danger will not be an possibility. I found this fact within the Nineteen Nineties, when I discovered myself in want of a mechanism to include nation danger into my company monetary evaluation and valuations, and the method that you simply see described on this submit was born from that want. I’d hasten so as to add that the method that I describe has little or no mental firepower behind it, places pragmatism forward of principle and most significantly is a work-in-process.Nation Threat: Drivers I do not suppose that there could be a lot disagreement, if I assert that it’s riskier to put money into some elements of the world than others, however there may be prone to be loads of disagreement on why there are danger variations and which elements of the world are riskiest. Within the broadest sense, I argue that variation in enterprise danger throughout international locations might be traced to 4 components – the political construction of the nation (democracy vs authoritarian), the prevalence of corruption within the nation (working as a hidden tax and distorting enterprise outcomes), the extent of violence within the nation (from inside and exterior forces) and the power of the authorized system in implementing property rights and contractual obligations. On the political danger entrance, I seemed on the EIU’s Democracy Index, a composite rating measuring each political freedom and protections of civil liberties, with the caveat that any index that tries to measure these will make subjective judgements that not everybody will agree with. Of their most up-to-date replace, here’s what the EIU scores seemed like around the globe:Supply: Economist Low (Excessive) rating: Least (Most) freedomBased on these scores, the lean in the direction of authoritarianism has elevated over the past decade, with solely 7.3% of the world’s inhabitants dwelling in democracies on the finish of 2025. Be aware, although, that there’s nonetheless an open query of whether or not companies and economies do higher beneath democratic than authoritarian regimes, and the reply within the analysis is at finest a “perhaps”. From a danger perspective, democratic regimes create extra steady danger for companies, with elections bringing regulatory and rule modifications to economies, than authoritarian regimes, the place governments can promise extra continuity in coverage, however when change does come to the latter, it’s extra prone to be giant and wrenching. Corruption is a truth of life in a lot of the world, and companies usually don’t have any alternative however to pay the value to outlive and develop. Transparency Worldwide, a world coalition in opposition to corruption, tries to seize the extent of corruption, comes up with corruption scores for international locations, with decrease scores indicating much less corruption, and the latest version incorporates the next:Supply: Transparency InternationalLow (Excessive) rating: Most (Least) corruptionNorthern Europe has the bottom corruption scores, adopted by Canada, United States and Australia, however giant parts of Africa have excessive publicity to corruption, with Latin America and far of Asia falling within the center. Dwelling within the midst of violence takes a toll, and that toll is extracted from companies that attempt to function in its presence. Imaginative and prescient of Humanity computes peace scores for international locations, measuring publicity to each violence throughout the nation in addition to from wars and terrorism. The latest peace scores are reported under:Supply: Imaginative and prescient of HumanityLow (Excessive) rating: Most (Least) peacefulCanada, Australia, Japan and far of Europe rating excessive on the peace dimension, and whereas Latin America and Africa rating decrease, there are parts of every continent which can be extra peaceable. The Russia-Ukraine warfare has created an enormous space of violence throughout Jap Europe and Russia, and publicity to gun violence creates a drag on the US. Companies are depending on the authorized system to implement property rights in addition to contractual obligations. Nations which have authorized techniques which can be both capricious on these fronts, or hopelessly sluggish in performing, create challenges for companies that function in them, creating each prices and dangers that they in any other case wouldn’t face. Property Rights Alliance is an entity that tracks worldwide property rights internationally, and of their most up-to-date replace, their property rights scores by nation are captured under:Supply: Worldwide Property RightsLow (Excessive) rating: Least (Most) property rightsThere are huge variations throughout areas, in relation to authorized and property rights, with Latin America, Africa and Asia lagging and Europe, Australia and far of North America main. There may be one ultimate dimension that I’ve added to nation danger lately that captures publicity to local weather danger. Whereas there are a lot of totally different entities that measure this publicity, every one with its personal skews, the map under which reveals the local weather danger publicity, by nation, from GermanWatch:Supply: GermanWatchLow (Excessive) rating: Least (Most) affectedThere are two the reason why local weather danger has not grow to be a much bigger subject in nation danger discussions. The primary is that there is no such thing as a a part of the globe that’s unaffected, making it much less of a differentiator throughout international locations on the chance dimension. The second is that local weather danger, by itself, is an abstraction for companies, till it begins affecting the underside line, and whereas there are particular person firms which can be being impacted, the mixture results, at the very least in the meanwhile, are usually not large enough to vary the dialogue. Nation Default Threat Whereas nation danger is decided by a number of components, the problem that companies is in consolidating all of these dangers into one quantity. The market that does this most immediately is the debt market, the place, when international locations (sovereigns) search to borrow cash, lenders decide the rates of interest to cost them, based mostly upon perceived default danger. To grasp why lenders fear about default with sovereign debt, you can begin by wanting on the historical past of sovereign defaults within the graph under:Supply: BoC & BoE Sovereign Default DatabaseDebt defaults, which soared within the Nineteen Eighties and Nineteen Nineties, have been decrease on this century, with a shift away from mortgage defaults (the place banks are often the lenders) to defaults within the bond market. It is usually price noting {that a} non-trivial portion of sovereign defaults in every year are native foreign money defaults, indicating that for some debtors, the prices of defaulting are seen as smaller than the prices of inflation arising from printing extra foreign money to repay debt. Over time, Latin America has been the epicenter for sovereign default, however on the finish of 2023, sovereign debt in default had a large geographical unfold:Supply: BoC & BoE Sovereign Default DatabaseThe most generally accessible measures of sovereign default danger stay sovereign scores, with scores businesses working as (imperfect) arbiters. At first of July 2026, the graph under stories the sovereign scores for all rated international locations, from S&P, Moody’s and Fitch:Supply: A number of public sourcesAs you’ll be able to see, the scores businesses largely agree on their assessments of default danger, and sovereign scores are correlated with the chance drivers (politics, corruption, violence, authorized system) that we outlined within the final part. I do consider that scores businesses, however the critiques of bias and mis-measurement leveled in opposition to them, do a fairly good job of their scores assessments, however they’re usually sluggish to behave, when confronted with change. The sovereign CDS market gives a market-based different for measuring sovereign default danger, with traders making assessments of how a lot they’d demand to insure in opposition to sovereign default within the type of (annualized) spreads. Within the graph under, I listing 10-year sovereign CDS spreads as of July 1, 2026:Supply: BloombergNote that sovereign CDS spreads can be found for under 84 international locations, and that there are swaths of the world (Central and North Africa, frontier markets) the place they aren’t out there. Nation Composite Threat While you lend cash to governments or purchase authorities bonds, sovereign default danger is your key concern, and each sovereign scores and CDS spreads attempt to measure that danger. When operating a enterprise in a rustic, you might be uncovered to a a lot wider vary of dangers, and measuring publicity to these dangers could require totally different measures. One different is nation danger scores, the place providers consider how international locations measure up on totally different danger drivers, and give you composite scores for these international locations. Within the desk under, I report the nation danger scores from two providers – Political Threat Providers (PRS) and the Economist (EIU), at first of July 2026:Sources: EIU (Economist) and PRSThe desk illustrates three issues that you simply face with political danger scores. The primary is that the scoring is idiosyncratic, with the Economist going from low scores for the most secure international locations to excessive scores for the riskiest, and PRS doing the reverse. The second is that every service picks various factors to contemplate, and totally different weightings, resulting in scoring divergences that generally confound; PRS, for example, ranks the US as riskier than Ghana, on a composite danger foundation. The third is that the scores, by themselves, are troublesome to transform into inputs in monetary evaluation, both in money stream or low cost price adjustment. It’s to fight the third drawback that I began estimating nation fairness danger premiums, and whereas the small print of the method and the info that I exploit have modified over the past three many years, the fundamental construction has remained unchanged. I begin with an estimate of the fairness danger premium for a mature market, and construct a rustic danger premium, if wanted, for riskier international locations. Till 2025, I estimated the mature market premium by computing an implied fairness danger premium for the S&P 500, and utilizing that as the bottom, arguing that the US, as a Aaa rated nation (at the very least in line with Moody’s), represented a mature market. The Moody’s downgrade for the US, from Aaa to Aa1, has thrown a wrench into that strategy, requiring adaptation. In response, I now begin with an estimate of the implied ERP for the S&P 500, however then modify that estimate for the default unfold (based mostly on the Aa1 ranking) for the US, with the ensuing values at first of July 2026 under:As you’ll be able to see, with the S&P 500 at 7499.36 on July 1, 2026, the implied fairness danger premium for the US is 4.42%, and netting out the default unfold of 0.22% for the Aa1 ranking yields a mature market premium of 4.20%. To estimate nation danger premiums, I begin with the sovereign scores for rated international locations and convert these scores into default spreads. To regulate for the upper danger related to equities, relative to authorities bonds, I estimate a composite measure of that relative danger, by scaling the volatility in an rising market fairness index to the volatility in a rising market authorities bond ETF, and scale the default danger up with this relative danger measure (1.55 in July 2026) to get nation danger premiums:For the 2 dozen international locations that don’t have any sovereign scores, I undertake an much more makeshift strategy, the place I used political danger scores for these international locations, after which seemed for rated international locations with related scores. The desk under has fairness and nation danger premiums, by nation, for the entire international locations that I evaluated in July 2026:I did submit an earlier model of this desk a few weeks in the past, however the numbers that I reported mirrored in incomplete replace of sovereign default spreads, and this desk (and the info on my webpage) now replicate the corrected (and decrease) spreads. (As a solo act, I’m deeply grateful for the checking that those that use my knowledge do, and grateful once they level out errors that I’ve made.)Firm Publicity to Nation Threat Should you purchase into my argument that each firm has a story, and it’s the narrative that drives its worth, it’s price contemplating the place nation danger matches into that narrative. The reply, I consider, comes from taking a look at the place the nation in query falls within the life cycle:The message from this life cycle view is a sobering one, particularly for these analyzing firms that function in very dangerous international locations, for the reason that narratives for these firms implicitly or explicitly incorporate a rustic danger part. You can not worth a Venezuelan firm with out taking a powerful view about Venezuela, and even an Indian and Brazilian firm with out an India or Brazil nation story underpinning worth. In distinction, you could possibly worth US and European firms, with out explicitly contemplating the evolution of nation danger in these elements of the world. When taking a look at a person firm, I consider that nation danger publicity comes much less from the place the corporate is included and extra from the place it operates. It’s simple that firms around the globe have substantial publicity exterior their home markets, and that publicity has elevated over time. Within the graph under, I take a look at the income breakdown of firms in 4 indices – the S&P 500 (US), the FTSE 100 (UK), the Nikkei 225 (Japan) and the Sensex (India): In each single index, firms that comprise that index get a good portion of their revenues from exterior the home market. Wanting throughout sectors, publicity to international markets varies broadly with expertise firms usually producing greater than half of their revenues exterior their home settings. I consider that fairness danger premiums for firms ought to replicate publicity to international markets, although it’s price debating how finest to weight that publicity – revenues work effectively for shopper product and repair firms, manufacturing works higher for pure useful resource firms and a mixture of revenues and manufacturing will be the proper alternative for manufacturing firms:With this framework, you’ll be able to see why virtually all analysts will confront nation danger, in the end, regardless of the place they function on the earth and which firms they analyze. For firms, nation danger may even come into play when confronted with capital budgeting choices, the place they want estimates of hurdle charges for particular person initiatives, to determine the place to speculate. For a multinational working in lots of companies, the venture value of fairness should then additionally replicate the enterprise the venture is in, along with nation danger. Thus, the price of fairness for a Siemens Home equipment for a venture in India ought to replicate the beta for the equipment enterprise, along with the nation danger for India. In distinction, a Siemens energy instrument venture in Hungary needs to be computed utilizing the beta for an energy instruments venture and the nation danger for Hungary. It is usually potential that nation danger will not be simple to isolate, if the manufacturing amenities are in a single nation however revenues are generated in one other. If the Siemens equipment manufacturing facility in India shall be producing merchandise that shall be bought in Japan, ought to we be displaying the nation danger of India or Japan in the price of fairness calculation? The reply, as was the case within the earlier part on valuation, is that it is determined by the place the corporate sees danger coming from. If the chance is that manufacturing shall be delayed or disrupted by political and financial danger in India, it’s Indian nation danger that needs to be checked out, but when the first concern is that revenues in Japan shall be unstable due to financial circumstances there, it’s Japanese nation danger that issues extra. If each dangers are issues, you need to use a weighted common of Indian and Japanese nation danger.Foreign money Questions For a few of you, it might appear odd that I’ve spent virtually a whole submit speaking about nation danger with out citing currencies. The reason being easy. Currencies are measurement mechanisms, and whereas they might be affected by the identical political and financial components that drive nation danger, they do not decide nation danger and in my opinion, mustn’t command danger premiums, on their very own. It’s true that hurdle charges are affected by each the fairness danger premiums that you simply estimate and the riskfree price that you simply use, and that riskfree charges differ throughout currencies. Within the determine under, I estimate riskfree charges in about 40 currencies, the place a local-currency authorities bond price is current, and I modify that authorities bond price for the default danger of the federal government in query:When estimating the price of fairness for a Turkish venture or firm in Turkish lira, we begin with a riskfree price in extra of 20% and construct on it, by including fairness danger premiums to it, however the price of fairness for a similar venture or firm in Euros will start with a riskfree price shut to three% (the German Euro bond price) and arrive at a a lot decrease quantity. Whereas this may occasionally sound farfetched, the worth that you simply derive for the venture or firm needs to be the identical utilizing both foreign money, if you’re constant about estimating your money flows in the identical foreign money:Since a lot or virtually the entire variations in riskfree charges come from inflation differentials, matching the excessive Turkish lira low cost price with a excessive development in cashflows in Turkish lira, and the low Euro low cost price with the low development in cashflows estimated in Euros will yield outcomes which can be constant. Should you do wish to estimate riskfree charges in currencies the place there may be both no native foreign money authorities bond that’s traded or the place you distrust the federal government bond price, due to gentle buying and selling or authorities intervention, the truth that riskfree price variations throughout currencies might be tied to differential inflation can be utilized for estimation; the riskfree price in any foreign money might be computed from a base foreign money (greenback or Euro) riskfree price and the distinction in anticipated inflation between the native and base currencies:Put merely, if the anticipated inflation price and riskfree price in US {dollars} are 2.5% and 4% respectively, and the anticipated inflation price in Brazil is 10.5%, the riskfree price in Brazilian reais needs to be roughly 12%. The implication of this strategy is that foreign money pegs, once they do exist, will maintain provided that the inflation within the pegged foreign money matches or is near the inflation within the index foreign money to which it’s pegged. It’s true that the estimates of riskfree charges will solely be nearly as good because the anticipated inflation charges which can be embedded within the estimation, however the excellent news is that being flawed on anticipated inflation shall be largely offsetting, since each your cashflows and your low cost charges shall be flawed in the identical path; when you underestimate anticipated inflation, you’ll underestimate (overestimate) your riskfree and hurdle charges, however additionally, you will underestimate (overestimate) your anticipated development price in money flows.Conclusion One of many negative effects of the rise of globalization is that there are fewer and fewer firms which can be totally local-country targeted in each their revenues and manufacturing, and in consequence, virtually each enterprise and investor is uncovered to danger in different elements of the world. The issue with measuring nation danger is that whereas its penalties are financial, it has its sources in historical past, politics and governance constructions. The measures of nation danger, whether or not they be entity-based like sovereign scores, or market estimates like sovereign CDS spreads, replicate this interaction. I confess that I’ve made simplistic assumptions and lower corners in my try and estimate fairness danger premiums, by nation, and there shall be particular person international locations, even perhaps your personal, the place you would possibly disagree with my assessments. As I famous earlier, my estimation strategy stays a work-in-progress and I’m all the time open to solutions on learn how to estimate these premiums higher, however remember that no matter these enhancements could also be, they should work throughout 180 international locations. YouTube VideoPapers on nation danger and fairness danger premiumsDataSpreadsheet
Musings on Markets: Nation Threat: Drivers, Measures and Funding Implications