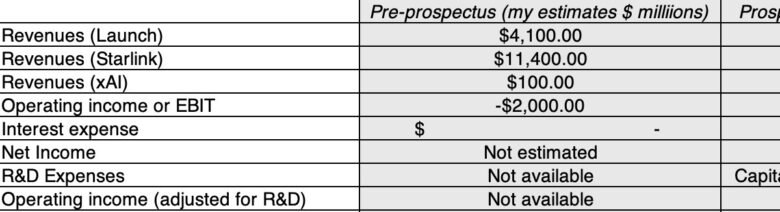
The prospectus additionally lays naked the governance questions that may overhang the agency, with data that there will likely be two lessons of shares- 6,932 million class A shares with one vote per share and 5,602 million class B shares with ten votes per share. The general public providing will likely be class A shares, and with Elon Musk holding the entire class B shares, he’ll management greater than 85% of the voting rights within the firm. In abstract, the prospectus is lengthy and full of distractions, however there may be virtually nothing in it that surprises me. SpaceX is a rising firm that’s money-losing and cash-burning, that will likely be a Elon Musk automobile (with all of the pluses and minuses that entails). The Prospectus: Story replace In my unique put up, I famous that SpaceX is an organization, the place it’s the story about how its companies will evolve over time that drives worth, somewhat than the bottom 12 months numbers (on revenues, earnings and money flows). That story, broadly talking, has three key spokes to it and they’re summarized beneath:The primary of those spokes, goal revenues, body how huge every enterprise can develop over time, and is a perform of the full market and market share. The second, the goal working margin, will seize how worthwhile every enterprise can turn out to be, and is set by unit economics and economies of scale. The third, reinvestment, measures how a lot every enterprise has to speculate to get to focus on revenues, and can range with the capital depth of the enterprise. To border how my valuation will change, because of what I discovered from wanting on the prospectus, I’ll begin by presenting by pre-prospectus estimates on these key inputs, after which take a look at the impression of the prospectus on every enter.Pre-prospectus inputs and worth My pre-prospectus valuation of SpaceX accommodates my storyline for the three companies that the corporate is in, with an add-on for the enlargement choices embedded in every enterprise:With these inputs in place, I estimated a worth of $1.2 trillion the SpaceX enterprise, and since I ignored money and debt, this yielded an equal market worth. Driving these numbers are upbeat tales about every of the three companies that SpaceX is in, with giant revenues and excessive margins in secure progress.The Prospectus Impact To the extent that the prospectus accommodates data that alters the storylines on all or any of those companies, it’ll have an effect on my estimate of worth for SpaceX.1. Income Progress (Goal Revenues) I’ll begin with the expansion (goal revenues) enter and use two elements of the prospectus to reexamine my story. The primary is the historic progress reported by the corporate for every of its three enterprise traces – launch, connectivity and AI.As you may see, the corporate noticed its revenues develop by a 3rd in 2025, relative to 2024, with divergence throughout companies; the connectivity enterprise led with revenues rising by virtually 50%, the AI enterprise noticed a rise in revenues of about 22% however the area enterprise reported solely modest progress within the 12 months (7.64%). In brief, however the star function performed by AI and the enchantment of the rockets within the area launch enterprise, it’s Starlink that carried the corporate in 2025. The prospectus mentions Colossus, xAI’s compute heart, which has been leased to Anthropic for an eye-popping $1.25 billion a month, which ought to kickstart revenues subsequent 12 months, with the potential of stress in future years if xAI plans to go head-to-head towards Anthropic within the AI merchandise market. The opposite related part of the prospectus contained estimates of whole addressable market (TAM) for the corporate, damaged down by enterprise:If the prospectus is to be believed, SpaceX has the most important TAM of any firm in historical past, with a complete TAM of $28 trillion, and AI accounts for $26 trillion of that market estimate. This estimate borders on fantasy, however I’ll lower the bankers who got here up with these numbers some slack for 2 causes. First, the estimation of TAM has been gamified by Silicon Valley, with bloated and patently unreachable numbers floated for corporations, as I famous after I valued Uber (which was given a TAM of $5.7 trillion in its prospectus) for its IPO in 2019 and Airbnb (with a TAM of $3.4 trillion in its prospectus) in 2020. Second, it’s true that AI brokers are usable throughout virtually each enterprise and geography, giving it a lot wider attain than most services, and whereas the main points of how the TAM was estimated will not be specified within the prospectus, my guess is that the $26 trillion estimate consists of all or a lot of the working bills of all companies. Story takeaway: I’ll keep on with my estimates for goal markets for the area launch and connectivity companies, for the reason that TAMs within the prospectus are, in my opinion, over reaches, and I’ll sluggish progress within the close to years, to replicate that these companies will take time to mature. Within the AI enterprise, I disagree with the magnitude of the TAM within the prospectus, however the acquisition of Cursor and the indications within the prospectus counsel that xAI very a lot desires to be a part of the enterprise options area, however its immense capitalization wants, and I’ll double my goal revenues for AI from $80 billion to $160 billion, reflecting my estimate of a TAM of about $3 trillion to $4 trillion for AI services from companies.The area enterprise has the most effective unit economics of the three enterprise, with a gross margin of about 67%, reflecting the associated fee benefits of its reusable rocket know-how. Whereas the area enterprise reported an working loss, that was solely due to its weighty R&D bills, and capitalizing these bills leads to a wholesome working margin for the enterprise.The connectivity enterprise doesn’t have gross margins as excessive because the area enterprise, however these gross margins are bettering, with gross margins leaping from 37% in 2024 to 48% in 2025. This enterprise had optimistic working earnings in 2025, even earlier than capitalizing R&D, and improves considerably with capitalization. The AI enterprise not solely has the bottom gross margins of the three companies, however noticed deterioration of these margins in 2025, reflecting intense competitors from different LLMs in addition to the rising prices of delivering AI services.There are different elements of the prospectus that come into play within the profitability dialogue, with every of the companies:On the area launch enterprise, the price of launching payloads at SpaceX have been trending down, making its already giant value benefits within the enterprise even bigger. On the connectivity companies, there may be unhealthy information and excellent news on the per person entrance. The unhealthy information is that the revenues, per 30 days, per subscriber, declined from $99 in month-to-month revenues in 2024 to $66 in month-to-month revenues within the first quarter of 2026. The excellent news is that the variety of subscribers has doubled from 5 million within the first quarter of 2025 to 10.3 million within the first quarter of 2026, with the bonus that the corporate has been capable of enhance its profitability (see gross margins within the desk above) over time. On the AI enterprise, there may be not a lot to go on, on the profitability entrance, for the reason that focus within the prospectus is extra on the rise in compute capability (see nameplate compute draw on Web page 90 of the prospectus) than it’s on revenues, particularly on the enterprise entrance. Right here once more, although, the Colossus lease with Anthropic ought to assist with profitability within the close to time period.Story takeaway: The unit economics for the area companies, together with the popularity that there aren’t any different substantial working bills (exterior of the misclassified R&D expense) in both enterprise, lead me to extend my estimate of the goal margin for the enterprise to 45%, from 40%. I’ll depart intact the goal margin of 60% for the connectivity enterprise, as a result of as soon as the satellites that service this enterprise are in area, that is the enterprise that may profit essentially the most from scale. My largest shift is in my estimated goal margin is for the AI enterprise, the place the dynamics which might be pushing gross margins down, i.e., elevated competitors and excessive prices of delivering AI providers, will persist; my estimated working margin drops from 45% to 25%.3. Reinvestment In my put up previous to accessing the prospectus, I did describe SpaceX as a capital intensive enterprise, however the precise spending on capital expenditures and R&D within the prospectus is breathtaking in its magnitude:In 2025, the corporate spent virtually $14 billion in capital expenditures and virtually $9 billion in R&D, a doubling of its reinvestment from 2024. Specifically, it’s AI that’s driving the majority of this surge, accounting for greater than $14 billion in whole reinvestment in 2025, with $9.1 billion in capital expenditures and $5.1 billion in R&D. The optimistic twist {that a} SpaceX optimist would placed on these numbers is that the spending on AI particularly is a optimistic, indicating that the corporate will not be planning to decide on a distinct segment market technique, however as a substitute will will go head-to-head with Anthropic, Google and OpenAI for the enterprise options markets. The damaging spin is that this bold agenda will translate into tens of billions extra in capital expenditures within the close to years, making a drag on the money flows and worth destruction in the event that they lose the AI market competitors.Story takeaway: Provided that SpaceX is constant to speculate substantial quantities in its area launch and connectivity companies, I’ll enhance reinvestment within the close to time period (years 1-5) by decreasing how a lot they are going to generate as extra revenues for each extra greenback of capital invested (decrease gross sales to capital ratios). With AI, the place I used to be already assuming that reinvestment could be giant (with a low gross sales to capital ratio), the tripling of goal revenues will end in a surge in reinvestment to generate the upper gross sales.Updating Story and Worth Whereas the core story of SpaceX being an organization with progress potential and powerful aggressive benefits that I framed previous to studying the prospectus stays intact, there are adjustments to that story that come from the data within the prospectus. The prospectus reinforces the notions that the corporate is greatest positioned within the connectivity enterprise to generate each income progress and earnings within the close to time period, that its value benefits within the area launch enterprise will persist and ship earnings, however that focus on market will likely be slower to develop, and that the AI enterprise has each the most important goal market and poses the most important challenges, by way of profitability and capital depth, for SpaceX. Bringing collectively my adjustments in goal revenues, working margins and reinvestment inputs permits for an replace of the enter desk that I began this part with:Clearly, a few of the adjustments in inputs (similar to the upper margins for the area launch enterprise and an even bigger goal marketplace for AI) will push worth increased, and a few of the inputs (together with a slowing of close to time period progress for all enterprise, and the a lot decrease margin for the AI enterprise) will push in the other way. Since US treasury charges have risen from 4.20% on the time of my earlier valuation to 4.56% initially of June, I’ve elevated the prices of capital that I take advantage of within the valuation accordingly (to eight.37% from 8.02% to begin the valuation, and the regular state value of capital to eight.25% from 8.00%; each numbers would put SpaceX at near the median for all US corporations). With these up to date inputs, I reestimate the money flows and the valuation for SpaceX, with the IPO proceeds (estimated at $75 billion) added to the combo: The enterprise worth for SpaceX edges up from $1.21 trillion, in my pre-prospectus valuation, to $1.22 trillion with the post-prospectus numbers, and the general fairness worth will increase to $1.3 trillion, with virtually the entire enhance coming from the inflow of $75 billion in money from the IPO, albeit with the next share rely. The worth per share of about $100 will want some revisiting because the IPO numbers agency up and extra data is forthcoming on restricted inventory items owned by workers, however simply as I used to be ending this put up, a information story hit the wires that the providing worth could be set at $135/share. If I had been to summarize the impression of the prospectus on my SpaceX story, it might be that it has made the story larger, but in addition extra risky. There are a mess of dangers that SpaceX faces in every of its companies, however the one which I’d be involved about essentially the most is that it’ll overreach within the AI enterprise, starting with an overestimate of the goal marketplace for AI services and the power of its personal aggressive place in that market, and following by way of with investments that replicate these misplaced assessments. These issues are heightened by a voting share construction that locks in Elon Musk’s management of the corporate, since there may be little that shareholders can do to restrain the corporate, if SpaceX doubles down on capital expenditures and acquisitions within the AI area, even after it turns into clear that the AI market is way smaller than anticipated and/or that xAI’s choices are not so good as the competitors. For those who add to this combine the antipathy that exists between Musk and Sam Altman, you’ve got the potential for a UFC match between two monstrous egos, funded by tens of billions of {dollars} shareholder cash.Monetary Statements and Worth: The Life Cycle Impact Monetary evaluation and valuation, going again to Ben Graham’s Safety Evaluation, has at all times been centered on monetary statements, and that focus has turn out to be extra intense over the previous few many years as entry to knowledge and evaluation instruments has expanded. In actual fact, a lot of what passes for valuation has turn out to be monetary modeling, the place line objects in monetary statements are forecast primarily based upon the historic time collection, with the proverbial backside traces being earnings and money flows. Alongside the best way, ratios computed from monetary assertion numbers are used to display corporations for funding high quality. A few of these ratios, similar to accounting returns on capital and fairness, have turn out to be the premise for assessing firm high quality and aggressive moats within the fingers of consultants and traders. The SpaceX prospectus is a case examine in why this method to investing is commonly myopic and deceptive, and why the informational worth of monetary statements will change as corporations develop and mature. In valuing corporations, you’re at all times attempting to forecast revenues, earnings and money flows in future, however they key questions you need answered and the drivers of worth shift as you progress by way of the life cycle:As you may see, for younger corporations, the important thing determinants of worth embrace sizing the full market and assessing unit economics, and never the proverbial backside traces in accounting statements together with the magnitude of revenues and profitability. As corporations transfer by way of the life cycle from start-up to mature to say no, you must count on to see monetary statements evolve as nicely. Younger and excessive progress corporations will typically report small revenues (although they count on these revenues to ramp up over time) and dropping cash and having damaging money flows is a characteristic, not a bug. As corporations mature, revenues will get bigger (albeit with decrease progress) and earnings flip optimistic, as will free money flows accessible to return to shareholders in dividends and buybacks.For those who permit for the truth that all three of SpaceX’s companies are younger, falling within the younger to excessive progress classes, the large questions driving worth are about market measurement and unit economics, for the reason that former gives the premise for income progress and the latter determines profitability. That’s the reason, when wanting on the prospectus for SpaceX it was the information on whole addressable markets, unit economics and capital depth that had an even bigger impression on worth, and this data, for essentially the most half, was within the footnotes to the financials, somewhat than within the monetary statements themselves. For individuals who are centered on worth metrics/constraints (constantly cash making, excessive revenue margins and accounting returns) and pricing multiples (low EV to EBITDA or low PE), the SpaceX prospectus is stuffed with crimson flags. SpaceX is an organization with small revenues and enormous losses, and paying 100 occasions revenues for it (which is the place a $1.8 trillion pricing would put it) appears foolhardy. I’ve no quarrels with this viewpoint, which animates old-time worth investing, however this angle comes with a price by way of funding decisions. Buyers who’re wedded to by no means shopping for cash dropping corporations or by no means paying greater than twenty occasions earnings for a inventory will find yourself with portfolios of mature (and declining) companies. If that’s their consolation zone, the technique is completely defensible, however they need to dispense with complaints about by no means having the ability to discover excessive progress shares to spend money on or critiques of others who discover these shares enticing, however the weak numbers. There are lots of good arguments that may be made about why you shouldn’t spend money on SpaceX, however basing that conclusion on the truth that they’re money-losing or have damaging money flows or commerce at a excessive a number of of revenues is each lazy and unconvincing. In distinction, making a case towards investing in SpaceX since you imagine that the goal markets for its companies will likely be far smaller than the corporate thinks they are going to be, or that value and aggressive pressures will drive margins down and even that you simply discover its company governance construction and dependence on a character (Elon Musk) off-putting is completely cheap. For those who do make that case, although, it’s value remembering that that is your viewpoint, and that disagreements about market measurement and profitability throughout traders, particularly in younger corporations, are pure and wholesome. In brief, primarily based on my inputs and story, I believe that SpaceX is value about $1.25-$1.3 trillion, however in case you contend that it’s value $3 trillion or solely half a trillion, it’s neither my job nor my place to persuade you that I’m proper and that you’re incorrect. The IPO Pricing Sport Within the coming weeks, you’ll undoubtedly be uncovered to a number of views on SpaceX, and that’s wholesome. That mentioned, you can be higher outfitted to make sense of those views, and maybe incorporate a few of the views into your individual, and reject these that don’t make sense, when you’ve got an understanding of what an IPO course of includes. Specifically, understanding the motivations of the completely different gamers within the sport (the funding bankers setting the providing worth and managing the providing, the issuing firm, the traders and merchants jockeying for shares at that providing worth and the merchants positioning themselves for the primary day of buying and selling) will assist decide whether or not you need to be enjoying this sport or sitting it out, at the very least for the second.The Bankers Let’s begin with the sequencing that goes into a standard preliminary public providing, although options have emerged to it lately:As you take a look at the function performed by bankers to the IPO course of, permitting them to maintain a slice of the IPO proceeds, the SpaceX IPO is a testimonial to the dwindling worth added by bankers on each dimension:Timing: It’s city (or market) legend that funding banks can time markets, and that this market timing may also help decide the most effective time to go public. Only one take a look at the monitor report of market strategists at funding banks ought to dispense with this delusion, since banks (and most institutional traders) are (and have by no means been) good at gauging market momentum and shifts in temper. Submitting and Providing particulars: It’s true that there are technical particulars and logistical steps to submitting a prospectus and setting providing particulars, however they’re virtually all mechanical. With SpaceX, I’m not certain whether or not the prospectus, as filed, was the work of a staff of bankers, but when it was, I’m wondering what a wholly Grok-written prospectus would have regarded like, and whether or not we’d have observed the distinction. Pricing: In an IPO, the bankers’ mission is to cost corporations for his or her providing, not worth them, and whereas they normally draw on pricing multiples and peer teams to make that pricing judgment, they’re guided by the pricing in the newest personal transactions, normally within the type on enterprise capital rounds. With SpaceX, that job is simplified by the truth that this firm, whereas personal, has had lively buying and selling in its personal shares, and that it was priced at roughly $1.2 trillion previous to the IPO course of commencing. Including the $75 billion in providing proceeds, and incorporating the benefits of elevated liquidity from being a public firm and turning into a part of the S&P 500, it’s not stunning that there’s a sense that the providing will likely be priced at between $1.5 trillion to $2 trillion, with or with out the funding banking enter. My guess is that we’ll find yourself someplace within the center, with some handwaving about income multiples and different AI corporations used to justify that pricing. (After I completed this put up, a information story popped up that the supply worth could be set at $135/share, translating into a couple of $1.8 trillion pricing for the corporate.)Promoting/Advertising: In an age the place funding banks have misplaced credibility and social media is the place advertising occurs, SpaceX can generate its personal advertising spin, and has a military of influencers behind it. As well as, virtually each institutional investor has a viewpoint on whether or not to personal SpaceX or not, it’s unclear what precisely a roadyshow can do to reinforce the gross sales pitch.Value assure: The pricing assure that funding bankers supply in preliminary public choices is a principally empty promise, since they systematically set providing costs at beneath (by 15-20%) what they imagine the market can pay. That’s the reason that the supply worth for SpaceX will likely be set beneath the higher finish of the vary, and whereas the low cost could seem to be a big loss to funders and present house owners, the truth that the providing is for lower than a tenth of the shares within the firm will soften the blow.Publish-market help: As a follow-up to the worth assure, funding banks usually supply after-market help for corporations within the days after they go public, shopping for shares if the inventory comes underneath promoting strain. With SpaceX, that choice is off the desk, since no funding financial institution has the capital to help the pricing of a two-trillion firm, if traders flip damaging on it.In actual fact, provided that banks are maybe getting extra from the preliminary public providing, by way of publicity and allotments for his or her most well-liked clientele, than SpaceX is getting from their providers, you might argue that the bankers ought to be paying the corporate for mirrored glory, somewhat than charging them charges. The one good cause that I can consider for SpaceX not going the direct itemizing route, the place you dispense with the kabuki dance of choices and let the market set the providing worth, is that the corporate wants the money from the providing, and that route is way more troublesome to soak up a direct itemizing.Issuer (Firm, Founder and Buyers) Trying on the IPO from the SpaceX perspective, the general public providing will present advantages. For the traders within the firm in its personal type, together with enterprise capitalists from early in its life to public traders in newer years, the IPO will permit them to money out, albeit after the lock-out interval expires in just a few months. For the corporate, the elevated entry to capital from being a public firm will permit it to fund the capital expenditures and funding wants that emanate from the corporate’s ambitions within the AI enterprise. For Elon Musk, the general public providing has the potential to make him the primary trillionaire in historical past, along with unlocking new pathways to additional enrichment for assembly specified targets (together with getting 1,000,000 folks on Mars). Since a few of these advantages have been in existence for a few years, the truth that firm stayed personal for that interval is a sign that there are prices to going public which have held it again. The primary is that, however Musk’s voting management of the corporate, turn out to be a public firm will open SpaceX to market scrutiny, within the type of earnings stories each quarter and insider buying and selling stories. The second is that the market is fickle, and whereas it’s rewarding corporations that spend money on AI with excessive market costs right now, it might probably change its thoughts and punish them for a similar cause. The third is that whereas there may be little that traders can do to commerce and make cash on overpriced personal companies, they will promote brief on public corporations.Buyers and Merchants SpaceX is an organization that has been within the public eye for a decade or extra, whilst a privately owned enterprise, partly due to its social media boosters and partly as a result of its area launches make it a magnet for consideration. There are lots of who’re drawn to the corporate, however unable to spend money on it as a non-public enterprise, will now have an opportunity to take action, if it goes public. However ought to they attempt to partake within the preliminary providing? The reply to that query relies on whether or not you’re an investor, the place you purchase (promote) corporations that you simply imagine are buying and selling underneath (over) their evaluation of worth and hope the hole closes or a dealer, the place you purchase (promote) corporations the place you count on costs to go up (down) sooner or later, for a mess of causes, solely a few of which can relate to firm fundamentals. I’m extra investor than dealer, and I say that with out judgment, for the reason that finish sport in markets is to make cash, not rating mental factors. The reality is that I’m not an excellent dealer, and I’m higher off staying in my most well-liked area, which is valuation, albeit with no ensures of a payoff. My valuation of SpaceX was pushed by my curiosity within the firm and perception that it’s in distinctive, cutting-edge companies, and my determination on whether or not to purchase into the providing is subsequently pushed by my evaluation of its worth. On the rumored pricing of $1.8 trillion for the corporate, it’s too richly priced for my tastes, given my valuation of $1.25-$1.35 trillion for the fairness within the firm. That doesn’t imply that I’ll by no means purchase the inventory, for the reason that market does change its thoughts, and if the worth does drop by sufficient, my determination would change accordingly. It’s value remembering that Fb was promoting at half its providing worth just a few months after its IPO, and that Uber misplaced greater than 50% of its market cap within the 12 months after its public providing, shifting each corporations from over to underneath valued. In case you are a dealer, although, the sport adjustments. Particularly, the intrinsic worth of the corporate will not be central to your determination, even perhaps irrelevant, and your judgment on whether or not you search to partake within the SpaceX providing will rely in your studying of market temper and momentum. I’d not be shocked within the least to see the providing priced at $1.8 trillion, and see a soar within the worth on the day of or within the weeks after the providing, and if that’s your most probably situation, having the ability to get into the providing on the supply worth and even within the first few hours or days of buying and selling will likely be a profitable technique. The danger, after all, is that momentum can shift shortly, inflicting a big worth drop, successfully making timing your trades proper key to your buying and selling technique. The shifting and sometimes unpredictable forces of temper and momentum are additionally the rationale that as an investor, I’d not promote brief, however my worth evaluation, even when the pricing for the corporate pushes from $1.8 trillion to $2 trillion or extra. A Loaded Guess on AI! Because the IPO course of for SpaceX heats up within the coming weeks, you must put together your self for a flood of promoting from the corporate and its bankers, with discuss of potentialities and potential dominating the dialogue, in addition to arguments from the opposite aspect, the place will probably be framed as a automobile for AI hype, destined to fail. In case you are on the receiving finish of those gross sales pitches, you must pay attention however examine the numbers for plausibility and make your individual judgments. For the bankers concerned and the issuing firm, the most important hazard to a profitable providing will not be that there will likely be near-term actuality checks on their hype, however that the market temper will shift, both within the mixture or particularly associated to AI, within the weeks main as much as the providing. It doesn’t matter what your views are in regards to the SpaceX IPO, optimistic or damaging, there isn’t any denying that this firm is a loaded wager on the AI and Elon Musk, and whereas that will concern some, there are others who will take a look at Musk’s monitor report with Tesla and really feel the chances are of their favor. YouTubeAttachmentsSpaceX prospectusValuation of SpaceX, post-prospectus on 6/2/26Blog posts on SpaceX
Musings on Markets: Revisiting the SpaceX Valuation: A Publish-Prospectus Replace!