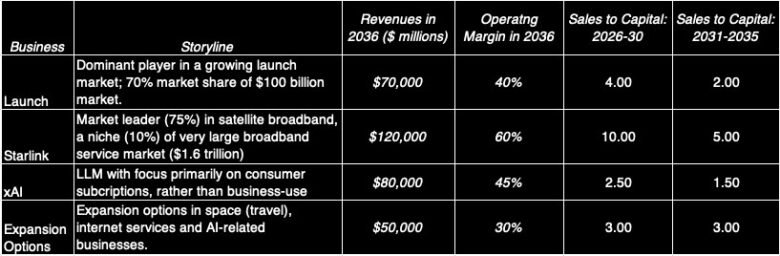
In 2001, A Area Odyssey, a film that was nicely forward of its time when it was launched in 1968, Hal (the pc) famously responded to questions on his reliability with “it (mstakes) can solely be attributable to human error”. I used to be reminded of my fallibility repeatedly as I attempted to worth SpaceX forward of its preliminary public providing, a market debut that’s shaping up as a barn-burner for 3 causes. The primary is that in a market the place there are various younger corporations all making an attempt to say to be futuristic of their choices, SpaceX clearly stands out as the actual factor, with rockets, satellites and AI all residing underneath its company umbrella. The second is that its founder (Elon Musk) is the richest individual on this planet, has upended one legacy enterprise (autos), purchased a social media firm as a soapbox and made his presence felt on the the political stage. Love him or hate him, Musk is certainly not boring, and his capability to spin enterprise narratives that appear outlandish at first listening to. however change into standard knowledge later, clearly provides to the attract of SpaceX. Third, if the non-public market pricing feeds into the general public providing, SpaceX may very nicely change into essentially the most priceless IPO of all time, becoming a member of the rarefied listing of trillion-dollar corporations, on itemizing. That mentioned, I could also be getting just a little forward of the sport right here, as a result of SpaceX has not filed a public prospectus but, and little is understood about its financials different that drabs of knowledge which have been leaked to the press. I’ll forge on, however, with the stipulation that it is a first iteration, and that I’ll revisit it, as extra info comes out in regards to the agency’s monetary standing and its IPO plans.The Historical past of SpaceX It’s possible you’ll be shocked to listen to that SpaceX is older than Tesla, at the least by way of chronological age, based on March 14, 2002, in El Segundo, California. At its founding, Musk acknowledged its targets as decreasing the prices of area transportation and journey to Mars, however was considered as having little probability of success by the area institution, composed then of presidency companies (NASA) and some protection companies (Boeing and Northrop Grumman). SpaceX utilized the teachings of modular engineering from the software program enterprise and it launched Falcon 1, its first area launch automobile in September 2008; that profitable launch led to a NASA contract for $1.6 billion, and rescued the corporate from close to chapter. In subsequent years, SpaceX developed Falcon 9, a reusable and heavier automobile, with the Dragon Spacecraft unit, and have become the primary industrial entity to ship cargo to the Worldwide Area Station. In 2013, SpaceX launched its first mission for a personal buyer, and rapidly secured a dominant market share of business launch contract market. In recent times, SpaceX has invested in an much more formidable model (by way of dimension and energy) of reusable spacecraft with Starship, and whereas its first launch in 2023 exploded in area, the corporate is clearly shifting in direction of making it useful. Alongside the way in which, the corporate added to its enterprise combine, first with The Boring Firm, a firm that specialised in constructing tunnels that might be used to move individuals, in 2017, earlier than spinning it off as a separate entity. Extra considerably, in 2019, the corporate launched sixty Starlink satellites, with the tip sport of providing satellite-based web companies to clients, particularly in areas the place standard web service was restricted. That endeavor has now grown to incorporate 1000’s of satellites and had greater than ten million lively subscribers unfold internationally, on the finish of 2025. In February 2026, the corporate created its third enterprise arm, with its acquisition of xAI, the dad or mum to Grok, the Musk-developed competitor within the LLM area. SpaceX had a sluggish begin financially, as its preliminary years have been spent growing the Falcon 1 rocket, and even after that improvement, the dependence on the US authorities and industrial satellite tv for pc launchers resulted in revenues rising rather more slowly than they did at Tesla, Musk’s different high-profile creation. At the same time as late as 2021, SpaceX reported revenues of simply over $2 billion, virtually totally from its launch enterprise, however Starlink’s subscriber primarily based mannequin has allowed revenues to extend greater than five-fold since, reaching an estimated $15.6 billion in 2025, with slightly below 30% coming from the launch enterprise ($4.1 billion) about the remainder from Starlink subscriptions and associated companies ($11.4 billion); xAI, which was acquired in 2026, had subscription revenues of roughly $100 million in 2025. With out full financials to again up the assertion, it’s estimated that SpaceX generated an EBITDA of $8 billion in 2025, although with depreciation and different bills thought-about, it isn’t clear how a lot (if any) working (or web) income the corporate delivered throughout the 12 months. On the funding entrance, Elon Musk used a portion of his winnings ($180 million) from his PayPal exit as seed cash ($100 million) for founding SpaceX, however the firm has required a number of rounds of enterprise capital to fund its infrastructure wants. The primary enterprise capital spherical of about $12 million was in 2002, however there have at the least thirty extra infusions amounting to greater than $12 billion. Whereas SpaceX counts huge title enterprise capitalists in its investing roster (Founders Fund, Andreessen Horowitz and Sequoia), it has additionally seen rising investments from public fairness buyers equivalent to Constancy and public tech corporations equivalent to Google. Whereas these enterprise capital investments have diluted Musk’s possession through the years, he continues to personal about 42% of the fairness within the firm, and with differential voting rights, near 80% of the overall voting rights within the firm.Valuing SpaceX It’s true that intrinsic valuation, at the least in its discounted money move avatar, is far simpler to do at corporations which have a few years of historic information and peer teams of corporations in the identical enterprise, and there are some who view one or each as pre-requisites. In case you undertake that standpoint, it’s simple to see why so many view SpaceX as an organization that can’t be valued (but), since you do not have entry to even a single 12 months of financials, not to mention a protracted historical past, and there aren’t any true opponents. In actual fact, it’s doubtless that even when the monetary statements are made public in a prospectus, most will proceed to keep away from valuing the corporate, utilizing uncertainty in regards to the future as an excuse. In case you outline intrinsic worth as the worth of a enterprise primarily based upon its capability to generate money flows sooner or later, there’s nothing in that definition that requires both historic information or peer group info, and statistically, the truth that you face uncertainty or that you’re lacking info doesn’t indicate that you just can’t make estimates, simply that the estimates will likely be noisier.. I’ve lengthy argued that you could estimate the worth of younger corporations with minimal information, so long as you construct a valuation round a enterprise narrative, and settle for that this valuation will change, as circumstances do, and with SpaceX, I’ll get an opportunity to place this argument into follow. To worth SpaceX, I think about every of its three core companies individually since they differ not simply on working metrics, but additionally on the competitors confronted in every one.The launch enterprise, which is the place SpaceX was born, remains to be its most identifiable enterprise, and frames the corporate’s story not simply as a futuristic firm, however one which was capable of overcome a number of the most vital technological challenges of any begin up and never simply survive however thrive. SpaceX has established such a sturdy and long-standing value benefit over its opponents within the enterprise, stemming from its current infrastructure investments and reusable rocket know-how, that it had a market share in extra of 80% of the launch market in 2025. Its competitors will come from some non-public and government-funded gamers, who could possibly seize market share, however their increased prices, attributable to safety and nationalistic issues..Valuation narrative: The area launch market is estimated to be about $30 billion in 2026 and is predicted to develop to $100 billion in 2036, as authorities and personal enterprise demand will increase. SpaceX will proceed to dominate the enterprise, albeit with a barely much less dominant market share (70%, down from >80% in 2025) of the overall market and as prices lower with scale, working margins will enhance over time to 40%. (I’m being conservative in my estimates, insofar as I’m ignoring area journey and expanded enterprise alternatives in area, however I do not assume, in the mean time, that both presents a viable path to augmenting revenues).The web service enterprise, constructed round Starlink, is the enterprise that accounts for nearly two thirds of the revenues of the corporate in 2025, and it builds on the infrastructure constructed for the launch enterprise, since SpaceX has used it to launch 1000’s of satellites into area. On the finish of 2025, Starlink had near 10,000 satellites in area, about two thirds of your entire world rely, and is including to that quantity each month. That has allowed it to double its subscriber numbers to simply over 10 million, within the final 12 months, and whereas Amazon’s acquisition of GlobalStar has introduced a possible competitor into the combination, GlobalStar has a fraction of the satellites that Starlink does. The problem for any satellite-based web service supplier is that however using low-earth orbit (LEO) satellites to enhance service, the broadband service lags extra standard web know-how (fiber optic and cable) in a lot of the world, leaving it (at the least for the second) with a distinct segment market of rural areas, international locations with broken or no infrastructure and individuals on the go (airplanes, trains and vehicles). Thus, whereas the overall web service market is estimated to be near a trillion and a half {dollars} globally, in 2025, satellite-based service accounted for about 1% of that market, delivering underneath $15 billion in revenues, with StarLink having a dominant market share. Valuation narrative: The satellite tv for pc web companies market will proceed to develop, as know-how improves service high quality and transit demand for higher wifi grows, from $15 billion to $160 billion (from lower than 1% to 10% of of the web service market) over the following decade. Starlink will see extra competitors, however its lead in satellites and capability to make use of its launch enterprise to get extra into area, will give it a considerable benefit and a market share of 75% of the general market). The price of buyer acquisition will ease over time, as enterprise clients change into a bigger portion of the enterprise, and working margins will strategy 60% in regular state, because the unit economics are very constructive.The Giant Language Mannequin (LLM) enterprise, from the acquisition of xAI, has introduced AI into the SpaceX story, and whereas which will add to the pricing pleasure, Grok lags the opposite LLMs by way of revenues and attain, for the second. By way of utilization, Anthropic (with Claude), OpenAI (with ChatGPT) and Google (with Gemini) should not solely extra extensively used than Grok, in enterprise setting, however are additional alongside in changing them into revenues. Whereas Grok has been bundled into the X Premium subscriptions, and earned about $80 million in revenues in 2025, it appears to be focusing extra on shoppers and solely on area of interest parts of the enterprise market. That is essentially the most diffuse and risky of the three markets, by way of potential market, for the reason that potential market can run from the tens of billions (if they continue to be subscription-based) to lots of of billions and even trillions (in the event that they change into replacements for human labor or large productiveness boosters). It’s doable that Grok could concede the bigger and extra aggressive enterprise area to Claude and ChatGPT and focus as a substitute on shopper subscriptions, giving it a smaller market, however one with much less competitors. Valuation narrative: The general LLM market will proceed to develop, however extra in enterprise purposes than in shopper apps, with the market dimension being decided by how nicely AI can replicate human labor and regulatory restrictions. xAI will goal primarily shopper subscription revenues and area of interest enterprise purposes. That can give it smaller revenues ($80 billion in 2036) than its LLM opponents, however one with much less competitors and better margins (50% working margin), and fewer reinvestment because it avoids going head-to-head with Anthropic, OpenAI and Google for enterprise use.It’s simple that SpaceX, as a lead participant in three fast-growing and risky companies, could possibly use its infrastructure to develop every of those companies. The area launch enterprise, which has usually centered on delivering industrial or authorities masses and satellites into outer area could change into a springboard for area journey, for leisure, analysis or enterprise. With its satellite tv for pc broadband choices, the chance exists that the know-how and the attain will enhance to some extent the place the service can compete with fiber-optic and cable broadband choices, maybe at a lot decrease value. With xAI, the chance that Grok finds a approach to outflank its LLM rivals, together with Claude, Gemini and ChatGPT, by way of enterprise choices could also be low, however it does exist. The latest acquisition of Cursor, a younger AI firm within the coding area, means that xAI has not thrown within the towel on enterprise purposes. In fact, these are all choices that will not be viable in the mean time, but when they change into viable, may add immense worth. Valuation narrative: This a part of the story is constructed on the growth choices that SpaceX has to enter giant markets, with low likelihood and excessive payoff. In a crude try to seize this a part of the story, I’ll connect an anticipated income in 2036 to those different companies of $50 billion and an working margin of 30%. Since these growth choices, in the event that they do exist, won’t present up within the close to future, the revenues from these choices ramp up after 12 months 6 (2032) within the valuation.Pulling these storylines collectively as valuation inputs, I estimate the next numbers for 2036, for the three enterprise traces and for the growth choices class: With these numbers in place, and utilizing a price of capital reflective of SpaceX’s enterprise combine (of aerospace/protection, telecom companies and AI) of 8%, we will estimate the corporate’s worth:With my story and inputs, the worth that I derive is $1.22 trillion, about 10% under the non-public market pricing and a couple of third under the anticipated IPO pricing, however nonetheless astonishingly excessive for an organization with $15.5 billion in revenues in the newest 12 months, and a number of query marks about company governance. Observe that on this iteration, I’ve ignored money and debt, since I should not have the corporate’s monetary statements, however it’s unlikely that both could have a lot of an influence on the worth of fairness for an organization with this excessive a price for its working belongings. As you’ll be able to see, the SpaceX story not solely has many shifting elements, however is fraught with uncertainty, and with out full financials, it doesn’t have start line. That mentioned, because the story performs out, we are going to get extra readability, and the story will should be reworked, with the worth penalties unclear. For the second, although, I’m unsure about each enter in my SpaceX valuation, however uncertainty is a continuum, and I’m much less unsure about some inputs (such because the revenues and margins within the area launch and satellite tv for pc web service companies) than about different inputs (together with the revenues and margins of the LLM and growth companies). If you’re questioning why the price of capital is just 8% for the corporate, near the median value of capital for a US firm, it’s as a result of a lot of the chance right here is particular to the corporate (thus decreasing the impact in a diversified portfolio) and cuts in each instructions (upside and draw back). In actual fact, if there are outliers, they’re extra prone to be on the upside than the draw back. With these issues in thoughts, I attempted to be open about how unsure I really feel about my estimates, and the outcomes of a simulation yields the next distribution for worth:Because the simulation is centered on the identical anticipated values for inputs as I utilized in my base case, it ought to come as no shock that the median worth, throughout ten thousand simulations, of $1.29 trillion is near the bottom case valuation of $1.22 trillion. Because the pricing for the IPO begins to achieve traction, it’s value recognizing {that a} $1.75 trillion or perhaps a $2 trillion pricing falls within the vary of the distribution, although with little or no upside left for an investor paying that value. In case you really feel that it’s best to attend for the prospectus to be filed, earlier than doing the valuation, I perceive however there are three factors value remembering. First tt is unlikely that the prospectus will comprise information that may transfer the intrinsic worth story, since not one of the numbers within the reported statements will likely be giant sufficient to change the immense worth coming from expectations of future development. Second, whereas the prospectus will comprise estimates of complete addressable market and maybe even profitability, in my expertise, will probably be hype; count on to see trillions of {dollars} thrown round nonchalantly for market dimension. Third, as I see it, it isn’t an both/or proposition, since I can worth the corporate now, and revisit the valuation when the prospectus comes out, with the benefit being that you’re much less prone to be swayed by the gross sales pitch within the prospectus.Pricing SpaceX In an preliminary public providing, corporations are priced, not valued, by bankers (for the providing value), by buyers (because the inventory begins buying and selling) and by observers to make judgments (on whether or not it over or underpriced). Thus, you may make the argument that the valuation, with all of its shifting elements, is irrelevant, and that you must value SpaceX, not worth it, in case your intent is to commerce on the IPO. That could be a respectable critique, however the argument that pricing someway dispenses with the necessity to make assumptions about market dimension and profitability or doesn’t have the identical uncertainties isn’t. You’ll be able to take challenge with the intrinsic valuation due to the layers of assumptions that I needed to make alongside the way in which, and I do know that for a lot of buyers, both invested already within the firm ,or planning to spend money on it, a pricing could seem much less daunting. Whereas I sympathize, I’m afraid that the uncertainty will likely be simply as a lot of a difficulty in pricing SpaceX, and to see why, check out the steps within the pricing course of:At every step within the course of, you’ll run into points. On the pricing metric entrance, the issue with choosing a metric is an info vacuum, with solely two scalars, revenues and EBITDA, accessible, and even if you happen to think about the newest non-public market pricing, which priced the corporate at about $1.25 trillion, because the market worth of fairness, the absence of debt and money numbers makes it inconceivable to again into enterprise worth. This downside needs to be resolved, for essentially the most half, when the corporate information a full prospectus, however for the second, if you happen to assume that the online debt quantity is near zero, the ensuing enterprise worth of $1.25 trillion yields nosebleed multiples of 81 occasions revenues and 156 occasions EBITDA for the corporate, utilizing 2025 numbers. Even with minimalist info, there will likely be pricing variants that use anticipated revenues (or EBITDA) in a future 12 months as a scalar, as could be seen on this graph:There is no such thing as a inherent downside with utilizing ahead numbers in pricing, so long as you do the identical for all the corporations in your peer group, however within the case of SpaceX. it’s inevitable that bullish analysts, unable to justify the sky excessive pricing values with trailing 12-month numbers, will resort to utilizing ahead pricing, and add to the bias, by inflating revenues in future years. Within the graph, I’ve used the forecasted revenues in 2030 and 2035, from my intrinsic valuation, and the EV to Gross sales ratio drops from 80.13 (112.18) to three.91 (5.47), utilizing the non-public firm (estimatedIPO providing) pricing of $1.25 trillion ($1.75 trillion) because the enterprise worth. The even greater problem in pricing SpaceX will likely be within the second step, the place it’s a must to discover comparable companies (or a peer group) to base your pricing on. There’s clearly no firm on the market that’s remotely just like SpaceX, as a composite firm, and even if you happen to break it down into companies, it’s doubtless that you’ll hit roadblocks. On the area launch enterprise, utilizing publicly traded aerospace and protection corporations like Boeing and Northrop Grumman is a non-starter, as a result of they’re low development, lower-margin companies, not like SpaceX. Palantir could look like a logical various, and whereas it might have excessive development potential, it’s a information/software program firm that doesn’t have the infrastructure wants that SpaceX does. On the web service enterprise once more, there are standard telecom companies like Verizon and T-Cell, however the economics of their choices are totally different, and they don’t seem to be development corporations. In April 2026, I computed the multiples of revenues and EBITDA that publicly traded corporations within the aerospace/protection, web companies companies and know-how corporations commerce at, and they’re far decrease than what SpaceX could be anticipated to commerce at, if it goes public at $1.5 to $2 trillion:Lastly, on xAI, there are different LLMs, virtually all of that are non-public corporations now, and whereas you need to use the pricing from most up-to-date VC rounds, you might be on shaky grounds. Even if you happen to solid forward with a peer group of high-growth, tech corporations, your pricing will virtually actually need to revolved round revenues, reasonably than income, and primarily based upon very small samples.The one a part of pricing that you’ll virtually actually see is the story telling, particularly with analysts who’re locked into discovering SpaceX to be a purchase, with the pricing extra of an ex-post rationalization than a analytical software. It doesn’t matter what peer group you choose, SpaceX will likely be priced increased than comparable companies, and to again the argument that it’s nonetheless funding, you’ll hear tales of its giant potential market, important aggressive benefits and profitability. All of those tales are grounded in reality, however they’re empty if they continue to be tales. I’ll predict that there will likely be way more purchase than promote or maintain suggestions for SpaceX, when it does go public, with analysts doing pricing gymnastics with ahead multiples, hand-picked peer teams and fairy tales to justifying their positions.Pricing is an train in information evaluation, and any pricing of SpaceX will replicate the statistical limitations of the info. Put merely, the one distinction between intrinsic valuation and pricing, on the subject of the uncertainties you face with SpaceX, is that with the previous (intrinsic valuation), it’s a must to resist the uncertainties and make your finest express judgments (on revenues, margins and reinvestment), whereas with the latter (pricing), they continue to be implicit. If bias is your largest adversary in assessing SpaceX, and you utilize pricing, it is rather doubtless that one can find a pricing metric and hand-picked peer group to replicate your biases, after which inform your self a narrative on why SpaceX is affordable or costly.The Backside Line SpaceX is an engineering marvel that has proven its naysayers, which included virtually each luminary within the area group, to be unsuitable. That mentioned, for potential buyers, there are classes to be discovered from watching Musk’s stewardship of Tesla. As with all of Musk’s creations, SpaceX will likely be a form shifting entity, irritating buyers who count on corporations to observe linear paths within the company life cycle, going from younger development to maturity; it can shift from one narrative to a different, typically with no advance warning, inflicting whiplash for buyers. After I purchased Tesla in 2019, after its inventory had taken a beating, I described the corporate as my company teenager, and with Musk in full management, SpaceX is prone to observe the identical unpredictable path. That makes it a tough firm to purchase, however it makes it an much more harmful firm to promote brief, as Tesla brief sellers have found within the final 20 years. With all that mentioned, SpaceX is a singular firm with immense aggressive benefits, and whereas I’d not be considering shopping for on the rumored IPO pricing of $1.75 trillion, it’s one huge correction away from being pretty priced and even low cost. If that occurs, I will likely be a purchaser, however will accomplish that with the popularity that this firm comes packaged with a founder who’s each uniquely gifted and deeply flawed, and complaining in regards to the elements of Musk you don’t like, whereas having fun with the fruits of the elements that you just do, is unfair.YouTube VideoSpreadsheetsValuation of SpaceX in April 2026 (Pre-IPO, and with restricted financials)
Musings on Markets: To a Trillion(s) {Dollars} and past: A SpaceX IPO Odyssey!