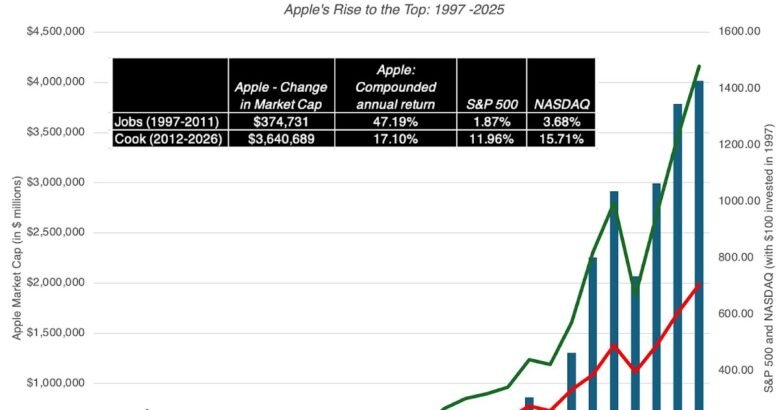
By means of time, we have now glorified conquerors and empire builders in politics, civic life and enterprise, from Alexander the Nice and Genghis Khan to the tech titans of at this time. That’s no shock, since these people have outsized personas and infrequently change the course of historical past, however additionally it is true that this glorification of empire constructing has shortcomings. The primary is the deification of those heroes comes with whitewashing of the darkish sides and the prices of empire constructing. The second is that we low cost and undervalue those that contribute to societal or enterprise advances, however achieve this quietly and with little fanfare. It’s on this context that I used to be drawn to the story of Tim Prepare dinner stepping down as Apple CEO, after a tenure of fifteen years atop an organization that has been among the many high market cap corporations on the planet for a lot of that interval. Whereas Steve Jobs, his predecessor as CEO at Apple, has now been deified in enterprise circles, as an unparalleled visionary and enterprise builder, and deservedly so, I feel that Tim Prepare dinner, in some ways, has performed simply as important a job in molding the corporate into its present day standing, with far much less recognition.Apple’s CEOs: From Scott to Jobs to Prepare dinner! Unfair although this may occasionally appear, the Tim Prepare dinner story at Apple has to begin with Steve Jobs. Jobs co-founded the corporate in 1976, with Steve Wozniak, and whereas the corporate went via a sequence of CEOs within the subsequent twenty years, Jobs was the face of the corporate in its early years. Whereas it’s straightforward, with the advantage of hindsight, to view these pretty much as good years for the corporate, these early years mirrored each Job’s strengths and weaknesses. His imaginative and prescient and power of character gave rise to the private laptop in its present type, as a instrument for everybody to make use of, not simply tech geeks, and as somebody who purchased his first Mac (the 128K with out a laborious drive) in 1984, and has stayed a Mac consumer since, I’m grateful. That stated, the darkish facet of Jobs, manifested in impatience with underlings and an obstinate perception that he knew what clients wanted higher than they did, led to the Lisa, the one Mac I regretted shopping for nearly instantly after my buy, and a lack of enterprise markets to Microsoft. These failures led Apple to the brink of failure, and to Jobs being forged out of the corporate by its board in 1985, although the CEOs that adopted had neither the strategic imaginative and prescient nor the business-building capability to rescue the corporate. In 1997, Apple seemed prefer it was an organization heading into oblivion, as Home windows turned the dominant working system for private computer systems, and it appeared like Apple had misplaced its objective. The August 1997 return of Steve Jobs,, who had used his years within the wilderness to construct Pixar, an organization that revolutionized animated film making, is now the stuff of legend, as he rebuilt Apple within the ensuing years right into a powerhouse, across the iPod, the iPad and most of all of the iPhone. Whereas there are books and films chronicling the Steve Jobs success story, it’s value asking what the distinction was between the primary iteration of Steve Jobs at Apple (from founding to leaving in 1985), the place Apple misplaced floor to Microsoft, and the second iteration of Steve Jobs (from his return in late 1997 till his resignation in 2011). The primary was that he was older, and to the extent that with age comes some knowledge, it helped, however it’s unlikely to have been the change maker. The second was that in his interval away from Apple, Jobs created and constructed up different corporations, with Pixar being the most important, the place he realized to cope with individuals higher and maybe compromise a bit greater than he used to. The third was that he benefited from the presence of Tim Prepare dinner, first as an govt in Apple gross sales and operations, and extra importantly, as chief working officer (COO) for Apple, beginning in 2005. If Steve’s talent was imaginative and prescient, the place he showcased Apple’s subsequent “huge innovation” at conferences in his trademark black turtleneck, Prepare dinner’s talent was constructing manufacturing hubs and provide chains to transform the imaginative and prescient to merchandise. That separation of imaginative and prescient from enterprise constructing created the Apple juggernaut within the first decade of this century. Whereas that division of labor clearly was within the firm’s finest pursuits, Jobs deserves credit score for being keen to set his ego apart and delegate the powers to make it occur. Tim Prepare dinner has been CEO for fifteen years, and when he retires on September 1, 2026, he may have been the longest serving CEO at Apple. It can’t have been straightforward, particularly within the early years, because the comparisons to Steve Jobs had been entrance and heart, and there was stress on him to proceed in the identical path. To Prepare dinner’s credit score, he by no means tried to be Jobs, and he created a really completely different template for himself, one which match him and the corporate nicely, and served as a testimonial to his confidence. In one in all my talks a few decade in the past about Apple, I described Prepare dinner, maybe harshly, as a person with out a visionary bone in his physique, however one who would be sure that the trains ran on time (or the iPhones had been delivered as promised), and I feel that he has used that power to good impact throughout his years as CEO of the corporate.Apple’s Funds within the Twenty First Century: The Steve Jobs and Tim Prepare dinner Years! Steve Jobs handed over an organization to Tim Prepare dinner in 2011, that was terribly worthwhile, and on the time of his leaving, already the most important market cap firm on the planet. Whereas that truth leads some to low cost what Prepare dinner has performed at Apple since, I feel it’s value going again in historical past and company handoffs of nice corporations, and the way usually they change into tangled messes, as new CEOs overreach and overpromise. The place to start our comparability of the Jobs and Prepare dinner tenures is by charting Apple’s market capitalization, with the delineation into the Jobs years (1998-2011) and the Prepare dinner years (2012-2026):Trying throughout the aggregated years throughout each CEOs, it has been a rare time. Apple started the Jobs tenure as CEO with a market cap of $1.68 billion, and by the top of 2025, its market cap had risen to over $4 trillion, and its efficiency burnishes the reputations of each Jobs and Prepare dinner. Jobs offered the foundational enhance for the corporate and the improvements he presided over delivered a compounded annual worth appreciation of 47.19% between 1997 and 2011, a interval when US equities had been struggling and Apple reached the highest of the market cap desk in 2011. With Tim Prepare dinner on the helm, Apple added an astounding $3.64 trillion in market cap, however a powerful fairness market offered robust tailwinds, and the corporate’s annual returns had been extra modest. On a proportion return foundation, the Jobs years had been higher, however for my part, the truth that the annual returns within the Prepare dinner years had been simply as spectacular, as a result of they needed to be earned on a a lot bigger agency. The explanations for Apple’s sustained enhance in market capitalization had been easy – stable income development and a revenue machine that delivered excessive margins, whilst the corporate scaled up:As with the market capitalization comparisons, this chart yields metrics which might be favorable to each Jobs and Prepare dinner. Underneath Jobs, the corporate scaled up its revenues considerably, with a compounded annual income development charge of 23.67% between 1997 and 2011, and simply as considerably, went from posting subpar margins and a web loss in 1997 to changing into some of the worthwhile tech corporations on the planet, Underneath Prepare dinner, income development charges got here down (to a compounded annual common of 8.52% between 2012 and 2025), however on a a lot bigger scale, and the corporate preserved and grew its revenue margins. There was one company finance dimension on which Prepare dinner deviated from Jobs, and that was on money return or dividend coverage. Within the chart under, I have a look at the money returned to shareholders by Apple through the tenures of the 2 CEOs:Throughout Job’s tenure at Apple, the corporate paid no dividends and initiated solely modest money buybacks, largely to cowl stock-based compensations. With Tim Prepare dinner as CEO, Apple was one of many biggest company money success tales of all time, initiating dividends in 2012 and growing them over time, and supplementing these dividends with money buybacks that, within the mixture, had been the most important in company historical past. In sum, the corporate has purchased again nearly $800 billion between 2012 and 2025, and essentially the most astonishing characteristic was that, whereas returning all of this money, the corporate additionally amassed one of many largest company money balances in historical past. To the query of how Apple was in a position to return this a lot money, enhance its money steadiness and nonetheless develop itself, the solutions are three fold. The primary is that the iPhone, maybe essentially the most precious single product in enterprise historical past, continued to ship for the corporate, with modest reinvestment wanted on its upgrades. Whereas a lot of the credit score for the iPhone continues to be given to Steve Jobs, and rightly so for fostering the innovation, credit score can also be because of Prepare dinner, who has taken the franchise handed to him, and grown it on steroids. The second is that the corporate borrowed $17 billion in 2013, a Prepare dinner departure from a Jobs follow of avoiding debt, and it has added to that debt load over time, although it stays a small slice of general worth:Whereas a lot is made from Apple’s debt foray, it’s value recognizing that Apple continues to be a really flippantly indebted firm on any debt metric, and that if you happen to web the corporate’s appreciable money steadiness out in opposition to its complete debt, its web debt has at all times been damaging (money exceeds debt). In truth, Apple’s use of debt is so gentle that the one rationale for its existence is making a presence within the bond market, simply in case it wants to make use of it extra sooner or later. The third characteristic is that the corporate has been cautious in its forays into new merchandise and markets, particularly outdoors its area, and this exhibits up in two knowledge sequence.The primary is that whereas Apple has acquired greater than 100 corporations, nearly all of them are small, personal expertise corporations with small worth tags, with the intent being bringing their services into the Apple ecosystem after the acquisition. In truth, its largest acquisitions throughout this century are so small that they signify petty money, relative to its money steadiness as an organization. Beats, as an example, which was one in all Apple’s greatest acquisitions price the corporate about $3 billion, a quantity dwarfed by its money steadiness that 12 months, which was greater than $100 billion.The second is that within the final 5 years, as huge tech corporations have gone on an AI capital expenditure binge, Apple has been the outlier, holding again on its AI investments, and this may be seen within the chart under, the place I examine Apple’s capital expenditures to these of the remainder of the Magazine Seven: As the remainder of the group has ramped up its capital investments, with a lot of it going into AI, Apple has held again, and its share of the entire cap ex on the corporations has fallen from 8.04% to three.02% over the interval.In sum, wanting on the adjustments at Apple during the last fifteen years, the corporate has modified from the expansion engine, pushed by disruptions, within the Jobs years to a mature, cash-returning and extra cautious firm beneath Prepare dinner. I’ve posted extra about Apple than about some other firm on the planet (and I’ve a sampling of a few of these posts on the finish of this submit) and have been a shareholder within the firm for important parts of each the Jobs and Prepare dinner tenures. I’ve not at all times agreed with both man, on selections that they’ve made on the firm, however I revered each of them sufficient to view them pretty much as good stewards of my funding. In a world stuffed with CEOs who’re fast to herd to what the consensus view is, I love each males for his or her willingness to face on their beliefs.Imaginative and prescient or Restraint: A Life Cycle Perspective Should you had been to create a profile of Tim Prepare dinner, the supervisor, based mostly upon the alternatives that he has made at Apple throughout his tenure as CEO, two very divergent views emerge. To his admirers, his actions on some fronts (initiating dividends, huge inventory buybacks, borrowing cash) and inaction on different fronts (no huge acquisitions, diffidence on AI investments), signify an train in self-discipline and restraint, preserving the corporate’s crown jewel (the iPhone) and keeping off the bankers and consultants, with their false guarantees. To his critics, and there are fairly a number of, Prepare dinner’s warning has price Apple its disruptor standing, when it might have used its ample money reserves to purchase its method or spend money on into nearly each new enterprise that has bloomed within the final fifteen years. In truth, they level to possibilities that Apple has had to purchase among the greatest stars out there, from Tesla and Netflix greater than a decade in the past to Anthropic, Mistral and Perplexity in more moderen years. It’s unattainable to argue that one facet is true and the opposite facet mistaken, however it’s plain that each pathways (the restrained pathway that Apple adopted and the extra aggressive pathway that it might have taken) embody commerce offs. It’s true that Apple’s restraint has led it to overlook out on among the greatest tendencies in expertise during the last decade, but it surely has additionally averted the overpayment that’s so frequent with excessive profile acquisitions of huge corporations. The argument that Apple could be value much more at this time if it had purchased Netflix or Tesla a decade in the past falls flat for 2 causes. The primary is the choice bias in choosing two corporations that, in hindsight, have emerged as winners, when in actual fact there have been no less than a dozen different worse-performing corporations that had been additionally on Apple’s radar. The second is the presumption that corporations like Tesla or Netflix would have been simply as profitable, owned by Apple, as they had been as stand alone enterprises. The conflict of company cultures that may have ensued if Apple had purchased both Tesla, an organization that reinvents its enterprise narrative each few hours, or Netflix, an entity that makes content material in amount with the hope that some it sticks, would have been epic, with the chance that each Apple and its acquired goal would have gone down in flames. Extra typically, although, the query of whether or not you need a visionary or a disciplined enterprise builder on the high of a agency shouldn’t be one which has a simple reply, because it depends upon the agency in query. In my work on company life cycles, I deal with the administration expertise which might be wanted most in an organization, based mostly upon the place it’s the life cycle, and which will assist deal with the selection between imaginative and prescient and restraint:With younger corporations, imaginative and prescient dominates, as managers work to sway traders, staff and nascent clients that their services or products will discover a market. Because the imaginative and prescient takes maintain, changing it into industrial services requires buying and selling off some parts of imaginative and prescient for pragmatism, within the curiosity of getting the enterprise going. As services discover demand amongst clients, enterprise constructing turns into a key difference-maker, with the grunt work of selling, manufacturing amenities and provide chains coming into play. Assuming that you’ve made it via these three phases, the commerce offs of scaling up come into focus, and as you hit market limits, success depends upon being opportunistic find new merchandise and markets, however provided that they exist. In company center age, pathways to straightforward development, particularly at scale, change into troublesome to search out, and to the extent that worth comes from moats and core merchandise, taking part in protection in opposition to rivals takes precedence. Lastly, in decline, a part that no firm ever needs to enter, however is inevitable sooner or later, that you must be keen to shrink a agency, shutting down companies that now not ship worth and promoting different belongings to excessive bidders. Given these very divergent administration features, it ought to come as no shock that there isn’t a prototype for the right CEO, McKinsey and Harvard Enterprise College blueprints however. Considered on this framework, I might argue that Apple has been fortunate with its final two CEOs, each when it comes to persona and when it comes to sequence. When Steve Jobs rejoined Apple in 1997, the corporate had hit all-time low, and with little to supply in liquidation, his imaginative and prescient allowed for a reincarnation, with disruptions main the way in which, and as we famous earlier on this submit, having a powerful chief working officer in Tim Prepare dinner made the distinction. The Apple that Tim Prepare dinner inherited, when he turned CEO, was a really completely different entity, already the world’s largest market cap firm, with a superlative franchise within the iPhone. In company life cycle phrases, Apple was a mature development firm, and what Prepare dinner lacked in opportunism , he made up for by defending Apple’s greatest product line(iPhone) and augmenting worth with increments just like the app retailer and gadgets. That stated, whereas every of those males created worth for shareholders, I do not suppose that both could be considered extremely, if you happen to swapped their tenures when it comes to timing. I do not suppose Tim Prepare dinner would have been in a position to carry Apple from its near-demise to being on high of the company universe, if he had change into CEO in 1997, and I feel Steve Jobs would have been ill-suited to the Apple that was in existence in 2011. Ageing, Administration Mismatches and Company Governance In a submit from a number of years in the past, I used the connection between CEO sort and company lifecycle to look at why administration mismatches happen at corporations, and the implications of that mismatch. Particularly, there are three confounding components that may make matching up CEO to firm, given the place it’s within the life cycle, difficult:Like people, corporations age, however in contrast to people, the charges at which completely different corporations undergo the life cycle may be wildly completely different. An infrastructure or manufacturing firm can take many years to change into operational, adopted by prolonged phases of development and maturity, earlier than going into decline. In distinction, a tech firm can have explosive development early in its life, spend a short interval having fun with the fruits of its success as a mature firm earlier than declining precipitously. As a consequence, managers and traders who use chronological age as their company growing older metric can misjudge the place they’re on the life cycle.Whereas growing older is inevitable for each people and companies, some mature and even declining companies can discover pathways, both via happenstance or administration selections, to rediscover their youth. These companies change into the stuff of legend, and they’re the themes of books and enterprise college case research, and their CEOs are elevated to administration deities. The narratives constructed round corporations that reincarnate and the CEOs atop these corporations additionally feed into administration incentives and habits. The story of Steve Jobs at Apple has been informed and retold, however it’s value remembering that for each story of reincarnation, there are 100 tales you’ll be able to inform about different CEOs who tried to observe the Apple playbook, spending billions on reinventing their corporations, with little to point out when it comes to payoffs. (See my posts on Marissa Mayer at Yahoo! and on Blackberry.) In essence, the glorification of CEOs who guess huge on turnarounds at mature or declining corporations, and win, units up CEOs dealing with comparable circumstances to behave like riverboat gamblers, when making administration selections at their corporations. In spite of everything, if their bets repay, they be a part of the legend crowd, and if they don’t, they contend that they did their finest, and that circumstances conspired to carry them down.The underside line is that there are a selection of the way in which you’ll find yourself with CEO mismatches – a CEO who can’t adapt to the altering calls for of an growing older enterprise, a hiring mistake and even adjustments within the macro atmosphere, and when these mismatches happen, is is inevitable that there can be friction between the CEO and shareholders. In a way, nearly all company governance challenges may be traced again to administration mismatches, and the ability (or the absence of it) that shareholders have to repair these mismatches:Whereas Tim Prepare dinner’s time as CEO of Apple is now seen via rose-colored lens, it’s value remembering that Apple was focused repeated early in his tenure by activist traders. Whereas among the adjustments that these activists had been pushing for had been warranted, some weren’t, and Prepare dinner deserves credit score for not capitulating. Carl Icahn, as an example, wished Apple to extend its debt considerably, borrowing a whole lot of billions, however I took challenge along with his argument that Apple might borrow this cash on the low charges that he was extrapolating. A few years later, David Einhorn made his play, arguing that Apple ought to challenge most well-liked shares with a 4% dividend yield, and I famous that most well-liked inventory might carry with it all the cashflow commitments of debt, with not one of the tax benefits. I’ve lengthy argued that the very best protection a administration has in opposition to activist traders is delivering superior efficiency and returns, and Tim Prepare dinner delivered on each dimensions, and confronted little greater than sniping from disgruntled traders in his later years as CEO. Within the final 4 years, the criticism has come primarily from analysts who fault his warning, and argue that Apple dangers falling behind its extra aggressive rivals within the AI race, however right here once more, Prepare dinner has stood his floor.Administration Transitions, Previous and Current – The Magazine Seven I do not envy John Ternus, who’s Prepare dinner’s inheritor obvious, as a result of he’s following two CEOs who had been immensely profitable, albeit in numerous methods. If there are classes he can study from each Jobs and Prepare dinner, they embody the next:Discover your personal path: There can be stress from some traders to be similar to Jobs, and go for giant disruptions, or from others to mimic Tim Prepare dinner, and go away Apple as a money machine. Whereas it could take time, Ternus has to search out his personal path as CEO, based mostly on not solely what he brings to the desk, given his background in laptop {hardware}, however on what Apple’s strengths are as an organization in 2026 and the markets it’s dealing with proper now.Adapt to the corporate you’re managing: Simply because the Apple that Jobs took over in 1997 was very completely different from the Apple that he handed over to Prepare dinner in 2011, the corporate that Ternus takes over is completely different from those handed over in both of the prior iterations. If you end up on the helm of one of many largest market cap corporations on the planet, it’s important to begin with the popularity that any new services or products that you just introduce should be enormous to make a dent within the working metrics (revenues and earnings) or market capitalization. As well as, the franchise that holds up the corporate’s money machine is the iPhone, and Ternus can’t afford to take his eyes of that prize. Hold the suggestions loop open: If you end up an organization value trillions, with legions of shareholders, and a whole lot of analysts, you’ll have recommendation meted to you consistently on what you need to or shouldn’t do. A lot of that recommendation can be dangerous, and must be dismissed, however a few of it’s value listening to and maybe transformed into coverage. As well as, as CEO, I hope that Ternus views the market worth as a crowd judgment on Apple’s actions quite than the product of hypothesis, and accepts that whereas that judgment may be mistaken, it must be taken severely. I want Mr. Ternus the very best, for purely egocentric causes. As a Mac and Apple machine consumer, I would like the corporate to prosper and proceed to make merchandise that I can proceed to make use of each day, and as a shareholder, I would like my funding to do nicely. The eye, on this submit has been on the administration transition at Apple, however administration transitions are half and parcel of each firm, with the adjustments typically pressured on the corporate and typically voluntary. Increasing the dialogue of administration to the opposite corporations within the Magazine Seven can present us with a chance to look at administration transitions which have both already occurred or that can occur sooner or later, and the following frictions:At Microsoft, the one firm on this group that traces its classic again to Apple, there have been two CEO transitions, from Invoice Gates to Steve Ballmer in 2000, and from Ballmer to Satya Nadella in 2014. Whereas Gates constructed Workplace and Home windows into money cows, and Ballmer preserved them, Nadella created his personal pathway to reincarnation by build up a cloud enterprise that’s now the dominant supply of revenues for the corporate. By partnering early with OpenAI on LLMs, and investing massively in knowledge facilities, Nadella is now betting that AI can present an additional enhance to the corporate’s operations, maybe setting the stage for a second rebirth.Amazon has seen a administration transition, the place a legendary founder (Bezos) left the agency in 2021, and his successor (Andy Jassy) has taken the reins, with remarkably little fanfare. Like Nadella, although, Jassy is betting huge on AI being a development and worth driver, and the success or failure of that guess will largely decide how his stint as CEO will get judged.Alphabet gives a case examine of an organization that attempted to separate the distinction, by separating its money cow (Google promoting) from its different companies, naming Sundar Pichai because the CEO for Google, whereas remaining atop the opposite Google companies (the bets in Alphabet). That experiment has struggled to ship, as the opposite companies remained earth-bound and in 2019, and Pichai took over as CEO of Alphabet as nicely. Over its lifetime, Alphabet has been immensely profitable in developing with services that catch public consideration, whether or not or not it’s its improvement of the Android working system or its work on Waymo or Gemini, but it surely has struggled to transform these successes into revenues and working earnings.In three of the businesses (Tesla, Meta and Nvidia), founders stay CEOs, although they create very completely different views and personalities into their roles. As I famous in my final submit on SpaceX, Musk has veered between genius and eccentricity in his stewardship, however shareholders at Tesla have largely benefited from the rollercoaster journey. At Meta, Zuckerberg has been a shrewd businessperson in his administration of his social media holdings, with savvy acquisitions of Instagram and Whatsapp boosting his ad-driven ecosystem, however he has additionally been headstrong in his pursuit of ventures that he feels are the “subsequent huge factor”. His costly failed guess on the Metaverse led some traders to query his governance, and plenty of of those traders fear that his guess on AI will play out equally. Lastly, on Nvidia, the corporate’s hovering market capitalization and large success with AI chips has pushed Jensen Huang into the highlight, however lower than a decade in the past, there have been questions on his administration as nicely.The truth that all six of those corporations have invested closely in AI is a lead-in to what may very well be the important thing take a look at for administration in any respect of them. If the AI investments repay and ship worth, Nadella will cement his legend standing, Jassy may have created his personal legacy at Amazon, the Alphabet experiment will lastly repay, and the founder-run corporations may have extra room to run. If the AI investments fail, although, Nadella’s reincarnation repute will take a success and Jassy’s place atop Amazon can be at-risk. The AI failure may even increase doubts about Alphabet’s capability to develop past promoting and the rumblings about Zuckerberg’s huge bets will get louder, however at these two corporations, it’s unclear what traders, regardless of how giant their holdings are, can do, since they’ve acquiesced to a voting share construction at these two corporations that has diminished them to bystander standing. At Alphabet, Brin and Web page management 51% of the voting rights, with lower than 10% possession, and at Meta, Zuckerberg controls 57% of the voting rights, with about 13% of share possession. An Ode to Restraint Whereas there are numerous who examine to Tim Prepare dinner to Steve Jobs and discover him wanting on imaginative and prescient and aptitude, I’m grateful, as an investor in Apple, for the restraint and self-discipline that he dropped at the job. That gratitude will keep intact even when Apple’s warning on AI seems to be a mistake, for the reason that restraint and rectitude that Prepare dinner dropped at his job are administration qualities that considerably undervalued. I do not educate from or write instances, however I might like to see extra enterprise college instances about CEOs like Prepare dinner who should not simply swayed by the temptation of extra development and ego-driven acquisitions. I cherished the Steve Jobs film, however I do not count on to see a Tim Prepare dinner film anytime quickly, and whereas that’s comprehensible, it additionally explains why we’ll proceed to have too many CEOs at corporations viewing themselves as saviors, playing shareholder cash on turnarounds and rescues, when the higher pathway could be acceptance and shrinkage. I imagine that traders lose more cash from corporations attempting to do an excessive amount of quite than from them doing too little, and from overreaching than from underachieving.YouTube VideoMy posts on AppleApple: Ideas on Bias, Worth, Extra Money & Dividends (March 1, 2012)Apple: Know when to carry ’em, know when to fold ’em (April 3, 2012)Feelings, Intrinsic worth and Dividend Clienteles: The Apple postscript (April 6, 2012)Apple’s Crown Jewel: Valuing the iPhone Franchise (August 29, 2012)The 12 months in Evaluate: Apple’s Universe (December 2012)Are you a price investor? Take the Apple Check! (January 2013)Again to Apple: Ideas on worth, worth and the boldness hole (February 7, 2013)Monetary Alchemy: David Einhorn’s worth play for Apple (February 8, 2013)Apple: Information, Noise and Worth (April 30, 2013)Love the corporate! Love the product! Love the inventory! (September 9, 2013)Watch the Hole: Apple’s Lengthy and Twisted Journey (April 2014)The Race to the High: The Duel between Alphabet and Apple (February 2016)Icahn exits, Buffett enters: Whither Apple (June 2016)Apple: The Best Money Machine in Historical past (February 2017)Investor Whiplash: On the lookout for Closure with Apple and Alphabet (December 2018)My guide on the company life cycle
Classes from the Tim Prepare dinner Legacy