Sofia Carollo and Natalie Burr
Whereas financial coverage units short-term coverage charges, households and companies borrow at various time horizons. How a coverage choice reshapes the entire yield curve subsequently issues. We hint the reactions of yields in slender home windows round UK financial coverage bulletins throughout two dimensions: a ‘degree’ shock that shifts the whole curve and a ‘slope’ shock that adjustments its steepness. We discover {that a} degree shock impacts CPI inflation greater than a slope shock does; this result’s troublesome to get well from surprises that conflate the 2 dimensions. So, the coverage fee tells solely a part of the story: two curves thought-about equal from a stance perspective can result in totally different inflation outcomes. Policymakers should be attuned to those differing results.
The entire yield curve issues for financial coverage transmission
The Financial Coverage Committee (MPC) units Financial institution Charge, the in a single day coverage fee. However that isn’t a fee households or companies ever actually pay (Burr and Willems (2024)). What they face are deposit charges, mortgage charges, or different borrowing prices, and these stretch throughout totally different horizons, from in a single day loans to mortgages spanning many years.
Measuring the results of financial coverage subsequently means wanting on the complete curve, not only one fee, and cleanly separating out the results on the curve that stem from a given coverage announcement from different elements. Modifications in Financial institution Charge anchor the very quick finish of the yield curve, however a coverage choice can ripple throughout the whole curve. Such results could be meant by policymakers – by way of unconventional instruments akin to quantitative easing and ahead steering (Busetto et al (2022)) or by way of policymakers’ communication in regards to the outlook and certain path of coverage. On the similar time, the yield curve is just not fully beneath the management of financial coverage makers – different elements akin to expectations of future charges, the financial outlook, anticipated future fiscal coverage, and danger premia additionally affect each the extent, and steepness of the curve.
Measuring degree and slope results
Fairly than monitoring remoted shifts at particular person maturities on the curve, we individually hint actions to the extent and slope of the curve. That is essential as actions in lengthy charges are correlated with actions briefly charges however attain the financial system via totally different channels. This evaluation additionally issues for higher understanding the interplay between standard and unconventional coverage instruments on macro-outcomes (Mann (2025)). The extent and slope elements seize the first dimensions alongside which yields transfer and have turn into commonplace instruments for analysing yield curve dynamics (Litterman and Scheinkman (1991)).
Following Odendahl et al (2024), we decompose UK financial coverage into its results on the ‘degree’ and ‘slope’ of the yield curve. We depend on a mixture of spot and ahead charges to signify the entire curve: 3 month and 1 yr spot charges, plus the 1y1y, 2y1y, 4y1y and 9y1y ahead charges. A ahead fee is agreed at present for borrowing over a future window, so 2y1y is the one-year fee anticipated to use in two years. Not like lengthy dated spot charges, which common anticipated quick charges throughout a number of horizons, ahead charges isolate particular factors on the curve and subsequently present a cleaner learn on how totally different maturities form it.
To determine financial coverage surprises, we observe yield actions in 30-minute home windows round 305 UK financial coverage bulletins since operational independence in 1997, based mostly on the database from Braun et al (2025). The high-frequency method of utilizing slender home windows round bulletins offers us confidence that the noticed yield actions replicate financial coverage moderately than different information.
We then summarise these shock actions in yields utilizing principal element evaluation (PCA), which filters out idiosyncratic volatility and extracts the widespread actions throughout maturities. Simply two elements clarify round 75% of the variation in yields on MPC announcement days. The primary resembles a close to parallel shift within the curve, which we interpret as a degree issue, whereas the second captures adjustments in its steepness, which we interpret as a slope issue. Importantly, these patterns emerge from the info moderately than being imposed a priori. Observe that our elements are empirical approximations of joint yield dynamics that resemble degree and slope results however will not be structurally modelled, so the ensuing degree shock isn’t a totally parallel shift, and the slope shock isn’t a uniform tilt.
Chart 1: Principal elements throughout spot and ahead yields (a) (b)
Sources: Authors’ calculations utilizing yield curve information from Bloomberg Finance L.P., Tradeweb and Financial institution calculations.
(a) First principal element, degree issue.
(b) Second principal element, slope issue.
From the PCA loadings, we then assemble degree and slope surprises for every announcement as weighted sums of yield surprises throughout maturities. Lined up by date, these kind the extent and slope shock sequence proven beneath. These shock sequence present empirical measures of the 2 dimensions via which financial coverage bulletins transfer the yield curve. We use them as proxies for degree and slope financial coverage shocks within the macroeconomic evaluation that follows.
Chart 2: Financial coverage surprises: degree and slope elements over time (a) (b)
Sources: Authors’ calculations utilizing yield curve information from Bloomberg Finance L.P., Tradeweb and Financial institution calculations.
(a) Surprises to the extent of the curve.
(b) Surprises to the slope of the curve.
Tracing the macroeconomic results from ‘degree’ and ‘slope’ financial coverage shocks
How do the ‘degree’ and ‘slope’ financial coverage shocks have an effect on the UK macroeconomy? To quantify this, we estimate a Bayesian vector autoregression (BVAR). Constructing on the proxy SVAR framework of Arias et al (2021), that permits for a number of exterior devices, the proxies enter collectively as two exterior devices. As a result of the PCA elements are orthogonal by building, the impulse responses signify the marginal impact of every shock independently of the opposite.
The mannequin is estimated as a single VAR in log-levels on month-to-month information. The variables embody UK nominal spot and ahead yields at varied horizons (3m, 1y, 1y1y, 4y1y and 9y1y), UK asset costs (£ERI, FTSE All Share, Funding Grade Company Bond Spreads) and seasonally adjusted actual GDP and CPI, in ranges. Our degree and slope shock sequence function exterior devices, embody within the VAR to proxy the shocks. The VAR consists of 12 lags, and the pattern interval is June 1997 to December 2019.
Degree and slope shocks generate totally different macroeconomic outcomes
We begin by asking what occurs when gilt yields fall throughout the entire curve. A adverse degree shock, normalised to a 25-basis-point decline within the 1y yield, results in a major fall in yields throughout maturities on affect (Chart 3). Additional, we observe a decline in credit score spreads, rise in fairness costs and depreciation of the alternate fee point out a broad easing in monetary circumstances, supporting each demand and inflation. Certainly, GDP picks up regularly, with the biggest achieve after a couple of yr. The patron value degree responds with a delay, rising slightly below a yr after the shock and notably after the pickup in output. A optimistic, statistically important value response is just not simply obtained in UK information, the place small VARs usually produce a value puzzle. Our outcomes could level to the worth of utilizing the total yield curve to construct the shocks: separating degree from slope separates two dimensions of curve variation, so the value response to a degree shock is much less more likely to be diluted by slope actions.
Chart 3: Impulse response features to a 25-basis-point adverse degree shock
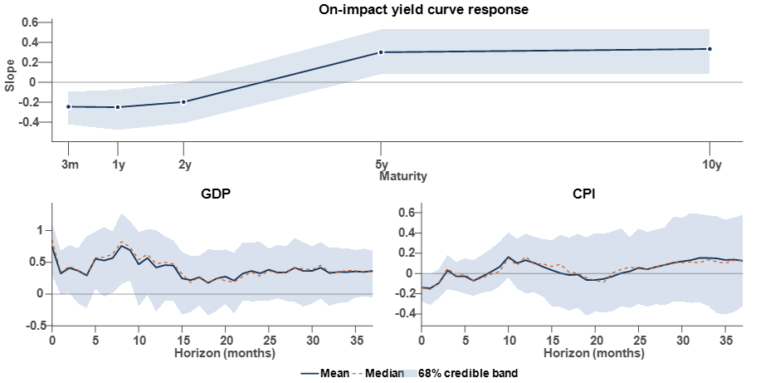
In distinction, a slope shock steepens the curve by easing quick‑time period charges whereas tightening additional out. A optimistic slope shock, ie, a 25-basis-point on-impact fall briefly‑time period yields, boosts GDP whereas leaving CPI broadly unchanged (Chart 4). Whereas our linear framework implies {that a} flattening shock would produce symmetric results in the wrong way, financial coverage transmission could also be uneven, with easing and tightening having totally different macroeconomic results – as proven by Busetto (2024) and Stenner (2021), amongst others, and Lloyd and Ostry (2024) for unconventional coverage. We discover that the easing on the quick finish supplies close to‑time period stimulus to exercise, which greater than offsets the modest tightening at longer maturities. The worth degree, in contrast, seems comparatively insensitive to both finish of the curve on this case. That is per the center section remaining anchored. The slope shock behaves very like a short-end (goal) shock, as in Braun et al (2025), the place the shock has a major impact on output however a weak value puzzle impact. This may increasingly additional recommend that it’s extra the extent than the slope dimension of the curve related to the value response, and one thing that shocks specializing in remoted segments of the curve may blur.
Chart 4: Impulse response features to a steepening slope shock
Financial coverage implications
Our outcomes spotlight that the results from a coverage announcement transcend the change in a single rate of interest alone. We now have proven that various kinds of adjustments to the yield curve related to financial coverage shocks have distinct macroeconomic results, even once they indicate the same change within the common degree of yields.
We discover that degree and slope shocks will not be interchangeable: they redistribute adjustments throughout maturities that transmit with totally different energy and timing. It’s not that exact maturities ‘matter extra’ (a separate query we don’t cowl within the put up). Whether or not a given transfer in gilt yields tightens or loosens the financial system relies upon crucially on the place alongside the curve it happens, and whether or not that transfer is broad‑based mostly or concentrated at explicit maturities – impacts the energy and timing of financial transmission to the mixture financial system.
Whereas policymakers can not exert exact management over the whole yield curve, our outcomes recommend that they need to be attentive not simply to a median change in yields, however to the configuration of these adjustments throughout maturities, when gauging the possible energy and timing of financial transmission.
Sofia Carollo works within the Financial institution’s Financial and Monetary Circumstances Division and Natalie Burr works within the Financial institution’s Exterior MPC Unit.
If you wish to get in contact, please electronic mail us at bankunderground@bankofengland.co.uk or depart a remark beneath.
Feedback will solely seem as soon as permitted by a moderator, and are solely revealed the place a full title is equipped. Financial institution Underground is a weblog for Financial institution of England workers to share views that problem – or help – prevailing coverage orthodoxies. The views expressed listed below are these of the authors, and will not be essentially these of the Financial institution of England, or its coverage committees.
Share the put up “Financial coverage transmission: it’s all within the curve”