Within the knowledge replace posts this 12 months, I’ve wended my means from the macro (equities collectives, the bond market and different asset lessons) to the micro, beginning with hurdle charges and returns in posts 5 and 6 and the debt/fairness alternative in my seventh put up. On this put up, I’ll have a look at the choice by companies on how a lot money to return to their homeowners, and in what kind (dividends or buybacks), and the way that call performed out globally in 2025. I’ll argue that dividend coverage, greater than some other facet of company finance, is dysfunctional each for the companies that select to return the money and the buyers who obtain that money. Additionally it is telling that there are lots of who appear to view the very act of returning money as an indication of failure on the a part of companies that accomplish that, though it’s the finish sport for each profitable enterprise.
The Dividend Resolution
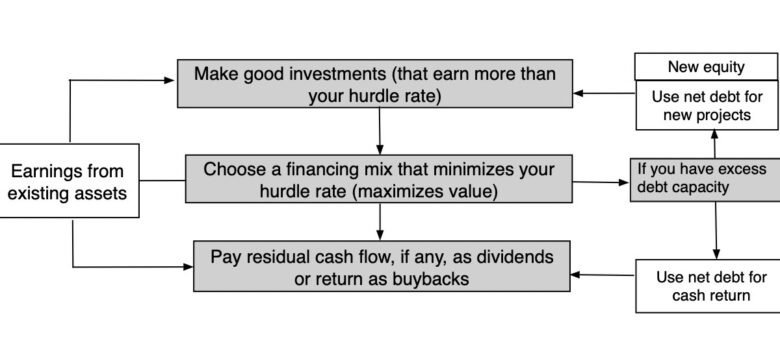
I begin my company finance lessons with an outline of three core choices that each agency has to make in the middle of enterprise, beginning with the funding determination, the place you attempt to spend money on tasks and investments that earn greater than your hurdle charge, transferring on to the financing determination, the place you determine on the combo of debt and fairness to make use of in funding these investments, and ending with the dividend determination, the place companies determine how a lot money to return to their homeowners. Within the case of privately owned companies, this money might be withdrawn by the homeowners from the enterprise, however in publicly listed firms, it takes the type of dividends or buybacks. In line with the notion that these are the cashflows to fairness buyers, and that these money flows ought to characterize what’s left after (residual) in any case different wants have been met, dividends ought to replicate that standing and, no less than in precept, be set after investing and financing choices have been made:
That utopian view of residual money being returned to shareholders is put to the take a look at by two real-world realities that usually govern company dividend coverage:
Inertia: In lots of firms, dividend coverage is ready on auto pilot, with dividends this 12 months set equal to dividends within the final 12 months. It’s for that purpose that the phrase I’d use to explain dividend coverage, no less than relating to standard dividends, is ‘sticky’, and you’ll can see that stickiness at play at US firms, should you observe the proportion of firms that improve dividends, lower dividends or depart them unchanged yearly.
In each single 12 months, from 1988 to 2025, the proportion of firms that pay the identical dividends that they did within the earlier 12 months outnumbers firms that change dividends, and when dividends are modified, they’re extra more likely to be elevated than decreased.
Me-tooism: In most firms, managers look to see group dividend coverage for steerage on how a lot, if any, to pay in dividends. Thus, if you’re a financial institution or a utility, it’s possible that you’ll pay excessive dividends, as a result of everybody else within the sector does so, whereas expertise firms pays no or low dividends, as a result of that’s business follow. Whereas there are good explanation why some business teams pay extra dividends than others, together with extra predictable earnings and decrease progress (and funding wants), hewing to the peer group implies that there might be outliers in every group (fast-growing banks or a mature expertise firms) that might be trapped into dividend insurance policies that do not go well with them.
When sustaining or growing dividends turn out to be the top sport for a enterprise, you unleash dividend monsters, the place investing and financing choices are skewed to fulfill dividend wants. Thus, a agency could flip away good investments or borrow rather more than it ought to as a result of it feels the necessity to maintain dividends.
I’ve lengthy argued that dividends, of their sticky kind, are unsuitable as money returns to shareholders, however for a lot of the final century, they remained the first or typically solely method to return money to shareholders. Whereas shopping for again inventory has at all times been an choice accessible to US firms, its use as a scientific means of returning money picked up within the Eighties, and within the years since, inventory buybacks have turn out to be the dominant method to returning money for US firms:
As you possibly can see, within the final decade, greater than 60% of money returned to shareholders took the type of buybacks. The first purpose, for my part, is that buybacks, in contrast to dividends, are versatile, with firms typically reversing buybacks, if macro circumstances change, as was the case in 2008 and 2020. There are different causes which have been provided for the explosive progress in buybacks, however none of them are as important. There are some who’ve argued it’s stock-based compensation for managers that’s pushing them away from dividends to inventory buybacks, however that rationale makes extra sense for inventory choices, the place inventory costs mater, than for restricted inventory. The truth is, at the same time as extra firms shift to restricted inventory as their inventory compensation mechanism, buybacks have continued to climb, and they’re simply as excessive at firms that don’t have any or very low inventory based mostly compensation as at firms with excessive stock-based compensation. Investor taxes are alway within the combine, since buyers are sometimes taxed at totally different charges on dividends and capital beneficial properties, however modifications in tax regulation within the final twenty years have lowered, if not eradicated, the tax disadvantages related to dividends, reducing towards this argument.
I do know that there are lots of buyers, particularly within the worth investing camp, and fairly just a few economists, who imagine that the shift away from dividends to buybacks is unhealthy, albeit for various causes. I’ll return to lots of the myths that revolve round buybacks later on this put up.
A Rational Money Return Coverage
If you happen to had been designing a smart money return coverage, it has to begin with an evaluation of how a lot money there may be accessible for a agency to return. Since that “potential dividend” ought to be the money left over after taxes are paid, reinvestment has been made and debt repaid, it may be computed pretty merely from the assertion of money flows, as free cashflow to fairness:
Observe that free money circulation to fairness begins with fairness earnings, converts these earnings to money flows by including again depreciation and different non-cash expenses, after which netting out capital expenditures and modifications in working capital, with will increase (decreases) in working capital lowering (growing) money flows. It’s accomplished by incorporating the money flows from debt, with debt issuances representing money inflows to fairness buyers and debt repayments changing into money outflows. Can free money flows to fairness be unfavourable? Completely, and it will possibly occur both as a result of you’re a money-losing firm, too deep within the gap to dig your self out, or perhaps a money-making firms, with giant reinvestment wants? Clearly, paying out dividends or shopping for again inventory when your free money flows to fairness is violating the easy rule that if you’re in a gap, you could cease digging.
In case your free money circulation to fairness is constructive, you possibly can select to return it to shareholders, both within the type of dividends or buybacks, however you aren’t obligated to take action. The truth is, when you’ve got constructive free cashflows to fairness and also you select to return none or solely a portion of that money circulation, the distinction accumulates right into a money stability. If you happen to select to return greater than your free cashflow to fairness, you’ll both should deplete an present money stability, or should you run out of money, exit and lift recent capital.
An organization that systematically holds again on money that it might have returned will, over time, accumulate a big money stability, however that, by itself, could not set off a shareholder response, if shareholders belief the corporate’s managers with their money. In any case, money invested in liquid and riskless investments, like treasury payments and business paper, is a impartial (zero NPV) funding, and leaves shareholders unaffected. If you happen to do not belief administration to be disciplined, although, it’s possible you’ll punish an organization for holding an excessive amount of money, successfully apply a “lack-of-trust” low cost to the money. The image beneath supplies a framework for considering by the money return determination, and the way it will play out in markets.
As you have a look at the interaction between earnings, funding wants and potential dividends, you possibly can already see why you must anticipate money return insurance policies to alter over an organization’s life cycle:
The money returns you see on this graph ought to largely map on to frequent sense, with start-ups and really younger firms, typically money-losing and requiring substantial reinvestment to develop, having unfavourable free money circulation to fairness (thus requiring fairness infusions). Younger progress firms are normally self-funding as a result of inside money flows could rise to cowl reinvestment, however these money flows will not be sufficient to pay dividends. Mature progress firms have sufficient money to return, however keep on with buybacks, as a result of they worth flexibility. Mature steady firms characterize the candy spot for dividend paying, since they’ve little in reinvestment wants and huge predictable earnings and money flows. As with the whole lot else within the growing old course of, firms that refuse to behave their age, i.e., younger firms that select to pay dividends or purchase again inventory or mature firms that insist on holding on to money, injury themselves and their shareholders.
Dividends in 2025
I’ll begin the evaluation of how a lot firms returned to shareholders in 2025 by taking a look at standard dividends paid by firms, utilizing two metrics. The primary metric is the dividend payout ratio, the place I divide dividends paid by internet earnings, however provided that internet earnings is constructive; if internet earnings is unfavourable, and dividends receives a commission, the payout ratio is just not significant:
As you possibly can see the median payout ratio is about 35% (59%) for US (world) firms, however in each samples, most firms don’t pay dividends. There’s a sizable subset of firms (12% of US and 14% of worldwide firms) that pay out greater than 100% of earnings as dividends, with a number of causes for that outsized quantity together with a foul earnings 12 months, a want to extend monetary leverage and partial liquidation plans all coming into play.
The second metric is the dividend yield, computed by dividing dividends paid by market capitalization, or dividends per share by the market value per share. Within the graph beneath, I have a look at the distribution of dividend yields throughout firms within the graph beneath, in 2025:
Once more taking a look at solely dividend paying companies within the US and world samples, the median dividend yield was 1.10% for the previous and a couple of.43% for the latter, with main divergences throughout sub-regions; observe that the p.c of dividend paying companies in the US has dropped beneath 30% and even globally, lower than half of companies pay dividends. The dividend yield ties into the price of fairness dialogue that I initiated in my fifth knowledge replace, the place I described the price of fairness as the speed of return that buyers anticipate to make on their fairness investments. In the US, for example, that anticipated return was about 8.50% initially of 2026, which might point out that if you’re an fairness investor, it’s value appreciation that you’re depending on, for the majority of your fairness return.
The dividend yield for equities has declined over time, with the drop off being most noticeable in the US. The graph beneath appears on the dividend yield on the S&P 500 from 1960 to 2025, and the way that quantity has turn out to be a smaller and smaller portion of the general anticipated return on shares (which I compute with the implied fairness return method):
In 1960, about half of your anticipated return on shares got here from dividends and that statistic has trended downwards for the previous couple of a long time, and in 2025, it represented lower than 15% of the entire return on shares.
As a last a part of this evaluation, I checked out dividend yields and payout ratios, damaged down by sector, for each US and world firms:
As you possibly can see, the sectors with the very best proportion of companies paying dividends are financials, actual property and utilities, for each US and world firms, and client product firms take part that group, for world firms. By way of payout ratios, the identical three sectors dominate, with vitality and actual property returning greater than 200% of internet earnings as dividends, in 2025, and posting dividend yields in extra of 6%. Know-how firms and communication companies have the bottom p.c of dividend paying firms and the bottom dividend yields and payout ratios. The drop in dividend yields over time for the market, the decline in dividend paying companies and the focus of dividend paying companies in some sectors has put outdated time worth investing to the take a look at. Ben Graham’s technique of principal safety was constructed round shopping for giant dividend paying companies and holding on for the long run and it has hit a wall. Any investing technique constructed round dividends will lead to a portfolio composed of mature and declining companies, and even should you settle for that actuality, these companies are more and more concentrated in actual property, banking and utilities.
Buybacks – Myths and Realities
As buybacks have soared in the US, misconceptions and myths about buybacks have additionally surged, with some myths used to again up the argument that buybacks are unhealthy and will due to this fact be banned and others offered as the premise for buybacks nearly as good, representing cannot-lose methods to beat the market. I’ll begin with the myths which can be used to argue towards buybacks first, earlier than transferring on to people who are used to justify it:
1. Myths in favor of the argument that buybacks are unhealthy and ought to be restricted or stopped
Fable 1.1: Buybacks are a US phenomenon
Actuality 1.1: Buybacks have gotten a world phenomenon
When US companies first began shopping for again inventory within the Eighties, it’s true that’s was nearly totally or primarily a phenomenon restricted to the US, with giant components of the world proscribing or banning the usage of buybacks to stop value manipulation by firms. That’s not the case, and firms all over the world have taken to buybacks, as a versatile different to dividends, have adopted the follow. In 2025, I checked out dividends and buybacks from firms all over the world:
Corporations in the US are nonetheless within the lead within the buyback race, shopping for again $1.153 trillion in inventory in 2025, near 60% of general money returned. Canada, the UK, and Japan will not be far behind with greater than 35% of money returned taking the type of buybacks, and the EU and environs, typically the slowest to adapt to alter, noticed nearly 29% of money returned in buybacks. For quite a lot of causes, together with poor company governance and regulatory restrictions, Africa & the Center East, Jap Europe and far of south and southeast Asia return comparatively little in buybacks.
Fable 1.2: Buybacks are wasteful and scale back company funding
Actuality 1.2: Buybacks redirect company funding from mature firms to progress companies
The argument that buybacks are wasteful typically come from utilizing a agency as a self-contained financial unit, and noting that cash used on buybacks can’t be reinvested again into the agency. That’s completely true, however the money that goes into buybacks goes to buyers and principally goes again into the market, as investments in different firms. Whereas there are clearly exceptions, the place firms that ought to be investing again into their companies use that money to buyback inventory, the businesses which can be the largest consumers of their very own inventory are mature companies with inadequate funding alternatives and the businesses which have the money redirected into them want that money to fund their progress. You possibly can see this play out, while you have a look at inventory buybacks damaged down, by age decile (based mostly upon company age) for US and world firms:
As you possibly can see, youthful firms will not be solely much less possible to purchase again inventory, but in addition return much less money in dividends and buybacks, no less than as a p.c of market capitalization than older firms. Utilizing the life cycle perspective, this implies that money is rotating out of older, extra mature companies into youthful companies. I’d argue that the distinction between geographies the place buybacks are uncommon and geographies the place buybacks are frequent is just not in how a lot company funding there may be, however in the place that funding is directed, with the previous investing investing again into declining companies and the latter funding larger progress and newer companies.
Fable 1.3: Buybacks are funded with debt are are making firms too extremely levered
Actuality 1.3: Buybacks are primarily funded with free money flows to fairness and at the same time as buybacks have surged, debt ratios have decreased.
I’m not an incredible believer in case research exactly as a result of anecdotal proof is spun into backing priors and preconception.s There are, after all, companies which have dug themselves right into a gap by shopping for again immense quantities of inventory, and funding these buybacks with debt, however the combination debt ratios for US non-financial service companies, with debt to capital ratios measured towards each e-book and market, have declined during the last 4 a long time, at the same time as buybacks have surged.
In case your response is that not all firms purchase again inventory, and that debt ratios has risen at firms that purchase again inventory, a comparability of debt ratios (debt to EBITDA and debt to capital) for US companies that purchased again inventory in 2025 versus these that don’t dispels that argument:
If companies are borrowing cash to fund buybacks, it’s clearly not displaying up within the statistics, since firms that purchased again inventory had a lot decrease debt masses than the businesses that didn’t, a simplistic comparability, however one which carries heft.
Fable 1.4: Buybacks are value-destroying as a result of firms have a tendency to purchase again their very own inventory when costs are too excessive
Actuality 1.4: Buybacks, at any value, can neither add nor destroy worth. They’ll simply switch worth
Warren Buffett was late to the buyback get together, however when he initiated buybacks at Berkshire Hathaway, he launched a constraint, which is that he would do buybacks provided that he believed that the corporate’s inventory value was lower than intrinsic worth. He, after all, had the credibility to make this assertion, however most firms do not impose this constraint and there may be proof that they typically purchase again their shares when inventory costs are larger than they’re decrease. That does appear to be worth destruction, however a money return can neither add nor destroy worth, however it will possibly switch wealth. Within the case of inventory buybacks at too excessive a value, wealth is transferred from those that stay loyal shareholders within the agency to those that promote their shares. Whereas there may be hand wringing about this, you will have a alternative, as a shareholder, in a buyback, to promote or maintain on, and should you imagine that the buyback is at too excessive a value, you must promote your shares again.
2. Myths in favor of the argument that buybacks are good and generate extra returns for buyers
Fable 2.1: Buybacks are value-adding as a result of firms that purchase again their very own inventory when costs are decrease than honest worth are taking constructive internet current worth investments.
Actuality 2.1: Buybacks, at any value, can neither add nor destroy worth. They’ll simply switch worth.
That is the inverse of the argument that buybacks are worth destroying and they’re each grounded in a misclassification of buybacks as tasks, relatively than money return, competing with funding tasks for the corporate’s {dollars}. The reality once more is {that a} inventory that buys again inventory at decrease than honest worth is transferring wealth from those that promote again to those that stay, and right here once more, if you’re on the flawed aspect of wealth switch, it was your option to promote again that made you the loser.
Fable 2.2: Buybacks are nearly at all times good for inventory costs, since there are fewer shares excellent after buybacks, and that ought to improve the value per share.
Actuality 2.2: A buyback can improve, do nothing or lower worth per share, relying on the value at which it’s accomplished and its results on leverage.
Buybacks scale back share depend (the denominator) however the money that leaves the agency additionally reduces fir worth (the numerator). A good-value buyback will create offsetting results, leaving worth per share unchanged, although there is usually a secondary impact on worth, if the buyback, by lowering fairness, modifications the debt to capital combine and value of capital for a corporation:
It’s true that empirical proof backs up the notion that inventory costs profit from buybacks, however which may be from the choice bias of beneath levered companies with giant money balances being the largest gamers within the inventory buyback sport.
Basically, nearly all of those myths come out of treating buybacks as one thing new and totally different, relatively than a variant on dividends. Basically, firms that shouldn’t be paying dividends, both as a result of they lack the money or the long run is unsure, shouldn’t be shopping for again inventory both.
Dividend Dysfunction
At first of this put up, I famous that dividend coverage is dysfunctional at many companies, pushed by inertia (we have at all times paid dividends or we have by no means paid dividend earlier than) and the need to hew to see group insurance policies. In consequence, there are lots of firms all over the world that undertake dividend insurance policies that, no less than of the face of it, take explaining together with:
Cash-losing firms that pay dividends: Whereas there are some firms that provide justifications grounded in worries about sending unhealthy alerts or hopes of a bounce again in earnings, many get caught with dividend insurance policies, due to inertia or peer group strain, that may drive them into destroy.Cash-making firms that refuse to pay dividends: Right here once more, there might be good causes for holding again together with issues about whether or not you possibly can maintain incomes and expectations that you will want to speculate extra sooner or later, however in some instances, it will possibly unwillingness to provoke dividends in an business the place nobody else pays dividends.Unfavorable FCFE firms that return money (dividends or buybacks): Along with hopes for a bounce again in FCFE, firms could proceed to return money, even with unfavourable FCFE, as a result of they’re attempting to extend debt ratios or shrink their companies over time. Optimistic FCFE firms that return no money: Corporations which have constructive FCFE that do not return money could maintain again that money due to the need to scale back debt ratios or as a result of they ahve funding plans.
The graph beneath lists out the variety of firms in every group, damaged down by geography:
Throughout the globe in 2025, nearly 18% of money-losing firms paid dividends, as did about 70% of money-making firms. With FCFE as your indicator, about 37% of firms that returned money (in dividends and buybacks) in 2025, had unfavourable FCFE, as did 66% of firms with constructive FCFE.
Conclusion
There are a complete host of misalignments between what firms return to their shareholders, both as dividends or in buybacks, and what they will, as potential dividends. That means to me, and maybe I’m flawed, that funding methods which can be constructed round money return, whether or not they be dividends or buybacks, are more likely to go off the tracks. Moreover, any technique that’s constructed totally round dividends, as is the case with methods the place you load up on excessive dividend yield shares or purchase a handful of heavy dividend payers, such because the Canine of the Dow, misses the essence of fairness investing. A inventory is just not a bond, the place dividends substitute coupons, and also you get some value appreciation on high, and treating it as such will solely create disappointment.
YouTube Video
=
Knowledge hyperlinks
Dividend statistics, by business (US and World)Buyback statistics, by business (US and World)Dividends and Buybacks – Historical past for US companies
Spreadsheets
Buyback inventory value calculator
Knowledge Replace Posts for 2026
Knowledge Replace 1 for 2026: The Push and Pull of DataData Replace 2 for 2026: Equities get examined and go once more!Knowledge Replace 3 for 2026: The Belief Deficit – Bonds, Currencies, Gold and Bitcoin!Knowledge Replace 4 for 2026: The World PerspectiveData Replace 5 for 2026: Threat and Hurdle RatesData Replace 6 for 2026: In Search of ProfitabilityData Replace 7 for 2026: Debt and TaxesData Replace 8 for 2026: Dividends and Buybacks