Crass and mercantile although this will likely sound, the top recreation for a enterprise is to earn a living, and a enterprise that fails this straightforward check can not survive for lengthy, regardless of how noble its social mission, how nice its merchandise and the way a lot it’s beloved by its clients and workers. On this put up, I begin with a protection of this mercantile goal, and argue that makes an attempt to increase it to include social good go away each companies and societies worse off. I have a look at enterprise profitability, first in absolute phrases in 2025, after which relative to revenues, analyzing why revenue margins differ throughout companies and sectors. I then increase the ante and argue that getting cash is simply too low an ordinary to carry corporations to, for the reason that capital invested in these corporations can generate returns elsewhere, opening the door to bringing within the alternative prices (prices of fairness and capital) that I launched in my final put up.
The Enterprise Finish Sport
In 1970, Milton Friedman argued in a New York Instances article that the social duty of a enterprise is to ship (and improve) earnings. That view has come underneath assault in current many years, however even within the speedy aftermath of the article’s look, there was some push again. Some got here from individuals who argued that Friedman was lacking particulars, with just a few noting that it’s cashflows, not earnings, that companies ought to deal with, and others arguing that it’s earnings over the long run, not simply speedy earnings, that must be the main target of a enterprise. My guess is that Professor Friedman would have agreed on each fronts, arguing that he was speaking about financial, not accounting, earnings, and that there was nothing in his mission assertion that foreclosed a deal with long run earnings.
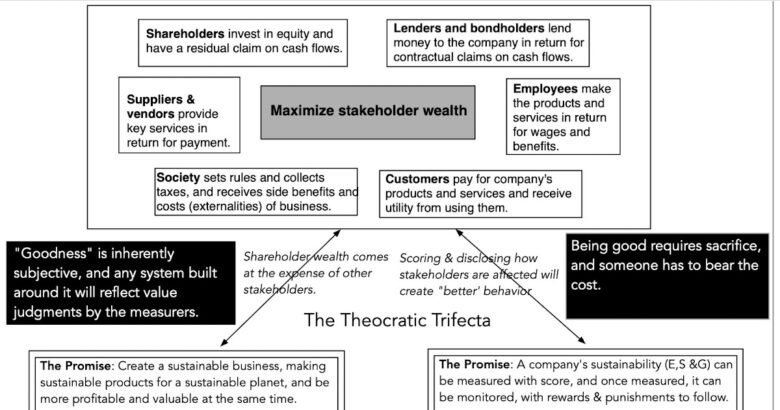
Within the many years since, there was a extra elementary critique of the Friedman enterprise finish recreation, coming from those that imagine that his view is much too cramped and slender a imaginative and prescient for a enterprise, and that companies have obligations to society and the planet that have to be integrated into decision-making. Initially, these critics argued for imposing social and environmental constraints on the profitability goal, and whereas Friedman might have taken subject with a few of these constraints, arguing that that’s what legal guidelines and laws must be doing, he would (in all probability) have gone together with most of them, given actual world frictions. Later, although, these critics determined to go for the jugular, arguing that the enterprise goal itself be reframed to incorporate these broader obligations, with some arguing for stakeholder wealth maximization, the place companies search to maximise worth to their totally different stakeholders (workers, lenders, clients). That concept gained traction amongst some lecturers, a lot of whom by no means grappled with placing this goal into apply in actual companies, and amongst some CEOs, who realized that being accountable to everybody successfully meant being accountable to nobody, however I’m not a fan. About 20 years in the past, stakeholder wealth maximization was supplemented by ESG, an acronym that rapidly received buy-in from the institution. In 2020, after I first checked out ESG, it was on the top of its attract, with funding managers (led by Blackrock), consultants (with McKinsey up entrance) and lecturers, all pushing for its adoption. Given the broad purchase in, I anticipated to see clear and conclusive proof that ESG was not simply good for traders and companies, but in addition for society, and I used to be dissatisfied on each entrance. The alpha that was attributed to ESG in investing was unintended, coming virtually fully from its overload on tech shares in its early years, the proof that ESG helped companies ship larger progress and earnings was laughably weak, and on virtually each societal dimension that ESG was imagined to make the world a greater place, it had failed. Even on threat, the one dimension the place a rational argument could be mounted for corporations following the ESG rulebook, its influence was hazy, with no discernible results on prices of capital and solely anecdotal (and largely ex-post) proof for shielding in opposition to reputational and catastrophic dangers. Within the final 5 years, ESG has fallen out of favor, largely undone by its personal inside inconsistencies, however the gravy practice that lived off its largesse has moved on, and brought a lot of what crammed the ESG house, repackaged it, and renamed it sustainability. Whereas advocates for sustainability attempt to create distance between ESG and sustainability, in my (biased) view, a lot of that dialogue is akin to portray lipstick on a pig after which debating what shade of lipstick fits the pig greatest, quite than trying to create actual change.
It’s with intent, therefor, that I named these three forces – stakeholder wealth maximization, ESG and sustainability – the theocratic trifecta in a put up that I wrote three years in the past, and argued that they failed for a similar causes.
First, by rooting themselves in advantage quite than in enterprise sense, they rendered a disservice to their very own trigger. In spite of everything, when you resolve that you’re on the aspect of goodness, any critics of what you do, regardless of how nicely merited their criticism is perhaps, are rapidly consigned to the badness heap, and never simply ignored, but in addition reviled for missing ethical fibre. The issue, in fact, is that if an motion makes enterprise sense (will increase profitability and worth), you wouldn’t want a advantage brigade to push for that motion within the first place. Second, by leaving the definitions of their central concepts (stakeholder wealth, ESG and sustainability) amorphous, they made it simpler to promote to traders and corporations, however on the expense of consistency and focus. In my 2022 put up on ESG, the place the Russian invasion of Ukraine had compelled its defenders to morph within the face of proof that that world was extra depending on fossil fuels and protection corporations than that they had been prepared to concede in earlier years, I famous the lack of credibility that comes from shifting definitions of goodness. Third, and most critically, of their zeal to push these ideas to a wider viewers and get extra folks to purchase in, they bought a lie, i.e., that you would be able to be good (no matter that definition of fine could also be) with out sacrifice. I don’t know whether or not ESG and sustainability salespeople meant what they stated after they argued that traders might earn larger returns, by including ESG constraints to their portfolios, and that corporations might develop into extra worthwhile, in the event that they integrated environmental and social concerns into resolution making, however my categorization of individuals in these areas as both helpful idiots or feckless knaves stems from a refusal to resist the inherent commerce offs. After many years of pushback from critics of the Friedman enterprise finish recreation, I, for one, imagine that Milton Friedman was proper, and that we might all be higher off to comply with up and ask the query of what could be performed, given that companies are profit-seekers, to advance social good and curb externalities. I do not imagine that the disclosure route, which appears to have develop into the fallback for some searching for higher enterprise habits, will accomplish a lot, and it could do extra hurt than good. Whereas legal guidelines and laws can present a partial repair, they’re blunt devices, and in a setting the place companies can transfer simply throughout borders, they will not be efficient. In the end, we (as shoppers and voter) get the companies we deserve, and if after paying lip service to social causes, we purchase merchandise and vote for governments hat undercut these causes, no acronym or phrase salad will restore the breach.Profitability in Companies
I meant to have a brief lead-in on why profitability issues at companies, however as you possibly can see from the earlier part, I did get aspect tracked, however the underlying message is that getting cash is central to enterprise success and survival, and that measuring profitability is subsequently a obligatory a part of assessing enterprise success and worth.
Financial versus Accounting Earnings
The Friedman view on the enterprise endgame might have been pushed by a imaginative and prescient of financial earnings, however in the actual world, we’re depending on accounting measures of earnings, that are, at greatest, imperfect substitutes for financial earnings. The desk beneath seems at an accounting earnings assertion, highlighting the various measures of earnings – gross, working and internet – that you will see that in it:
Every revenue measure has utility, with gross earnings reflecting unit economics, the distinction between gross and working earnings capturing economies of scale and the distinction between working and internet earnings being pushed by taxes and selections that companies make on debt and non-operating property. In 2025, trying on the mixture values (in thousands and thousands of US $) for these line gadgets throughout sectors, listed below are the numbers, for each world companies and simply the US subset:
Within the mixture, world companies generated $6.2 trillion in internet earnings and $7.7 trillion in working earnings on revenues of $72.4 trillion, in 2025; throughout the identical 12 months, US companies generated $2.2 trillion in internet earnings and $2.9 trillion in working earnings on revenues of $22.7 trillion in revenues. Throughout sectors, and taking a look at revenues, industrials carried probably the most weight for the worldwide pattern, however well being care generated probably the most revenues throughout the US sub-sample.
Earnings scaled to Revenues – Revenue Margins
The issue with greenback earnings is that comparisons throughout corporations, industries or sectors are skewed by scale variations, and one easy scalar for earnings is revenues, yielding variants of revenue margins. If you are undoubtedly acquainted with these margin variants, their actual use in evaluation is in offering perception into enterprise fashions
I’m not a believer in monetary ratio evaluation, however I do imagine that the earnings statements for corporations, particularly examined over time, give us perception into their enterprise fashions and may also help body valuation narratives. Within the desk beneath, I have a look at variations in margins throughout sectors in 2025, once more trying throughout world companies, and simply US companies:
I’ve estimated margins, by sector, utilizing the aggregated greenback values for earnings and revenues from the earlier desk, and likewise reported the cross sectional distribution of company-level margins. Evaluating the aggregated margin with the median margin throughout the sector ought to offer you a way of how top-heavy the sector is when it comes to profitability. In know-how, which has the very best weighted working margin (24.7%) of throughout sectors, the median working margin is just 3.41% (-0.30%) throughout world (US) know-how companies; the larger tech corporations are cash machines in a sector that also comprises loads of youthful and smaller money-losing companies. Observe that the margins should not computed for monetary service companies, since revenues are sometimes unreported (and largely meaningless) and gross and working earnings haven’t got the identical measurement worth as they do for non-financial service companies.
Business Margins and the AI Risk
Breaking down sectors into industries gives extra granular element, and there’s a hyperlink on the backside of this put up that stories the margin statistics, by trade group. On the threat of stating the plain, there are giant disparities on margins throughout industries, reflecting variations in unit economics, economies of scale and leverage, as could be seen on this desk that lists the trade groupings with the very best and lowest aggregated working margins amongst US companies:
At one finish of the spectrum, you will have trade teams like fundamental chemical compounds, which has an aggregated (median) gross margin of 9.31%, making the margin hill a lot steeper to climb, since working margins and internet margins can be decrease. On the different finish of the spectrum, along with tobacco and railroads (stunned, proper?), you will have system and utility software program, delivering an aggregated gross margin of 71.72%, working margin of 33.21% and internet margins of 25.49%, capturing the robust unit economics that characterize the enterprise.
Whereas excessive margins are a fascinating characteristic for a enterprise, these identical excessive margins could make a enterprise weak to disruption, and the AI unload that we now have seen play out in the previous couple of months in software program displays the issues that traders have of AI placing important downward stress on software program margins. In case your pushback is that the drop off in revenues and margins has not occurred but, and that it’s unfair to software program companies to mark their market pricing down preemptively, that is precisely what markets are imagined to do, and these software program corporations benefited earlier of their lives, when market costs had been marked up nicely forward of the run-up in margins. You reside by the sword (expectations of progress and excessive margins), you die by it (expectations that progress charges will hit a cliff and margins will decline)!
Time Developments in Earnings
I’ve tracked revenue margins for corporations for a very long time (about three many years) in my datasets, and there may be clear evidences that they’ve trended upwards in the course of the interval. Within the graph beneath, I have a look at the online revenue margins for the S&P 500 within the mixture on this century (from 2000-2025):
As you possibly can see, internet revenue margins have climbed during the last 20 years for US corporations, with numerous tales competing for why.
Essentially the most cynical clarification is that this improve in margins is all sleight-of-hand, the place accountants are pushing via modifications, aided and abetted by accounting rule-writers, to make corporations look extra worthwhile. As somebody who has taken subject with the gaming of earnings that you simply typically see at corporations, I’m disinclined to take this criticism significantly, since most of the modifications in accounting guidelines (such because the expensing of stock-based compensation and R&D) ought to push earnings down, and accountants have extra energy to maneuver earnings throughout intervals than they do to extend the extent of earnings.A second clarification is that the macroeconomic setting makes it simpler for corporations to ship earnings, and this clarification had resonance when rates of interest had been at historic lows within the final decade. As charges have risen again to extra regular ranges and the financial system limps alongside, I’m skeptical of the reasoning on this clarification.A 3rd clarification, and this one has been eagerly adopted by many on the political left, is that that this displays the rise in bargaining energy for capital, relative particularly to labor, implying that the rise in earnings are coming primarily on the expense of employee wages. Whereas there are definitely pockets of the financial system the place that is true, the margins for many manufacturing and repair companies, which have the very best worker rely and wage prices, have stagnated or decreased during the last 20 years, indicating that neither capital nor labor has benefited a minimum of in these sectors.The fourth, and in my opinion probably the most salient rationale for margin will increase, is that the composition of the market has modified, as know-how corporations supplant old-economy corporations, bringing superior unit economics and economies of scale to play. Put easy, a market that will get the most important portion of its worth from tech corporations will ship a lot larger margins that one which will get a lot of its worth from manufacturing and repair companies.
Ought to we involved that margins might compress sooner or later? After all, and we all the time ought to, however that compression, if it occurs, will rely virtually fully on how the financial system performs and the results of disruption, whether it is coming, for tech corporations.
Worth Creation in Enterprise
If we outline the edge for enterprise success as producing earnings, we’re setting the bar too low for a easy cause. Beginning a enterprise requires capital, and that capital can earn a return elsewhere on funding of equal threat. If these phrases sounds acquainted, it’s as a result of I used them in my final put up on hurdle charges to explain the prices of fairness and capital. Thus, worth creation requires a enterprise to generate a return on its fairness (capital) that exceeds its price of fairness (capital). That may be a easy proposition, and a strong one, however the measurement problem we face is in figuring out the returns that corporations generate, and for higher or worse, we’re depending on accounting measures of those returns. A great way to see what an accounting return is measuring or a minimum of making an attempt to measure is to take a look at returns on fairness and invested capital in a monetary steadiness sheet:
Whereas accounting returns are extensively utilized in apply, as a gauge of funding high quality, they are often skewed not simply by accounting inconsistencies however efforts by accountants to do the “proper factor” (like writing off unhealthy investments. I’ve laid out my issues in exhaustive and extremely boring element on this paper on accounting returns, which is dated, however nonetheless related. I summarize the components that may trigger accounting returns on fairness and capital to deviate from actuality within the image beneath:
With these issues about accounting returns in place, I computed the accounting returns on fairness and invested capital for the entire corporations in my world pattern (48.156 companies) and my US pattern (5994 companies), and the next desk stories the statistics for each teams, by sector:
Once more, I report the accounting returns computed primarily based on aggregated values first, after which the distributional statistics (first quartile, median, third quartile) for the company-level accounting returns. As with revenue margins, you possibly can see that even in sectors the place the aggregated accounting returns are excessive (resembling know-how and communication providers), the median worth displays the fact that the majority corporations in these sectors battle to ship double-digit returns.
Turning again to our worth creation metric, the place we evaluate accounting returns to prices of fairness and capital, you must be constant, evaluating fairness returns to fairness prices and capital returns to capital prices:
The surplus return is a numeric, however as with all numbers in enterprise, it’s value trying behind the quantity at its drivers, i.e., why do some enterprise ship returns that constantly outstrip their prices of fairness and capital, whereas others battle? Essentially the most highly effective explainer of extra returns is just not qualitative, for the reason that capability to generate extra returns comes from limitations to entry and aggressive benefits. Within the language of worth investing, it’s the width (energy of aggressive benefits) and depth (sustainability of aggressive benefit) of moats that decide whether or not an organization can earn greater than its price of fairness or capital:
If you’re on this matter, and it’s a fascinating one, Michael Mauboussin brings his erudition and data into play in this Morgan Stanley thought piece from October 2024.
Since I’ve estimates of prices of fairness and capital for every of my companies (see my final knowledge replace for particulars), I compute extra returns, by sector, for my world and US samples:
Given what you noticed within the final desk, with accounting returns, you shouldn’t be stunned to study that solely 29% (28%) of worldwide companies earn returns on fairness (capital) that exceed their prices of fairness (capital). In actual fact, for those who increase the edge and have a look at corporations that generate 5% or extra as extra returns, the numbers drop off to 19% (17%) for fairness (capital) extra returns. Most corporations have bother incomes their prices of fairness and capital, however for those who have a look at the aggregated values, there are a number of sectors within the US (know-how, shopper items and communication providers) that earn double digit extra returns, pointing once more to bigger corporations inside these sectors with the ability to set themselves other than the remainder.
In case your concern is that the worldwide statistics are being skewed by regional variations, I compute the surplus return statistics damaged down by area:
As you possibly can see, there may be not a single geography the place greater than 50% of companies earn greater than their required returns, with Japan rating highest in percentages and Canada and Australia the bottom. Right here once more, the aggregated values inform a unique story, with US corporations collectively delivering extra returns of 8.44% on fairness and 1.81% on capital, suggesting once more that giant US corporations carry the load of worth creation out there.
Given how a lot time we spend in finance analyzing investments and creating resolution guidelines (NPV>0, IRR>Hurdle price) which are supposed to guard companies from taking “unhealthy” investments, it’s possible you’ll be stunned on the prevalence of worth destroying investments. Among the failure at companies to ship returns on capital that exceed the price of capital might replicate imperfections in our accounting return measures, since it’s primarily based upon earnings in the newest 12 months, and which will bias us in opposition to younger and rising corporations constructing as much as scale. In my guide on company life cycle, I spotlight how accounting returns shift as corporations go from youth to say no:
To see if it is a consider our world findings on extra returns, I break corporations down by age into deciles and compute extra returns throughout these groupings:
The desk broadly displays what you need to anticipate to see, with a company life cycle, because the % of corporations that beat their price of capital improve as corporations age, however the aggregated extra returns peak in center age (the center of the life cycle), extra pronounced with US than world companies.
A Profitability Wrap Up
Wanting on the knowledge, and there’s a hazard right here that I’m overreaching, it appears to me that during the last 4 many years, moats have crumbled, partly because of world competitors and partly due to disruption (which upends companies, turning good companies to unhealthy ones), and the enterprise panorama has tilted extra decisively to bigger companies, as increasingly companies develop into winner(s)-take-all. It’s on this context that I take a extra jaundiced view of what AI will do for firm profitability and worth. I imagine that, as a disruptor, it is going to trigger downward stress on margins at most companies, and improve the benefits that bigger companies have in every enterprise. How do I reconcile this view with the blissful speak of AI as a instrument that can make corporations extra productive, and that the ensuing decrease prices will make them extra worthwhile? Except the AI instruments that you’re speaking about are unique to those corporations, within the sense that rivals can not purchase the identical or equal instruments, these AI instruments will decrease prices throughout the board, and competitors will then kick in on the pricing entrance, decreasing profitability. If that seems like a attain, I’d advocate a revisit of the US retail sector during the last three many years, as on-line retail, initially considered as a boon by brick-and-mortar retail companies, ended up destroying most of them and lowering the margins for retail collectively. As shoppers, we’ll profit, however as traders or workers within the disrupted corporations, we can pay a worth that outweigh the advantages, for a large variety of us. I do assume that the AI disruption can be extra akin to a slow-motion automobile wreck, when it comes to its impact on general profitability, and that the margin slippage will happen over time, however it is going to damaging. Time will inform!
YouTube Video
Datasets
Revenue margins, by trade (US and International)Accounting returns and extra returns, by trade (US and International)
Paper on Accounting Returns (Lengthy and Boring)
Return on Capital, Return on Invested Capital and Return on Fairness: Measurement and Implications
Information Replace Posts for 2026
Information Replace 1 for 2026: The Push and Pull of DataData Replace 2 for 2026: Equities get examined and move once more!Information Replace 3 for 2026: The Belief Deficit – Bonds, Currencies, Gold and Bitcoin!Information Replace 4 for 2026: The International PerspectiveData Replace 5 for 2026: Threat and Hurdle RatesData Replace 6 for 2026: In Search of ProfitabilityData Replace 7 for 2026: Debt and TaxesData Replace 8 for 2026: Dividends and Buybacks