In my first 4 posts, I checked out markets – fairness, debt and collectibles – within the combination carried out in 2025. On this publish, I flip my consideration to divergences in danger throughout firms, different measures of danger, some primarily based on costs and others at earnings, and the way these variations play out in hurdle charges, a crucial ingredient for companies making an attempt to find out whether or not and the way a lot to spend money on particular person initiatives and for buyers making that very same judgment, when firms.
Threat: Definition and Measures
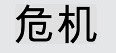
For an idea tas central to investing and company finance as danger is, it’s astonishing how a lot divergence there’s throughout even finance consultants and teachers on what it’s, and consequently on the way to measure it. I’ve heard some describe danger as uncertainty, primarily substituting one fuzzy phrase for one more, others as the specter of grevious loss and nonetheless and nonetheless others as the opportunity of destructive outcomes. When you’ve got taken a finance class, and I confess to having an element on this, chances are you’ll outline danger as volatility or normal deviation, and even convey Greek alphabets into play. My favourite definition of danger and one which I begin my company finance class with is that Chinese language image for disaster or massive danger (and I’m certain that I’ve mangled the symbols, since I’ve been corrected a dozen instances previously):
As somebody who can neither learn nor converse Chinese language, I’m reliant on pals who know the language, and I’ve been advised that the primary of the 2 symbols is the one for hazard and the second is an emblem for alternative. In impact, by bunding collectively hazard and alternative, the chance measure captures how danger each attracts (to get to alternative) and repels (with the specter of hazard). That duality explains why an funding or enterprise technique typically can’t be constructed across the goal of simply minimizing danger, since that successfully will take away entry to alternatives or recklessly chasing after alternatives, ignoring risks
With that definition of danger in place, I’ll begin the dialogue of danger measures by inspecting the alternatives that we face in making the measurement:
Upside versus Draw back: Should you begin with a generic definition of danger as receiving an consequence that’s completely different from what your expectation, it’s value recognizing that a few of these outcomes shall be constructive (higher than anticipated) and a few shall be destructive (worse than anticipated), and that it’s the latter than buyers and companies dislike. Thus, there are some who argue that danger measures ought to concentrate on simply draw back outcomes, not all sudden consequence.Worth-based versus accounting-based: Threat measures which can be primarily based upon information will be constructed on market costs, for publicly traded companies, or on accounting information, particularly earnings. Worth-based measures have the benefit of fixed updating, supplying you with extra information, however are typically contaminated by the noise and volatility that come from buying and selling. Accounting measures yield extra stability, however since they’re up to date occasionally, and accounting smooths adjustments over time, they’ll provide stale or distorted values.Whole versus Non-diversifiable: The chance in an funding, whether or not a venture or a enterprise, can come from many alternative sources, however among the dangers are extra investment-specific whereas others are market-wide:
To the query of why we should always care, the presence of many investments in a portfolio implies that dangers which can be investment-specific will common out, reducing and even disappearing as portfolios get bigger, whereas market dangers stay intact. This perception, which earned Harry Markowitz a Nobel prize, gave start to fashionable portfolio idea and is on the coronary heart of most danger and return fashions in finance.
I’ve my preferences on how finest to measure danger, I wish to preserve an open thoughts and begin by laying out the alternatives we face on risk-measures:
As you possibly can see, the chance measure you select shall be a operate of whether or not you (as an investor or enterprise) imagine that the marginal buyers, i.e., the buyers who personal essentially the most shares in what you are promoting and commerce these share, are diversified or not, and what you imagine about monetary markets and accounting information.
Threat throughout Corporations in 2025
My pattern consists of 48,156 publicly traded companies and on condition that these firms commerce throughout completely different geographies and are in numerous companies, it ought to come as no shock that there are large variations in danger throughout these firms. On this part, I’ll begin with accounting-based measures, with the caveat that accounting requirements range internationally, although IFRS and GAAP have created vital convergence.
Accounting Measures
Whereas there are a selection of accounting metrics that you should use to measure danger, essentially the most logical one to concentrate on is earnings, however you might have many selections. You can use internet revenue or earnings per share, which can mirror not solely the riskiness of the enterprise function in, but additionally the quantity of debt you might have chosen to tackle, or you possibly can used working revenue, extra reflective of simply market danger. Inside every of those metrics, you possibly can measure danger as volatility (in earnings) or in additional simplistic phrases, on whether or not you might have constructive or destructive revenue. For these buyers and companies to whom, it’s debt that’s the danger set off, you possibly can take a look at measures of that debt burden:
Let’s begin with volatility in earnings, the place we’ve got two estimation selections that we should make, earlier than we get began. The primary is historical past, and I compute the usual deviations in working and internet revenue utilizing ten years of earnings information, for every agency, a compromise between a quantity too excessive (the place I lose too many companies in my pattern) and too low (the place I lack sufficient information). The second is that earnings normal deviations in earnings will mirror the extent of earnings, with larger earnings firms having larger normal deviations. To manage for this, I divide the usual deviation of earnings by the common earnings over the ten years, yielding coefficients of variation in earnings. The next desk summarizes the distributional values for this metric, throughout sectors:
It ought to come as no shock that utilities have the least unstable working earnings and have the bottom coefficient of variation on that metric, and that vitality and know-how haver essentially the most unstable working revenue. On a internet revenue foundation, financials and utilities have the bottom volatility in earnings, , and vitality and communication companies have the very best internet revenue volatility.
Should you use the frequency of loss-making, as a danger proxy, the desk under captures variations on that metric throughout sectors on this dimension:
Utilities are once more the least dangerous sector, with a decrease proportion of cash losers than some other sector, and well being care and know-how companies have a better % of cash losers than different sectors.
Whereas there are some who use debt hundreds as proxies for firm danger, and we are going to come again and take a look at variations throughout sectors and industries in a later publish, it’s a slender measure, since a younger, dangerous, excessive progress firm with no debt can be labeled as low-risk, if it’s not debt-laden.
Worth-based Measures
All the shares in our pattern are publicly traded, and consequently, you should use market costs to measure danger. That stated, liquidity is a wild card, excessive in some markets and low in others, and that may trigger distortions within the comparability.
1. Excessive and Low Costs: One of many easiest measures of worth volatility is the vary of costs, with wider divergences between excessive and low costs at extra dangerous firms and smaller ones at safer firms:
HiLo Threat Measure = (Excessive Worth – Low Worth)/ (Excessive Worth + Low Worth)
I computed this statistic for every firm in my pattern, after which the averages throughout firms in every business, and it ought to be decrease (larger) for safer (riskier) shares. Utilizing my international information, that is what this statistic appears to be like like, throughout sectors:
Utilities once more are available as most secure, utilizing this danger metric, tied with actual property, and well being care has the widest worth ranges of the businesses in my pattern.
2. Normal deviation in worth adjustments: This can be a normal statistical assemble, and measures volatility in a inventory, although it doesn’t distinguish between upside and draw back volatility. Primarily based upon the company-specific normal deviations, once more averaged out throughout sectors, here’s what the numbers appeared like in 2025:
Financials and utilities are the 2 most secure sectors, and know-how and well being care are the riskiest, in case you measure danger with normal deviation.
3. Betas: Should you purchase into the notion that the buyers setting costs are diversified, and thus care solely about danger that can not be diversified away, you’ll focus solely on the portion of the usual deviation in a inventory that comes from the market, and betas, however the misinterpretations and misreading, try to measure that non-diversifiable portion of ordinary deviation and scale round one. Once more, wanting throughout industries, I take a look at the distribution of betas, by sector:
If you’re concerned about a much less broad categorization, you possibly can try betas by business on the finish of this publish.
As you evaluation the sector rankings utilizing the various danger measures, you possibly can see why the heated debates about which danger measure to make use of is usually overdone, since they, for essentially the most half, rank the sectors equally, with the sectors having much less earnings volatility and fewer money-losers additionally having much less volatility in inventory worth, smaller worth ranges and decrease betas.
Hurdle Charges
Whilst we wrestle with selecting between worth and accounting-based measures, it’s value remembering that the top sport right here is just not the chance measure itself, and that danger measures are a way to an finish, which is estimating hurdle charges. Hurdle charges come into play for each companies and buyers, setting thresholds that they’ll use to find out whether or not to speculate or not:
There are some buyers and companies who imagine that hurdle charges come from their guts, numbers that mirror private danger aversion and previous experiences, however hurdle charges are alternative prices, reflecting returns that buyers (companies) can earn available in the market on investments of equal danger.
Within the context of a enterprise, which raises cash from debt and fairness, you possibly can take a look at hurdle charges by way of the eyes of the capital suppliers – a price of fairness, capturing what fairness investor believers count on to make on different fairness investments of equal danger, and a price of debt, what lenders can earn on lending to others with comparable default danger:
That’s what all danger and return fashions attempt to do, albeit with completely different levels of constancy to the precept. In actual fact, my use of an implied fairness danger premium within the estimation of the price of fairness is designed to advance this trigger, since it’s model-agnostic and displays what buyers are pricing shares to earn, on an annual foundation. Thus, while you use the beta within the capital asset pricing mannequin to derive the price of fairness, try to be computing the return you possibly can earn elsewhere available in the market on different investments with the identical beta, making the price of fairness the hurdle charge for fairness investments in a venture or firm. The price of capital, which incorporate the price of borrowing into its assemble, can also be a hurdle charge, albeit to each debt and fairness suppliers:
As to the query of which of those hurdle charges it’s best to use as a enterprise, the reply lies in consistence. If you’re fairness returns (return on fairness or an inside charge of return primarily based on fairness money flows alone), try to be measuring up towards simply the price of fairness. Alternatively, with returns on invested capital or an inside charge of return primarily based upon cashflows to the enterprise (pre-debt), it’s the price of capital that comes into play.
I compute the prices of fairness and capital for all 48,156 companies in my pattern, and in doing so, and within the pursuits of consistency and ease, I make some simplifying assumptions:
As soon as I’ve the prices of fairness and capital for every agency, I compute business averages, each for international companies, and by area (US, Japan, Europe, Rising Markets, with India and China as sub-categories). You’ll find the hyperlinks to the info on the finish of this publish, however there’s one other perspective that you could convey to the price of capital dialogue, primarily based upon the place an organization falls within the firm life cycle:
Intuitively, you’d count on extra uncertainty about enterprise prospects with youthful companies, than older ones, particularly on the estimation entrance. That stated, it’s an open query of whether or not this uncertainty will translate into larger prices of fairness and capital, because it is dependent upon who the marginal buyers in these companies are, and whether or not the chance is diversifiable (and never have an effect on value of fairness) or non-diversifiable. To reply these questions, I classify companies into ten deciles, primarily based on their company age, and compute prices of capital:
As you possibly can see, there isn’t a discernible sample on prices of fairness, as you go throughout the age courses. Nonetheless, as companies age, they do borrow extra, partly as a result of their capability to generate earnings enhance, and that does have some affect on the price of capital, particularly with the oldest companies available in the market.
In company finance and valuation, an undervalued talent is having perspective, a way of what includes typical, and what’s a excessive or a low worth. It’s for that cause that I additionally compute a histogram of prices of capital of all publicly traded companies in the beginning of 2026:
This desk is one on my most-used, for a lot of causes. First, when doing my very own valuations, particularly for younger companies or for companies the place the price of capital is in flux, it offers me the enter to us. Thus, if I’m valuing a small, AI agency that has simply gone public and has international operations, in US {dollars}, I’ll begin the valuation with a price of capital of 11.66% and transfer that value of capital over time in direction of 8.65%, as its will get bigger and extra established. Second, I do see (and should evaluation or grade) different folks’s valuations greater than I do my very own, and this desk operates as a plausibility test; a valuation of a publicly traded US firm that has a greenback value of capital of 14% goes on my suspect listing, since that’s effectively above the ninetieth percentile for US companies. Third, the desk operates as a reminder that any analysts the place the majority of the time is spent estimating and finessing the price of capital is time ill-spent, for the reason that 80% of all US (international) firms have prices of capital between 5.26% (6.28%) and 9.88% (11.66%).
For these working in numerous currencies, the inflation differential method that I described and used within the final publish can be utilized to transform your complete desk. Thus, if you employ the anticipated inflation charges of two.24% and 4.00% for america and India, from the IMF forecasts, you possibly can 1.76% to every of the numbers to every greenback value of capital that you just see within the desk or as an business common.
Conclusion
To run a enterprise or spend money on one, you want hurdle charges, and that’s what prices of equi6y and debt measure. Whereas fashions and equations could also be the way you get these numbers, it’s at all times value going again to first ideas, everytime you face questions on what to do. Thus, recognizing that the price of capital is a chance value, i.e., the speed of return you possibly can earn elsewhere available in the market, on investments of equal danger, ought to be a immediate to make use of betas that mirror the chance in investments, somewhat than the entities making the funding, and up to date prices of borrowing for the price of debt. As we enter 2026, we at the moment are in our fourth 12 months with US greenback riskfree charges round 4%, and firms and buyers appear to have develop into acclimatized to the ensuing prices of capital, and the shock of seeing greenback riskfree charges surge in 2022, pushing up prices of capital throughout the board appear to have pale.
YouTube
Datasets
Earnings variability, by business (World in 2025)Cash making and dropping percentages, by business (World in 2025)Pricing danger measures, by business (World in 2025)Betas by business group (US, World, Japan, Europe, Rising Markets, India & China)Value of capital by business group (US, World, Japan, Europe, Rising Markets, India & China)
Knowledge Replace Posts for 2026
Knowledge Replace 1 for 2026: The Push and Pull of DataData Replace 2 for 2026: Equities get examined and cross once more!Knowledge Replace 3 for 2026: The Belief Deficit – Bonds, Currencies, Gold and Bitcoin!Knowledge Replace 4 for 2026: The World PerspectiveData Replace 5 for 2026: Threat and Hurdle RatesData Replace 6 for 2026: In Search of ProfitabilityData Replace 7 for 2026: Debt and TaxesData Replace 8 for 2026: Dividends and Buybacks